Fear of rising interest rates is rattling the supply-demand dynamics of Samsung Electronics and SK hynix, the two flagship semiconductor stocks on the Korean market. While it is typical for one group of investors to absorb shares when another sells heavily, retail investors and foreign investors have recently been net sellers of both Samsung Electronics and SK hynix at the same time.
SK hynix has seen an even more unusual situation: institutions have joined the selling as well, meaning all three major investor groups — retail, foreign and institutional — have been offloading shares simultaneously, a rarely seen phenomenon.
According to Korea Exchange data released Monday, retail investors net sold approximately 11.5 trillion won ($8.54 billion) worth of SK hynix shares in the month from Aug. 11 to Friday — the heaviest net selling of any stock among retail investors during that period. Samsung Electronics was second, with retail investors net selling approximately 7.9 trillion won worth of shares. Samsung Electronics preferred shares, however, saw net purchases of around 800 billion won.
Foreign investors moved in the same direction. Over the same period, they net sold approximately 4.4 trillion won worth of SK hynix shares, making it the stock they shed most heavily. Samsung Electronics preferred shares ranked second with approximately 1.4 trillion won in net selling, while Samsung Electronics common shares also appeared in the top net-sold list at around 500 billion won.
Institutions added to the pressure on SK hynix, net selling approximately 2.5 trillion won worth of shares. That made SK hynix the top net-sold stock for each of the three major investor groups individually. Over the past month, SK hynix was the single stock that all three major investor groups in the domestic market sold most heavily.
The primary driver behind this unusual synchronized selling is a resurgence of "high-rate fears." Growing concerns over inflation fueled by elevated oil prices have pushed US market interest rates sharply higher, and wariness that the Federal Reserve could resume benchmark interest rate hikes is weighing on equities broadly. The yield on the 10-year US Treasury note — the global benchmark for bond rates — has crept close to 5 percent, dampening appetite for risk assets.
Rising rates hit large-cap technology stocks like Samsung Electronics and SK hynix particularly hard. When interest rates climb, the discount rate applied to a company's future earnings rises as well. In simple terms, the higher a stock's valuation is tied to expectations of future growth — such as gains from AI and the HBM market — the more its present value erodes when rates rise.
For investors, the incentive to hold equities also weakens. When the 10-year US Treasury yield approaches 5 percent, investors can expect strong returns simply by holding relatively safe US government bonds instead of price-volatile stocks. As rates rise, the expected return investors demand from equities rises with them, intensifying profit-taking pressure especially on technology stocks that have already rallied sharply.
For foreign investors, global capital allocation adds another layer of pressure. Higher US rates increase the appeal of dollar-denominated assets such as US Treasuries, while reducing the incentive to allocate to emerging-market equities including Korean stocks. This means foreign capital can flow out even without any immediate deterioration in the earnings outlook for Samsung Electronics or SK hynix.
A slowdown in the domestic market's upward momentum has also dampened investor sentiment. On top of that, financial regulators tightened rules on single-stock leveraged ETFs — instruments that had significantly boosted trading in Samsung Electronics and SK hynix in the first half of this year — reducing short-term, high-risk demand for semiconductor shares. Analysts say the combination of weakening risk appetite from rising rates and a simultaneous pullback in leveraged investment demand amplified the selling by both retail and foreign investors.
Despite all three investor groups selling, share prices have not collapsed as sharply as the volume of net selling might suggest. Large-scale share buybacks are seen as a key reason.
In the stock market, every seller requires a buyer on the other side. In recent trading flows, that role has been played by "other corporations" — a category tracked separately from retail investors, foreign investors and institutions.
Over the same period, other corporations net bought approximately 18.5 trillion won worth of SK hynix shares, in effect absorbing most of the supply offloaded by the other three groups. For Samsung Electronics, other corporations net bought approximately 7.5 trillion won.
Large-scale share buybacks are identified as the key structural factor enabling this dynamic. SK hynix's aggressive buyback program has created a situation where the company's own purchasing absorbs shares even as retail investors, foreigners and institutions sell simultaneously. Samsung Electronics' ongoing buyback is playing a similar role in soaking up selling pressure.
Normally, simultaneous net selling by retail investors, foreign investors and institutions would raise the likelihood of a sharp drop in share prices. This time, however, the emergence of other corporations and share buybacks as powerful buyers has prevented the synchronized selling from translating directly into a steep decline.
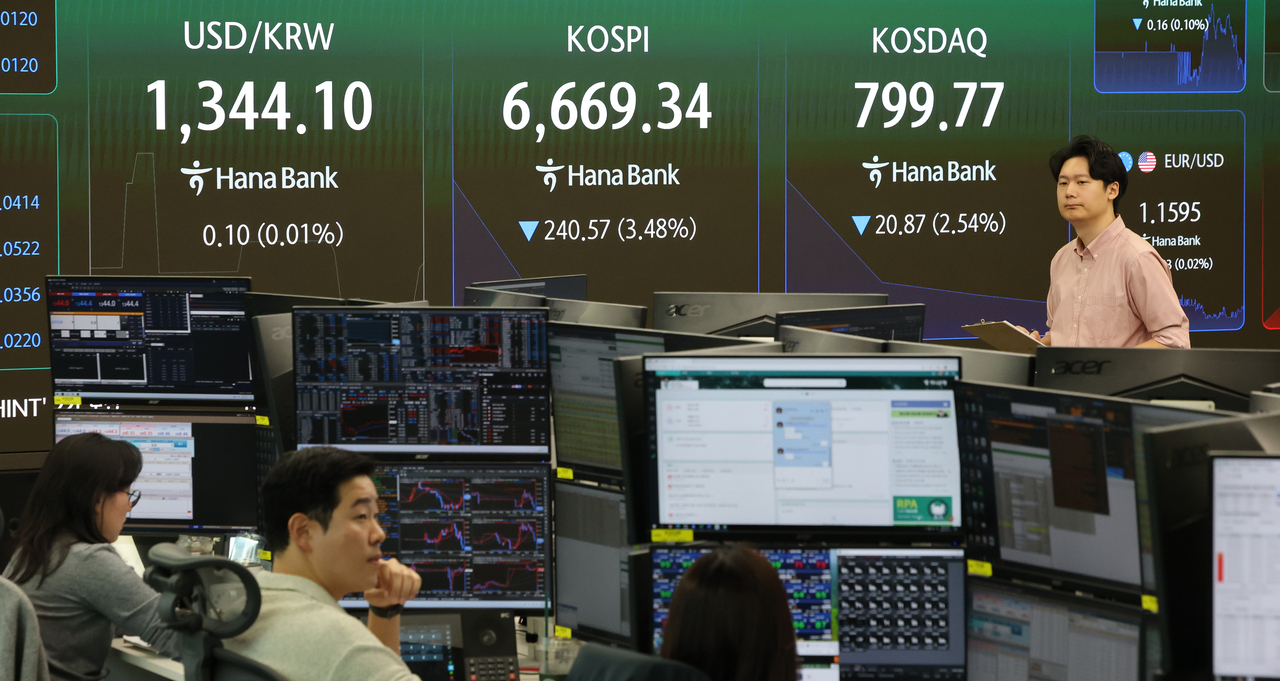
Ultimately, the recent supply-demand picture for Samsung Electronics and SK hynix can be read as two forces in opposition. On one side, rising US rates, risk aversion and a pullback in leveraged investment are building selling pressure from retail investors, foreign investors and institutions. On the other, large-scale share buybacks are absorbing that supply and providing a floor under share prices.
Market participants are watching the trajectory of US interest rates after the next Federal Open Market Committee meeting as the key variable that will determine the direction of semiconductor stocks. If US rate increases ease, selling pressure from foreign investors could also moderate — but if high rates persist for an extended period, buybacks alone may not be enough to offset the supply overhang, analysts say.
"The absolute level of interest rates can be a burden for growth stocks," said Kim Jun-young, a researcher at iM Securities. "Noise over the weekend about the pace of AI investment and development will likely keep markets unsettled." He added that US equities, being less exposed to AI than Korean stocks, appear more likely to extend their record-high rally, and that "it is still a bit early to reduce preference for equities as an asset class."
th5@heraldcorp.com