Samjong KPMG report on global fintech investment trends and H2 2026 outlook
Fewer deals but larger bets signal deepening 'selective concentration' in H1
AI advancement, agentic commerce and tech sovereignty among key H2 themes
The global fintech investment market is recovering rapidly, driven by large-scale mergers and acquisitions. While deal count has fallen, total investment volume has surged, and a pattern of "selective concentration" — capital flowing to proven market leaders with demonstrated growth and profitability — is becoming increasingly pronounced.
According to a report released Tuesday by Samjong KPMG on global fintech investment trends and the H2 2026 outlook, global fintech investment in the first half of this year reached $103.1 billion, a 42.8 percent jump from $72.2 billion in the second half of last year. The number of transactions, however, fell to 2,100 — down 400 from the prior half.
The divergence between investment volume and deal count reflects investors pouring large sums into established market leaders with proven track records.
The largest fintech deal of the half was Global Payments' acquisition of electronic payments and banking platform Worldpay, valued at $24.3 billion. In second place, US-based FIS acquired Total System Services — Global Payments' card-issuing solutions unit — for $13.5 billion.
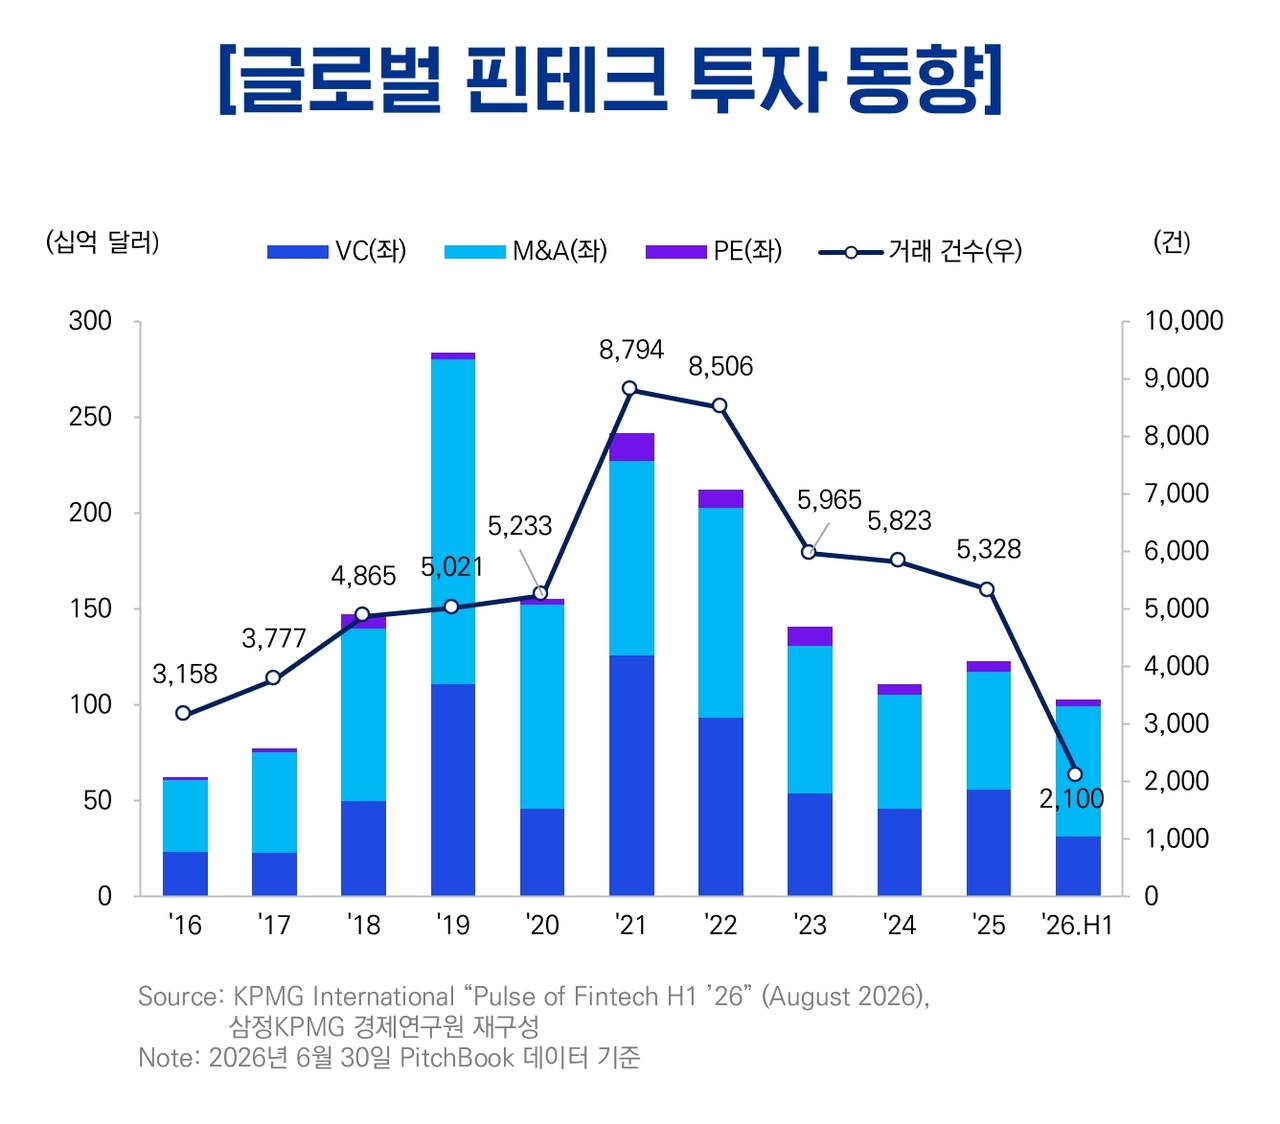
By investment type, M&A led the market recovery, accounting for 65.9 percent of total investment at $67.9 billion across 394 deals. Venture capital investment came in at $31.5 billion, a slight decline from $32.3 billion in the second half of 2025, though it maintained a solid pace. Private equity investment hit $2.6 billion in the second quarter of this year, its highest level in 11 quarters.
By region, the Americas dominated the global market with $86.9 billion across 1,120 deals. The United States alone accounted for $80.8 billion and 933 transactions, driving the bulk of activity. Europe, the Middle East and Africa ($11.3 billion, 626 deals) and Asia-Pacific ($4.6 billion, 350 deals) lagged behind.
By sector, payments attracted the most capital at $44.2 billion. Despite the payments market entering a mature phase, large deals continued to concentrate around fintech companies with validated business models.
The digital assets sector drew $11.1 billion in investment. The pace of deployment has slowed somewhat due to regulatory uncertainty, including doubts over whether the US Digital Asset Market Clarity Act will be enacted this year. Investor interest in market institutionalization centered on stablecoins and the diversification of business models, however, has remained steady.
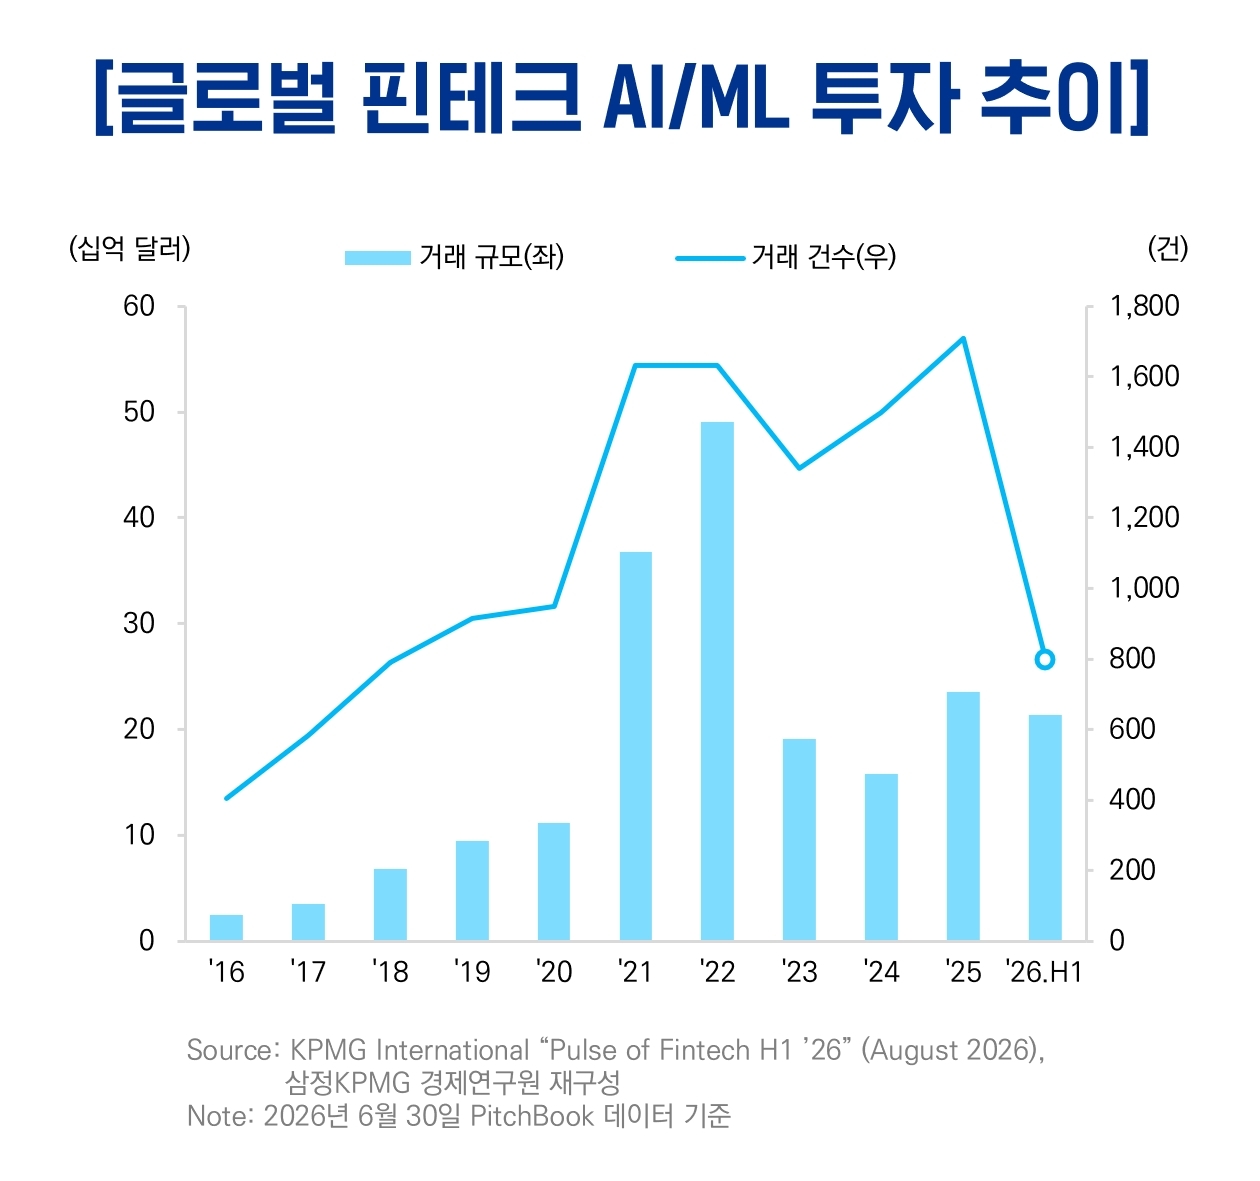
Investment in AI and machine learning also emerged as a core area, reaching $21.4 billion across 800 deals. The trend is expected to continue as financial institutions move beyond simply integrating AI into services and toward redesigning their operational processes and customer touchpoints.
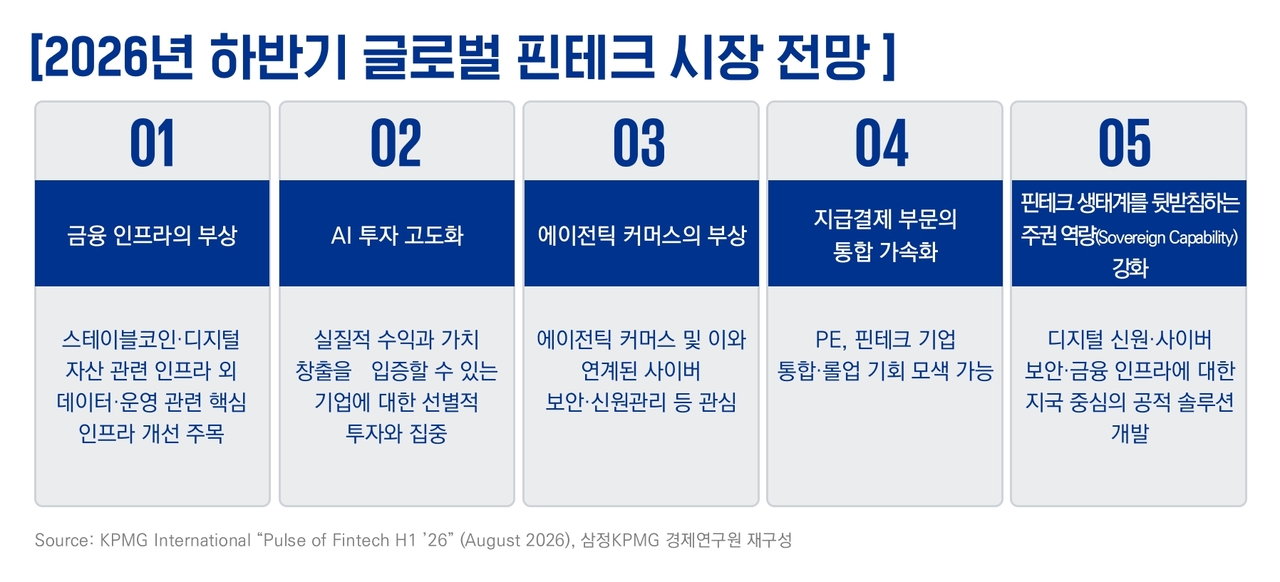
The report identified five key fintech trends to watch in the second half of this year: expanded investment in financial infrastructure, more advanced AI investment, the spread of agentic commerce, accelerated consolidation in the payments sector, and the development of sovereign capabilities to support fintech ecosystems.
Financial infrastructure is emerging as a prime investment destination on the back of stablecoin and digital asset market growth, while AI investment is entering a phase of real-world profitability validation, the report said. The rise of agentic commerce — where AI agents handle shopping and transactions on behalf of users — is drawing heightened attention to related fields such as cybersecurity and digital identity management. Meanwhile, consolidation in the payments industry and intensifying competition among nations to secure technological sovereignty are expected to accelerate.
"AI will become the top priority for fintech investors going forward," said Kim Se-ho, Samjong KPMG's digital finance and fintech industry leader. "The domestic market should also pay close attention to the growth potential of the digital asset market, including stablecoins, as legislation on a basic digital assets law is expected to be enacted in the second half of this year."
Meanwhile, Samjong KPMG, which closes its books in March, posted operating revenue of 905.6 billion won ($673 million) for the fiscal year running April 2025 through March 2026 — a roughly 3.4 percent increase from the prior year — crossing the 900 billion won threshold for the first time.
an@heraldcorp.com