EY Korea survey covers independent directors, auditors and executives at listed firms
68% cite K-IFRS 1118 as top year-end priority
Most expect sustainability disclosure to demand massive resources
Only 7% have active AI inventory or completed high-impact AI review
With a new international accounting standard set to take effect in 2027, only one or two in 10 domestic companies have completed preparations, a survey shows — and the gap between large and small firms is widening fast, raising urgent calls for action.
EY Korea announced the findings Friday, drawing on a survey conducted among independent directors, auditors, audit committee members and executives at listed and major domestic companies who attended the firm's seventh annual accounting transparency seminar.
According to the survey, 68 percent of respondents identified the adoption of K-IFRS 1118 — "Presentation and Disclosure in Financial Statements" — as the single most important task to prepare for ahead of this year's year-end closing. That figure far outpaced other concerns, including responses to high exchange rates and high interest rates, which were cited by 36 percent, underscoring how central the new standard has become to corporate closing preparations.
K-IFRS 1118, which takes effect Jan. 1, 2027, overhauls the structure of the income statement under international financial reporting rules. While the standard is expected to bring sweeping changes to financial reporting and disclosure, only 16 percent of respondents said they had fully completed preparations — including reviews of accounting policies and documentation of key judgments.
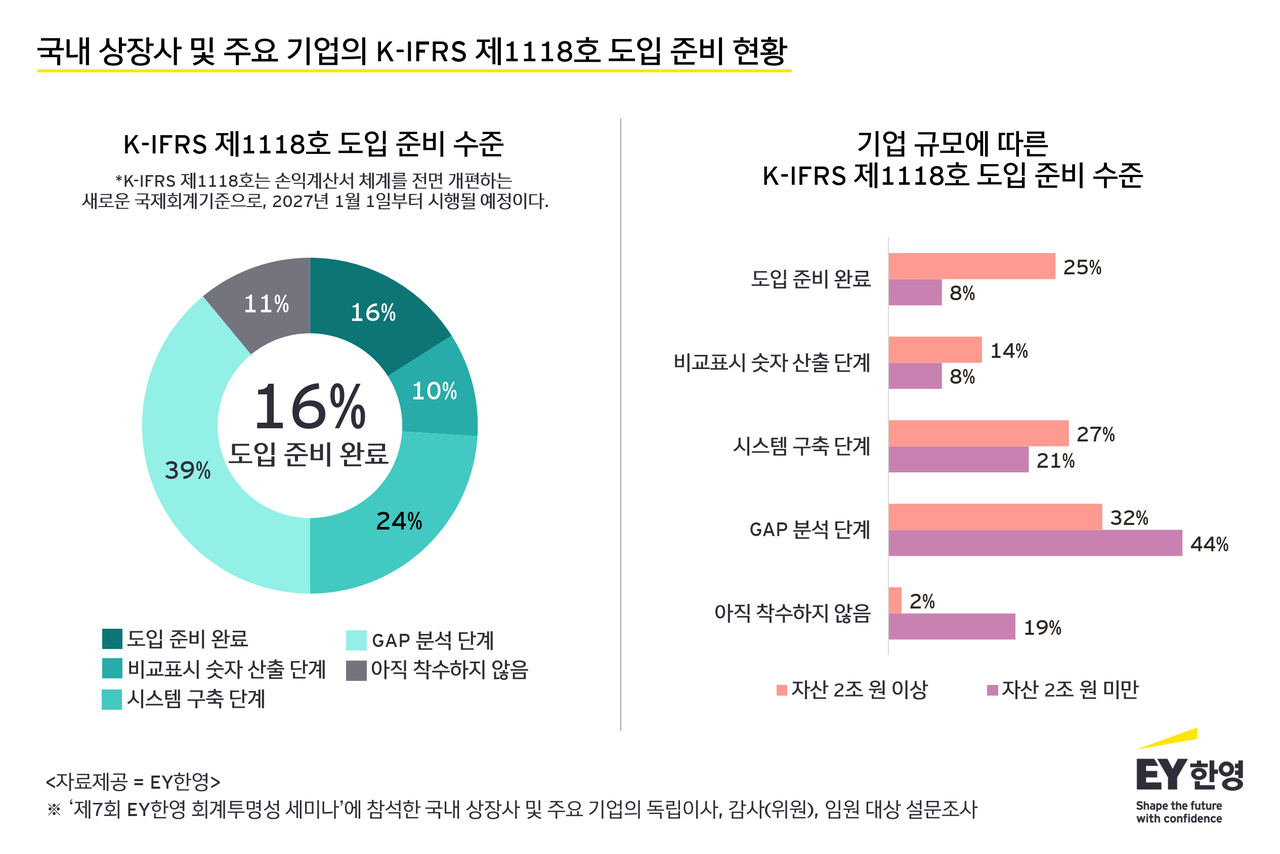
The readiness gap was stark by company size. Among firms with assets of 2 trillion won ($1.46 billion) or more, 25 percent had completed preparations and 41 percent had entered the system-building and comparative-figure calculation stage. At firms with assets below 2 trillion won, the completion rate stood at just 8 percent, and 23 percent of companies with assets under 500 billion won had not even begun preparations.
Sustainability disclosure also emerged as a significant source of concern. Some 76 percent of respondents said they expected sustainability disclosure requirements, once introduced, to bring real changes to management strategy and business operations. Some 80 percent anticipated that the effort would require more personnel and cost than either the full adoption of IFRS or the mandatory introduction of internal accounting management systems in the past. Sustainability disclosure is a regime under which companies report environmental, social and governance information — along with climate-related risks and opportunities — to investors.
Continuous risk-monitoring systems, which form the foundation of regulatory compliance, were also found to be underdeveloped. Only 13 percent of companies said they had fully embedded a firm-wide continuous risk-monitoring framework for identifying, assessing and managing current exposures. By contrast, 58 percent of respondents said their systems were either nonexistent, still under review or in pilot operation, or operational but limited in practice — a figure that climbed to 72 percent among firms with assets below 2 trillion won.
Audit committees were also found to rely heavily on after-the-fact reporting. The most common oversight approach — cited by 51 percent — was reviewing regulatory risks through post-event reports at quarterly meetings, while only 26 percent said they had a system in place to receive continuous monitoring indicators.
Preparedness for shifting global AI regulation was similarly lacking. Just 7 percent of companies said they were actively using an "AI inventory" — a tool for cataloging AI systems in use and evaluating and managing high-impact AI — in response to regulatory changes such as Korea's AI Basic Act and the EU AI Act. Some 57 percent of respondents said they were either still building their AI inventory or had one but had not yet assessed which systems qualified as high-impact AI, while 36 percent said they had no AI inventory at all.
"In an era of compounding risks — where new accounting standards, sustainability disclosure and AI regulation are all tightening at once — the gap in risk exposure between companies that have built proactive compliance frameworks and those that have not will widen sharply," said Lee Dong-geun, EY Korea's head of quality and risk management. "An AI inventory is the starting point for AI governance, and companies must use it to build appropriate internal controls and risk management systems."
Meanwhile, EY Korea said it continued to grow in its fiscal year 2024 — covering July 2024 through June 2025 — posting total sales of 764.8 billion won and operating profit of 13.9 billion won.
an@heraldcorp.com