'Tax reform needed first to shift household funds to capital markets'
Researchers propose adjusting property holding taxes, expanding ISA benefits
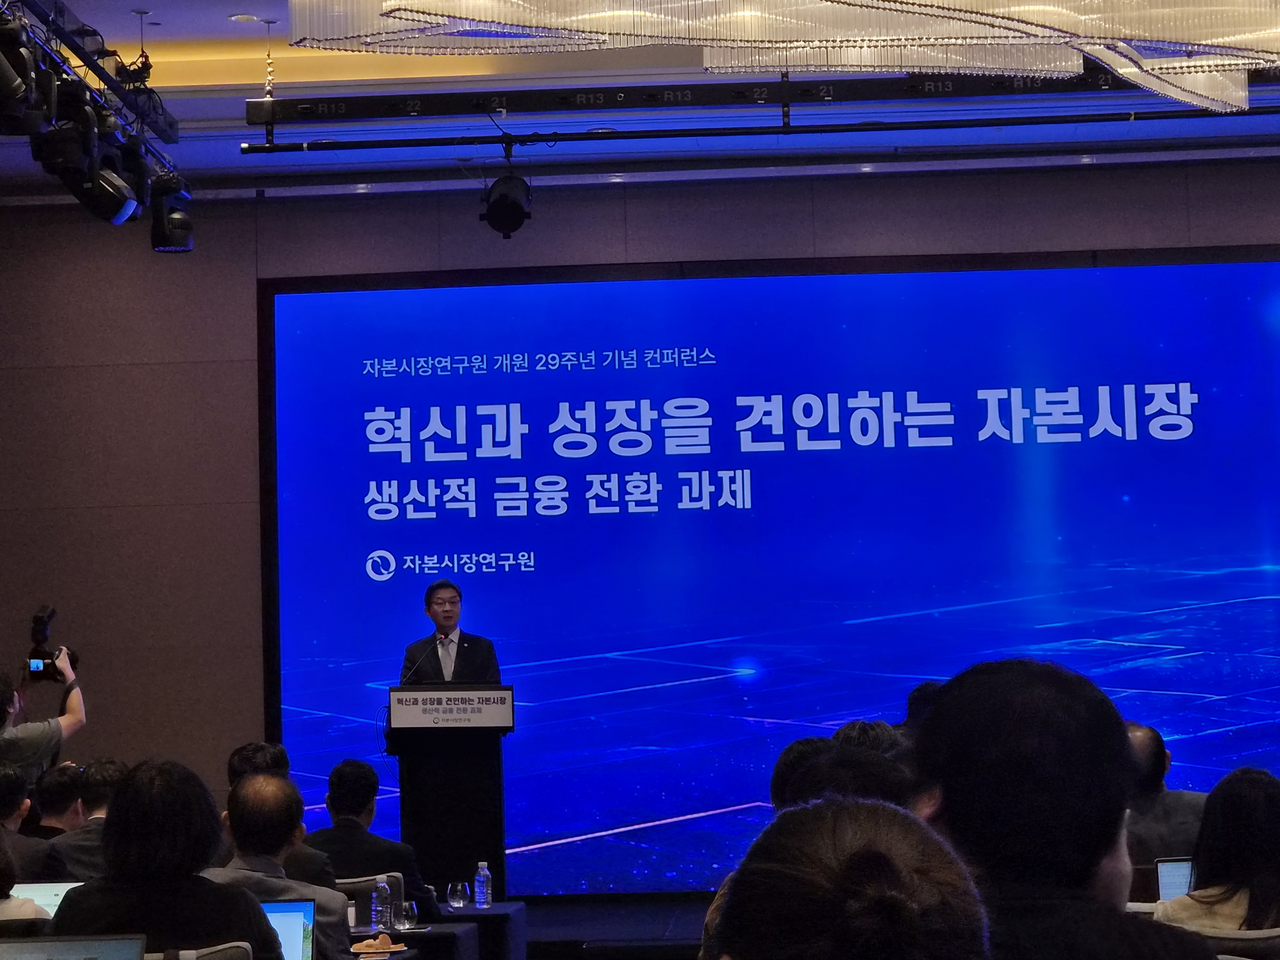
Seoul real estate delivered an after-tax annual return of 11.6%, the highest among major investment assets, according to new research. While the findings suggest households had rational grounds for concentrating wealth in property — given its risk-adjusted performance — researchers called for tax reforms to redirect household funds from real estate into financial investment products.
The Korea Capital Market Institute presented the findings Friday at its 29th anniversary conference at Conrad Hotel in Yeouido, Seoul. The results came from a joint study by Lee Hyo-seop, a senior research fellow at the institute, and Hong Byeong-jin, head of the tariffs research team at the Korea Institute of Public Finance.
The research team simulated 20-year investment returns across major asset classes and found that Seoul real estate's after-tax annual return of 11.6% outpaced nationwide real estate (7.2%), the S&P 500 (7.1%), Kospi (6.0%), public funds (5.7%) and equity-linked securities (2.1%).
The study found that the heavy concentration of domestic household assets in real estate is a natural outcome when both returns and risk are considered. In an optimal portfolio calculated to reflect after-tax returns and risk, real estate accounted for 67.1% — closely mirroring the actual share of real estate in household assets, which stood at 64.5%.
"It is hard to fault households for holding large amounts of real estate in the past, given its strong risk-adjusted performance," Lee Hyo-seop said. "For innovative growth and to raise potential growth rates, we need a structure that moves household funds into financial investment products." He added that actively shifting money away from real estate and bank deposits toward capital markets is essential to boosting total factor productivity and long-term growth potential.
The researchers set a target of reducing the share of real estate in household assets from the current 64.5% to 50% over the next decade, while raising the share of financial investment products from 8.5% to 20%. They argued that narrowing the gap in after-tax returns between asset classes is a prerequisite for redirecting funds locked in real estate toward financial investment.
To that end, the study proposed gradually adjusting property holding taxes while offering tax incentives when proceeds from real estate sales flow into capital markets. The proposals also included expanding tax benefits under individual savings accounts, and introducing, over the medium to long term, loss offsetting across financial investment income and the carryforward of investment losses.
The researchers also outlined measures to enhance the long-term appeal of domestic equities, proposing a gradual easing of the conditions for separate taxation of dividend income and offering tax benefits for long-term share holdings. "The requirements for separate taxation of dividend income on domestic shares are currently very strict," Lee said. "We need to ease them gradually to raise dividend yields further and foster a culture of dividend investing."
The study also identified the patchwork of tax rules applied differently across financial products as an area in need of reform. It proposed harmonizing the treatment of funds, discretionary accounts, trusts, equity-linked securities and derivative-linked securities under a "same asset, same tax" principle, and called for the eventual consolidation of various tax-advantaged accounts into a single "productive finance ISA."
The analysis drew on monthly return data from January 2023 through December 2025, incorporating taxes and the opportunity cost of investment. Returns were calculated to reflect real-world conditions by comparing two scenarios: investing in financial products while renting on a jeonse basis rather than buying, versus purchasing a home with a mortgage for owner-occupancy.
kacew@heraldcorp.com