① Solidigm does not urgently need a large capital infusion — yet certain parties stand to gain enormously from a listing.
② Transactions barred among SK affiliates in Korea face no such restrictions at Solidigm, a US-incorporated entity.
③ The more "they" profit from the Solidigm IPO, the less is left for the true owners: SK hynix shareholders.
④ A price return swap (PRS) structure was used to sell the SK Group stake of Chairman Chey Tae-won, who faces a court-ordered asset division.
⑤ For Solidigm to keep outperforming, SK hynix may have to keep making concessions — or sacrifices.
SK Group investors are facing a complex equation. The variables — Solidigm's planned initial public offering and Chairman Chey Tae-won's divorce litigation — may seem unrelated at first glance, but they are intertwined. Many of the variables remain unknown. Plugging in the values one by one reveals a structure that may not be particularly welcome news for ordinary shareholders of SK hynix, widely regarded as a "people's stock."
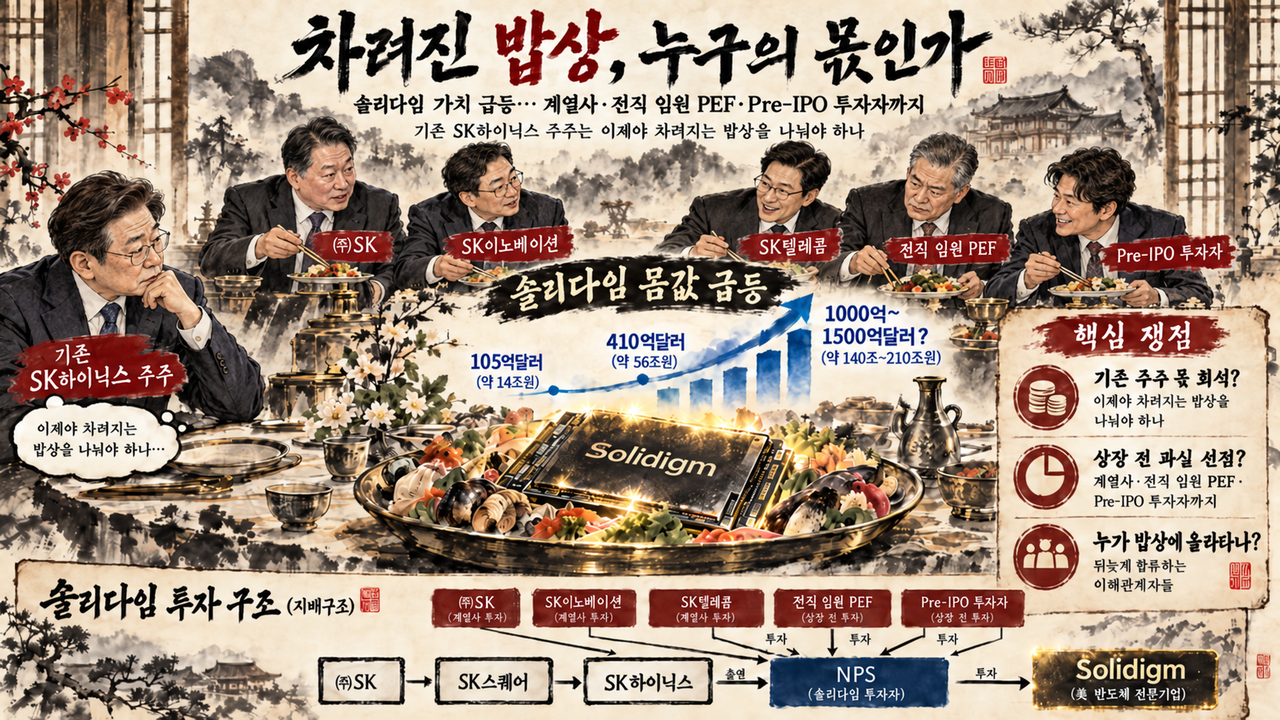
Bloomberg reported Thursday that Solidigm, a subsidiary two levels below SK hynix, has selected Goldman Sachs and Morgan Stanley as underwriters for its IPO. The listing is most likely to take place in 2027, with an estimated valuation of $100 billion and potential proceeds of around $10 billion. The underwriters are also said to be pursuing a pre-IPO round with two investors that could raise up to $7.2 billion.
Does Solidigm really need $17 billion from outside investors?
Does Solidigm truly need to raise as much as $17.2 billion in external capital? Reuters has reported that Solidigm is exploring its first NAND production base on the US East Coast, with New York state mentioned as a candidate. The required investment would vary widely depending on the type of facility. A back-end plant for SSD assembly and testing could be built for a few billion dollars, but a front-end fab for wafer production could easily exceed $10 billion in its first phase alone.
SK hynix's interim financial statements as of late June show that NPS (SK hynix NAND Product Solutions Corp. and its subsidiaries), which includes Solidigm, posted net assets of 8.23 trillion won ($6.14 billion) and first-half net profit of 5.84 trillion won. In the same period last year, those figures were 2.27 trillion won and 132.1 billion won, respectively. A rough estimate based on the performance trends of rivals Kioxia and SanDisk suggests Solidigm's full-year net profit this year could reach 14 trillion to 16 trillion won, with some projections pointing to more than 20 trillion won in 2027.
Assuming current industry conditions hold to some degree, cumulative earnings from the second half of this year through 2029 could reach $30 billion to $40 billion. Even if conditions deteriorate sharply from 2028 and profits fall by half, the accumulated earnings would still be substantial. Add depreciation, and operating cash flow would exceed net profit. Building a large-scale front-end fab in the United States would require enormous capital — but whether that money truly needs to come from outside investors is a question worth examining.
The chairman's divorce and a 944 billion won asset division
Chey Tae-won recently agreed to sell 944 billion won worth of his personal stake in SK Inc. — the same amount set by a court in the retrial of his divorce case against Noh So-young, director of Art Center Nabi.
As a sale by a major shareholder, the transaction carries capital gains tax based on the acquisition cost, plus transaction fees. The exact tax liability depends on the original cost basis, but estimates put it at close to 700 billion won. Chey's side decided not to contest the 700 billion won portion of the 944 billion won total during the re-appeal process, seeking a Supreme Court ruling only on the remaining 244 billion won. In effect, he must secure at least 700 billion won to fund the asset division.
What has drawn attention is the price return swap (PRS) contract he entered into with Korea Investment & Securities as part of the sale.
TRS was the old favorite — now it's PRS?
Chey's stake in SK Inc. is directly tied to his control over the group. Under the arrangement, he transfers shares worth about 400 billion won to Korea Investment & Securities, with the two sides settling the difference between the disposal price and a reference price three years later. If the share price rises, Chey keeps the gain; if it falls, he absorbs the loss. Ownership and voting rights pass to Korea Investment & Securities, but much of the price risk and upside remain with Chey. In economic substance it resembles a loan more than a sale — he secures immediate cash while retaining exposure to any appreciation in SK Inc.'s share price over three years.
Although not disclosed publicly, the structure could also include a call option or right of first refusal allowing Chey to buy back the transferred stake at the contract's expiry. That would let him reclaim the shares at the original sale price even if the stock has risen.
SK Group has previously used derivatives such as total return swaps (TRS) and call options in stake transactions involving SK E&S and SK Siltron, bringing in outside capital while preserving a path to reclaim the shares. The terms of the deal with the strategic investor that acquired 544 billion won worth of shares are therefore another variable — the possibility that Chey has built in an option to repurchase that stake cannot be ruled out at this stage.
Chey holds a 29.3 percent stake in SK Siltron through a TRS arrangement. Selling it could net him hundreds of billions of won — but still not enough to buy back the SK Inc. shares he has just sold.
Solidigm's valuation soars — as SK affiliates pile in
Solidigm is currently a wholly owned subsidiary of NPS. SK Inc., which Chey directly controls, invested about 199.7 billion won in NPS in May. Back-calculating from the investment amount and the stake acquired implies an NPS valuation of roughly $10.5 billion at the time. SK Innovation also invested 89.5 billion won during the first half at a similar valuation. SK Telecom then invested 397.1 billion won in late July, implying a valuation of roughly $41 billion — nearly a tenfold increase in just a few months.
The stakes these affiliates purchased were newly issued shares from NPS. Selling new shares at a discount — if that is indeed what happened — could mean SK hynix, as NPS's largest shareholder, got the short end of the deal. Under Korea's Fair Trade Act, SK Inc. as a holding company, and "uncle" companies SK Innovation and SK Telecom, are barred from investing in SK hynix domestically. Because NPS is a foreign entity, domestic regulations do not apply. The three companies plan to invest a combined total of $1.1 billion in NPS.
Former SK hynix executives investing in Solidigm ahead of the IPO?
The private equity fund said to be investing around 2 trillion won in Solidigm's pre-IPO round is TechBridge Investment. Some domestic media outlets have recently reported that former SK hynix executives — including former President Noh Jong-won, former Executive Vice President Hyun Eun-ah and former Executive Vice President Lee Jae-seo — are involved with TechBridge Investment. These are individuals who played central roles in Solidigm's creation and the acquisition of Intel's NAND business. How executives who only recently left SK hynix managed to raise capital in the trillion-won range is an open question — as is the identity of the limited partners who entrusted them with that money. US private equity funds are generally under no obligation to disclose their individual LP lists to the public, making it difficult to trace the source of the funds.
Bloomberg put Solidigm's expected valuation at $100 billion — a discount of more than 20 percent to SanDisk — while Reuters recently cited a projection of $150 billion, on par with SanDisk. Solidigm signed a deal with CoreWeave on Aug. 7 giving it priority allocation of enterprise SSD production capacity, and on Wednesday announced an extended SSD partnership with Broadcom along with the addition of a contract manufacturing base in Taiwan. Both developments are the kind of news that could push the valuation higher.
For pre-IPO investors, the listing is the clearest opportunity to realize gains. If the pre-IPO and IPO follow in quick succession within a year, early investors benefit most when the valuation rises as sharply as possible in a short period.
Does Solidigm's valuation depend on SK hynix?
That is especially true when the NAND market is booming, as it is now. Solidigm sources NAND wafers from SK hynix to manufacture enterprise SSDs. The lower the wafer price, the lower Solidigm's costs and the higher its profits — but the greater the burden on SK hynix. How SK hynix prices those wafers directly affects Solidigm's valuation. Arm's-length pricing rules and transfer pricing regulations exist for related-party transactions, but applying them to overseas entities is difficult in practice.
Solidigm would not be the first large conglomerate subsidiary to list overseas. Hyundai Motor and LG Electronics have set precedents.
Hyundai Motor held 100 percent of its India unit right up to the IPO and issued no new shares at listing. Instead, it sold a 17.5 percent existing stake through an offer for sale, with proceeds of roughly 3 trillion won flowing back to Hyundai Motor's parent. Hyundai Motor's stake fell from 100 percent to 82.5 percent, but not a single won of the public offering proceeds went into the India unit itself. The stated rationale for the listing was to build a local funding structure — while returning the fruits of years of growth to the parent company's shareholders.
LG Electronics followed a similar approach with its India unit. In an IPO aimed at expanding local investment, LG Electronics sold 15 percent of its 100 percent stake as an existing-share offering. Proceeds of roughly 1.7 trillion won accrued to LG Electronics' parent. LG Group's holding company, LG Corp., did not purchase any shares in LG Electronics' India unit.
"A person cannot draw a square with the left hand while simultaneously drawing a circle with the right." — Han Feizi, "Outer Congeries of Sayings, Lower Left Series"
On Oct. 1, SK hynix said of the Solidigm situation: "Whether to use external or internal capital is a matter that must be judged by comprehensively considering not only the form but also the economic value impact on existing shareholders," adding that it would "review the impact on existing shareholders and the necessary shareholder protection measures, and provide a thorough explanation."
Whether SK can draw a square with one hand and a circle with the other remains to be seen.
kyhong@heraldcorp.com