Rep. Heo Jong-sik calls for abolishing marriage-based exclusion and extending premium support to non-earning spouses
About 3.86 million people with no income are excluded from the national pension system solely because they are married to an earning spouse — even though unmarried people in the same financial situation retain full membership, data showed.
Nine out of 10 of those excluded had previously paid premiums, and about 320,000 had contributed for more than 16 years.
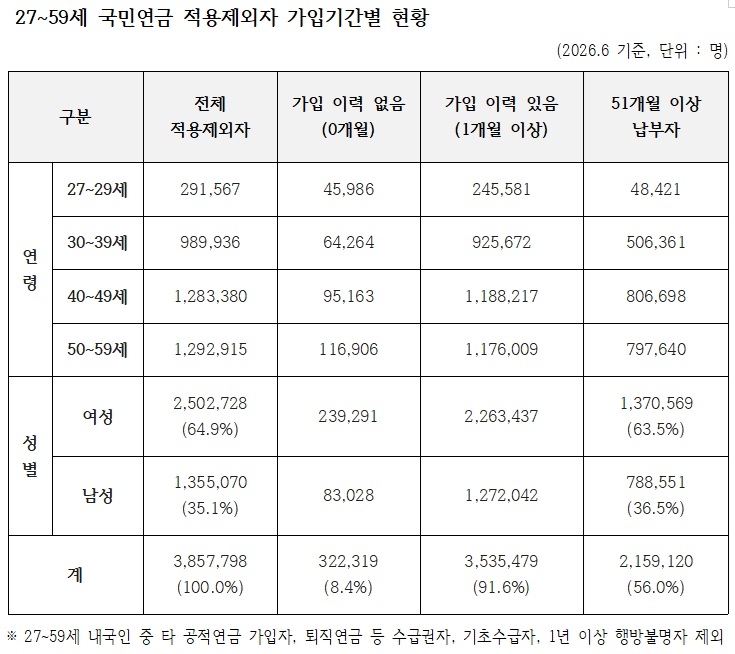
According to data obtained from the National Pension Service by Rep. Heo Jong-sik of the Democratic Party of Korea, a member of the National Assembly's Health and Welfare Committee, the number of people aged 27 to 59 classified as exempt from the national pension as of June 2026 stood at 3,857,798.
Of that total, 91.6 percent — about 3.5355 million — had a contribution history of at least one month, while 322,319 people, or 8.4 percent, had never paid a premium.
By age group, about 1.2834 million were in their 40s and about 1.2929 million were in their 50s. Those in their 40s and 50s — for whom retirement preparation is most urgent — accounted for 66.8 percent of the total, or about 2.5763 million people.
Under the current national pension system, people without earned income are treated differently depending on whether they are married.
Unmarried people with no income are classified as "premium-deferred" subscribers and retain their membership, while married people with no income whose spouses earn are classified as "exempt" and removed from the subscriber rolls. The disparity stems from the household-centered enrollment structure built into the system when it was first introduced.
To rejoin the national pension, an exempt person must apply for voluntary enrollment and pay the full premium out of pocket. Because they are not legally classified as regional subscribers, they are also ineligible for the temporary premium support available to regional subscribers who resume contributions.
The rules governing retroactive premium payments — which allow people to pay premiums for periods they missed — also differ by marital status.
Premium-deferred periods accumulated while single can be paid retroactively regardless of whether the person ever made a first payment, but exempt periods accumulated after marriage can only be paid retroactively for months following an initial contribution.
For example, a person who married at 26 and became a full-time homemaker cannot make retroactive payments for the exempt period. By contrast, someone who married at 37 can pay retroactively for the premium-deferred period from age 27 up to the date of marriage and thereby qualify for a pension. Two people with identical income histories end up with different retirement outcomes simply because of when they married.
"It goes against the spirit of a pension system meant to cover the entire population that people with no income are excluded from the national pension just because they are married," Heo said. "A structure that pushes people away from the public pension system the moment they start a family also runs counter to efforts to address the low birth rate."
Heo called for a comprehensive overhaul, saying the marriage-based exemption should be abolished so that non-earning spouses are managed as premium-deferred regional subscribers, allowed to make retroactive payments regardless of prior contribution history, and made eligible for premium support.
thlee@heraldcorp.com