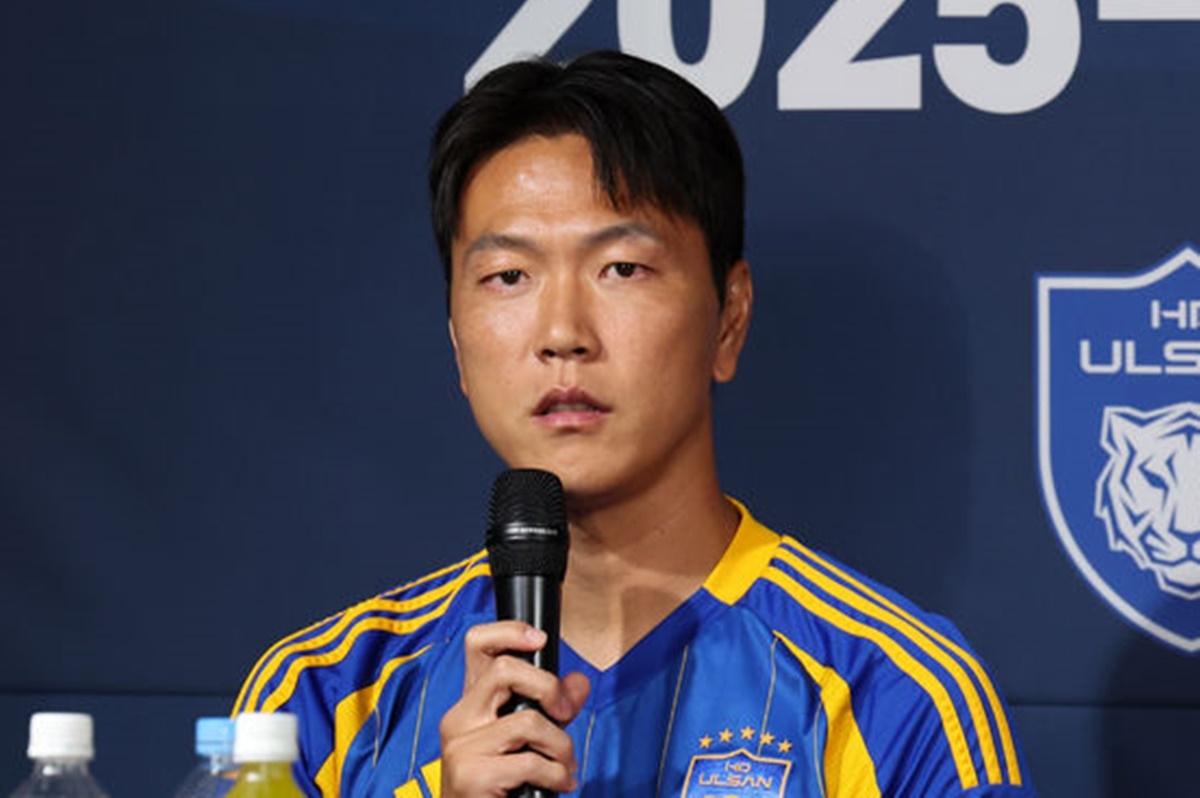
Footballer Kim Young-kwon, 36, of Ulsan HD has lost a Supreme Court challenge against an 800 million won ($593,000) tax assessment, after arguing that the way foreign tax credits were applied to his domestic income tax liability was improper.
The court ruled that foreign tax credits must be calculated separately for each country where income is earned, and that unused credits from one country cannot be carried over and applied against tax owed on income earned in a different country.
According to legal sources Sunday, the Supreme Court's Third Division confirmed on Sept. 23 a lower court ruling against Kim in his lawsuit seeking to cancel an income tax assessment issued by the Ulsan tax office.
Kim played for Chinese professional club Guangzhou Evergrande from June 2012 to December 2018, then for Japanese club Gamba Osaka from January 2019 to December 2021. He has played for K League 1 side Ulsan HD since January 2022.
The central issue in the case was how taxes paid abroad should be credited against his domestic income tax obligations.
Under the Income Tax Act, Korean residents who earn income and pay taxes overseas are entitled to deduct those foreign taxes from their domestic income tax liability up to a set limit, in order to prevent double taxation. Any amount exceeding the deduction limit in a given year may be carried forward to subsequent years.
Kim had been unable to claim a credit for about 600 million won of the taxes he paid in China in 2018, as the amount exceeded the applicable limit. When filing and paying domestic income tax on his earnings in Japan from 2019 to 2021, he applied not only the Japanese taxes but also the 600 million won in uncredited Chinese taxes as a combined deduction.
Tax authorities rejected the carryover of the Chinese tax credit, saying the per-country limit rules had to be applied separately. They consequently imposed an additional 830 million won on top of the 1.07 billion won Kim had already paid in income tax.
The enforcement decree of the Income Tax Act stipulates that when a taxpayer has overseas business operations in two or more countries, the foreign tax credit limit must be calculated on a country-by-country basis.
Kim filed for a tax tribunal review, but after it was dismissed he took the matter to court.
He argued that he should not be considered a Korean resident for the 2019–2021 period, as he had lived in Japan and conducted his social and economic activities there. He also contended that the per-country credit limit rule applied only when a taxpayer had operations in two or more countries within the same tax year, and therefore did not apply to him since his time in China and Japan fell in different periods.
The Supreme Court upheld the lower courts' rejection of both arguments.
The court first determined that Kim qualified as a Korean resident under the Korea-Japan tax treaty for the 2019–2021 period. Although he maintained permanent residences in both countries during that time, the court found that his personal and economic ties were closer to Korea.
Key factors included that Kim remitted most of his Japanese earnings to Korea and spent the money there, that he conducted real estate transactions in Korea and lived with his family in a Seoul apartment, and that he operated a soccer education business and a rental business in Korea, generating domestic income.
On the per-country credit limit rule, the court held that its application could not be restricted to cases where a taxpayer had overseas operations in two or more countries within the same tax year. The rule equally requires a country-by-country calculation when operations span two or more countries across different tax years.
Accordingly, the court ruled that the uncredited portion of taxes paid in China could not be included in the credit limit applicable to income earned in Japan.
bbo@heraldcorp.com