Samsung E&A has been on a relentless upward run, powered by earnings that have blown past market expectations and a robust shareholder-return program. Even as foreign investors have been dumping Kospi heavyweights Samsung Electronics and SK hynix in bulk, they have been snapping up Samsung E&A shares — cementing the stock's reputation as a standout pick in a volatile market.
Samsung E&A surged as much as 9 percent during Friday's session, briefly topping 61,000 won ($46). The rally extended a three-session winning streak: the stock climbed 9.63 percent on Wednesday and then rocketed 17.61 percent on Thursday.
The share price stood at 24,050 won at the end of last year (Dec. 30) and has since soared more than 150 percent. Foreign investors have been aggressive net buyers of Samsung E&A this month, helping drive the broader index higher.
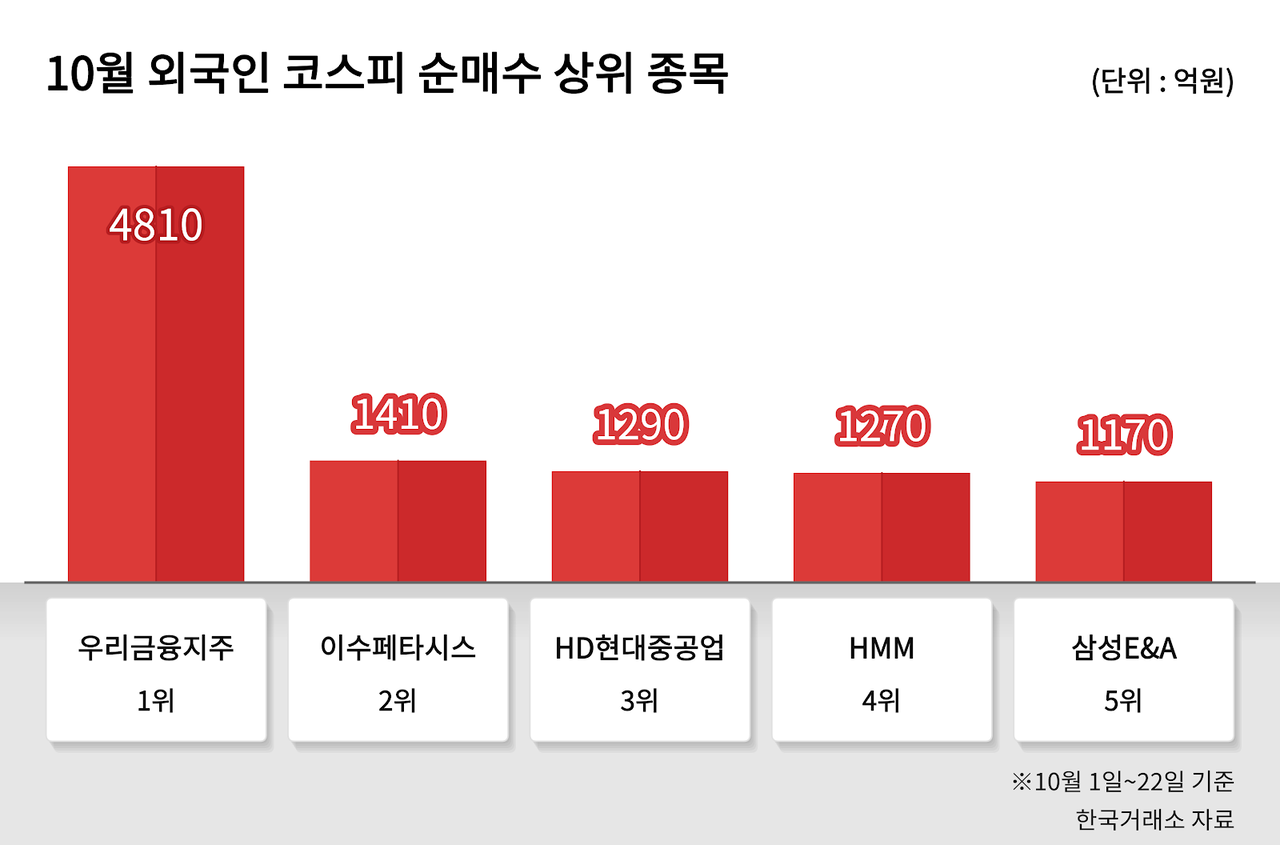
From the start of this month through Thursday, foreign investors ranked Samsung E&A fifth on the Kospi in terms of net purchases, behind Woori Financial, Isupetasys, HD Hyundai Heavy Industries and HMM. Net foreign buying in the stock totaled 117 billion won over the period.
The flow of foreign capital into Samsung E&A reflects a rotation away from semiconductor-related names, whose volatility has risen amid growing skepticism about AI, and toward stocks with clear earnings momentum and shareholder-return catalysts.
During the same period, foreign investors net sold SK hynix and Samsung Electronics more heavily than any other stocks on the exchange, offloading a combined 13.485 trillion won ($10.2 billion) worth of the two names.
Samsung E&A's third-quarter results and shareholder-return announcement, released earlier, overwhelmed market expectations. On a consolidated basis, third-quarter sales rose 45.8 percent year on year to 2.91 trillion won, while operating profit surged 183.6 percent to 500.6 billion won — nearly double the market consensus of around 252 billion won.
The gross profit margin climbed to 21.5 percent, lifted by a provision reversal of about 100 billion won from the final settlement of the Saudi Yanbu power project, along with incentive payments tied to client capital-expenditure savings and settlement gains from projects nearing completion — improvements spread evenly across all business segments.
Strong cash generation gave the company the firepower to announce a buyback and raise its annual guidance, adding further fuel to the share-price rally. Samsung E&A said it would repurchase a total of 780 billion won worth of its own shares. Of that amount, roughly 690 billion won — about 6.4 percent of shares outstanding — will be retired in full after purchase, excluding 90 billion won set aside for employee compensation.
The buyback is a special shareholder-return measure separate from the company's existing policy of returning 15 to 20 percent of controlling-interest net profit.
The company also sharply raised its full-year guidance, lifting its new-order target from 12 trillion won to 19 trillion won and its operating-profit target from 800 billion won to 1.4 trillion won, signaling strong confidence in its earnings trajectory.
Brokerages raised their targets in unison, with analysts calculating more than 30 percent additional upside from current levels. NH Investment & Securities set the highest target price among domestic brokerages at 86,000 won, while Hanwha Investment & Securities, Samsung Securities, Eugene Investment & Securities and KB Securities all raised their targets to the 81,000–84,000 won range.
"As semiconductor factory expansions by Samsung Electronics and others gather pace, order opportunities in petrochemicals and global LNG are coming into focus as clients seek to protect their supply chains from disruptions stemming from the Middle East war," said Lee Eun-sang, an analyst at NH Investment & Securities. "Operating profit should continue growing to around 1.4 trillion won next year, and expectations for expanded shareholder returns on the back of improving earnings — including a new three-year policy to be announced early next year — remain well-founded."
Song Yu-rim, an analyst at Hanwha Investment & Securities, said Samsung E&A's third-quarter operating profit far exceeded the market consensus, adding that affiliate-related and petrochemical sales would ramp up sequentially from next year, making a sustained earnings increase over the following two to three years highly likely. "We are still at the very beginning of an improvement cycle, not anywhere near a peak, and it is rare to find this kind of reliable growth in such an uncertain macro environment," Song said.
Heo Jae-jun, an analyst at Samsung Securities, said design optimization and modularization were structural, not one-off, drivers of profitability improvement. "Next year, earnings from the advanced-industry segment will begin to benefit in earnest from affiliate investment, and the combination of earnings growth and a reduction in equity from share cancellations should push return on equity to 23.4 percent next year," Heo said.
jiyun@heraldcorp.com