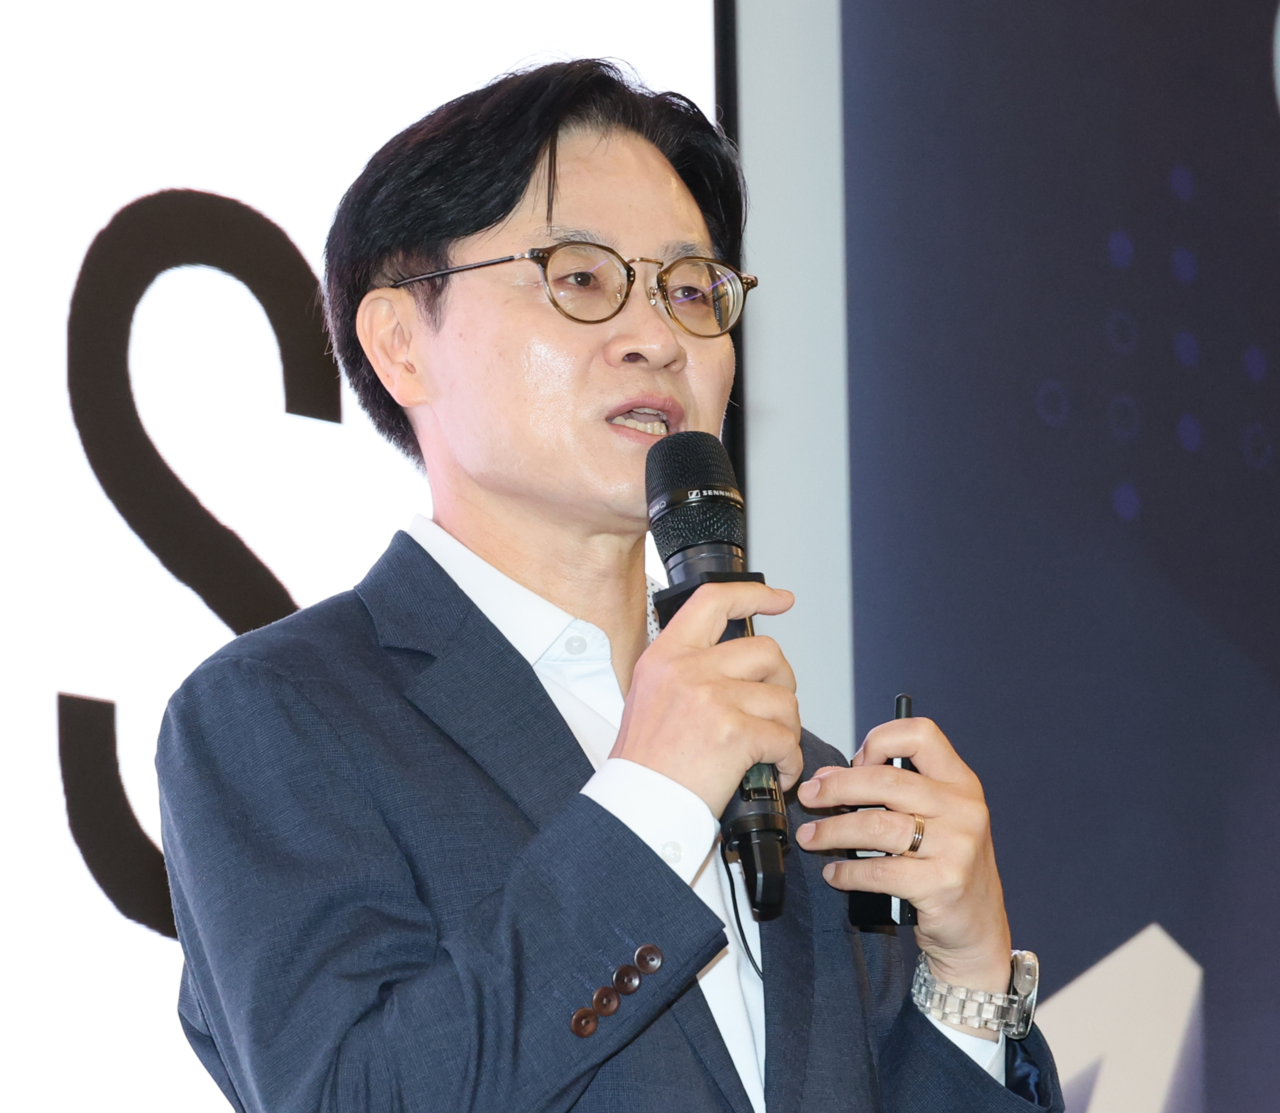
Interview with Kim Jeong-hun, head of FICC division
Capital boost and leverage improvement in one move
Overseas network drives inbound business strategy
Commodity derivatives revenue up 336%, FX up 98%
Hana Securities has become the first domestic brokerage to successfully issue a US dollar-denominated hybrid bond, cementing a distinctive position in the global foreign-currency funding market — an achievement made all the more notable against a backdrop of Middle East geopolitical risk and persistently high interest rates.
Overseas investors credited the result in large part to their high regard for Hana Financial Group's global standing and its demonstrated willingness to support its securities arm. The cohesion between the group and the brokerage — particularly Hana Financial Group's consistent track record of backing paid-in capital increases — was praised as a mark of reliability and long-term potential.
A hybrid bond, or additional tier-1 security, typically carries a maturity of 30 years or more and is classified as equity rather than debt on the balance sheet. Its chief advantage is that it allows an issuer to raise funds much like an ordinary bond while keeping the debt ratio in check and bolstering the capital base. By issuing in foreign currency — US dollars — Hana Securities secured dollar liquidity while laying the groundwork for a more diversified capital structure.
Hana Securities made its debut in the public Korean-issuer dollar bond market in April last year, and in late May this year it successfully priced a $300 million senior dollar bond even as the Middle East crisis was unfolding. The latest hybrid bond issuance rounds out the firm's global funding lineup. At the center of both landmark deals is Kim Jeong-hun, executive vice president and head of the fixed income, currency and commodity (FICC) division.
The hybrid bond led by Kim was a $300 million offering issued on Sept. 30. It carries a 30-year maturity with a call option exercisable after five years — a "30NC5" structure. The deal received a BBB rating from S&P Global Ratings, and the order book drew participation from more than 120 institutions worldwide, with total demand reaching $1.7 billion — roughly six times the offering size. The final coupon was set at 6.50%, equivalent to the five-year US Treasury yield plus 169 basis points, 30 basis points tighter than the initial price guidance.
Behind the word "blockbuster" lay a nerve-shredding game of timing. Kim recalled the tension vividly. "Picking the date was, quite literally, hell," he said.
The window for issuance was just three business days before and three days after the Chuseok holiday. The five-year US Treasury yield had already climbed 50 basis points from where it stood when the team first began evaluating the deal, driven by the Middle East crisis and mounting global fiscal concerns. SoftBank of Japan also had a large bond offering scheduled for the same week. After much deliberation, the team locked in the pricing on Sept. 22 — and watched the rate jump another 20 to 30 basis points almost immediately afterward, prompting a collective sigh of relief across the division.
The primary motivation behind the hybrid bond issuance was capital reinforcement. A "money move" phenomenon — a surge of retail money flowing into the stock market — had pushed brokerages' assets and liabilities higher in tandem, making leverage ratio compliance an industry-wide headache. "When assets and liabilities grow together, it doesn't mean much from a risk standpoint, but because accounting captures both sides, the leverage ratio has become a shared constraint across the industry," Kim said. "As the need for idle capital to support business expansion grew, we began exploring the issuance of foreign-currency capital securities."
Consistent demand signals from overseas investors also served as a catalyst. Since the firm's public debut in the Korean-issuer market last year, a significant number of foreign institutions had asked at every roadshow whether Hana Securities planned to issue hybrid bonds. When the team gauged actual demand, it found that the spread between a five-year senior bond and a five-year callable hybrid was only around 70 to 80 basis points. "We confirmed that we could raise equity-like capital by paying just that much more in yield, and concluded that it was far more advantageous in terms of cost and terms than issuing domestically," Kim said.
The need to build a global investment network to grow inbound business — channeling overseas investors into Korean assets through Hana Securities — was another factor. "To sell attractive Korean assets such as equities, alternative investments and blind funds, the global investor network we built through this issuance was a very important justification," Kim said. The deal thus served a dual purpose: strengthening the capital base while creating a new revenue-generating bridgehead to connect overseas capital with the Korean market.
What overseas investors valued most was Hana Financial Group's global standing and its commitment to supporting the brokerage. Investors took note of the cohesion between the group and its securities unit — particularly Hana Financial Group's consistent history of backing paid-in capital increases. Also persuasive were the firm's near-decade-long leadership in the equity-linked securities market, its ability to manage risk through back-to-back structures, and the growth trajectory of its wealth management division.
The rising profile of Korean-issuer paper in global markets also played a role. The share of Korean issuers in the Asian dollar bond market has grown from around 15 to 20 percent to nearly matching the pan-China issuance share of 30 percent this year. Korean credit spreads have held near historic lows for more than two to three years. "It is clear that Korean paper has gained in global stature," Kim said. "This hybrid bond issuance has also helped broaden the diversity of the Korean-issuer universe."
The hybrid bond issuance lifted Hana Securities' net capital ratio by approximately 280 percentage points and improved its leverage ratio by about 48 percentage points. As of end-September, the net capital ratio stood at 1,726.9 percent and the leverage ratio at 839.3 percent.
"Because hybrid bonds count as equity, they improve both the net capital ratio and the leverage ratio simultaneously, and the reinforced capital base allows the firm to lever up by as much as ten times — making it broadly useful across the entire business," Kim said. Raising $300 million translates theoretically into roughly 4 trillion won ($3.02 billion) in leverage capacity. Hana Securities plans to deploy around 2.5 trillion won of that.
The firm intends to allocate the additional capital strategically across its sales and trading and investment banking divisions, redeploy it in portfolio restructuring and growth businesses, and put it to work in productive finance and large-scale projects.
Going forward, Hana Securities plans to maintain a flexible foreign-currency funding framework that adapts to market conditions and the broader financial environment. Its outstanding overseas issuance currently stands at around $2 billion. "When we did our first public offering last year, we set a goal of issuing $300 million every year for three years to establish ourselves as a trusted issuer," Kim said, signaling the firm's continued commitment to global capital markets.
The FICC division's own competitive strength is also showing up in the numbers. At the end of last year, Hana Securities elevated FICC from a department to a full division and consolidated three separate units — products, asset management and institutional financial products — under a single umbrella. "I expected that combining the various functions scattered across the institutional and sales divisions with FICC would maximize synergies," Kim said. Since the reorganization, commodity derivatives revenue has surged 336 percent year-on-year and foreign exchange revenue has jumped 98 percent.
The division plans to actively develop structured Euro Medium Term Notes — foreign-currency bonds combined with derivative structures — as the domestic equity-linked securities market has contracted under accounting and regulatory constraints, prompting the firm to seek new demand overseas. Beyond supplying overseas alternative investment products to domestic clients, Hana Securities will also formalize a two-way business model that connects foreign investors with domestic blind funds and asset managers. "The overseas investor network we expanded through this issuance will be the foundation for that inbound business," Kim said.
jiyun@heraldcorp.com