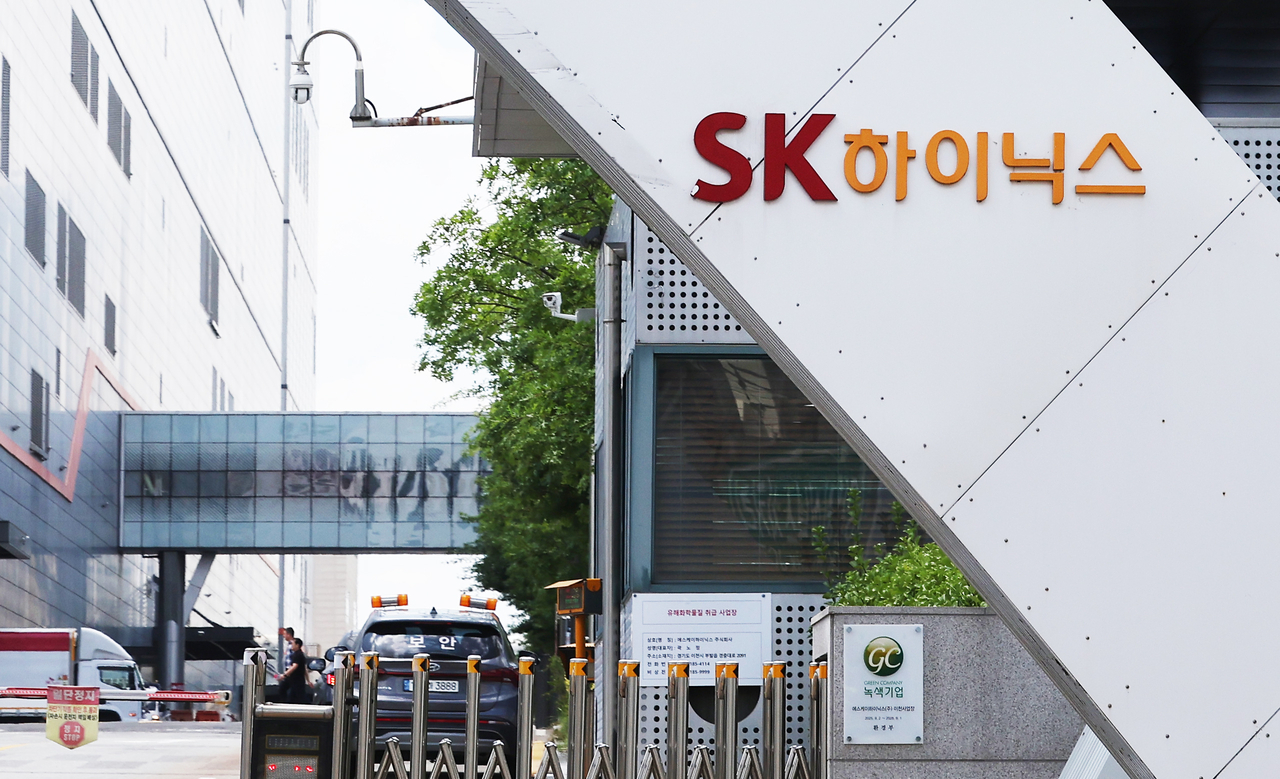
Overseas institutional investors are piling into SK hynix's American depositary receipts ahead of the company's Nasdaq listing on Friday. Because the ADRs are issued on the basis of the domestic common shares, the converted price of the underlying stock serves as an important reference point — though the final issue price will be set based on overseas institutional demand and market conditions. Some analysts say the ADRs could trade at a premium to the Korean-listed shares after the debut, particularly if conversion restrictions between the two securities come into play alongside improved access for US investors.
Bloomberg reported Monday, citing sources, that the SK hynix ADR was oversubscribed "multiple times" during the bookbuilding process ahead of final pricing. The final issue price is set to be confirmed Wednesday afternoon New York time.
Demand from large, long-term institutional investors and technology-focused funds was strong from the outset of the bookbuilding process, according to industry sources. About 1,000 institutional investors attended a roadshow held Monday. Bloomberg reported that three major investment firms — Situational Awareness Partners, Baillie Gifford and Coatue Management — have indicated interest in buying up to $7 billion worth of shares through the bookbuilding process.
A key driver of the strong demand is the difficulty US investors face in gaining direct exposure to Korean memory chip stocks. Nori Chiu, director of investments at White Oak Capital, told Bloomberg that Korean equities — especially memory chip names — "remain a relatively scarce and hard-to-access asset for US investors," adding that "this scarcity value will underpin demand."
UBS Group also flagged the potential for the SK hynix ADR to trade at a premium. Bloomberg reported Tuesday that the UBS sales and trading desk recommended in a client note that investors buy the SK hynix ADR and sell the Korean-listed shares. The bank reasoned that the newly issued ADRs would be more efficient and cost-effective to hold and manage than the domestic common shares, making them more attractive to hedge funds and other institutional investors.
"Buying the depositary receipts from day one and shorting the domestic line is an obvious trade," UBS said in the client note, adding that "the dollar risk exposure is very limited, making it highly scalable, so the probability of it trading at a discount is very low." The strategy amounts to a relative-value trade for institutional investors seeking to profit from the price gap between the ADR and the domestic common shares.
UBS also cited as a premium factor the fact that global portfolio managers who do not include Korean-listed stocks in their investment universe would now be able to gain exposure to SK hynix through the ADR. "There have been some reports of US brokerages providing foreign retail investors with access to Korean equities, but this is a recent development," UBS said, adding that "global retail investor ownership of SK hynix remains low, and the ADR will improve accessibility."
Bloomberg noted that investors are closely watching whether conversion between the Korean shares and the ADR will be possible. According to SEC filings, ADR holders can cancel their receipts and receive the equivalent Korean-listed shares, but converting those shares back into ADRs at a later date may require approval from Korean authorities and could face other restrictions.
If conversion from domestic shares to ADRs is limited while US investor demand remains strong, the supply of ADRs in the American market may struggle to keep pace with demand. "Investors will pay attention to the headroom in the foreign ownership limit that would be available for future conversion from the Korean domestic listing to the US secondary ADR listing," UBS said, warning that "without that limit flexibility, the lack of accessibility makes it highly likely that the US line will trade at a clear and sustained premium."
A premium over the home-market listing has been observed in other similarly structured overseas ADRs. TSMC's ADR, listed on the New York Stock Exchange, traded at an average premium of about 16 percent over its Taiwan-listed shares this month.
However, heightened volatility in semiconductor stocks around the listing is a wildcard. Bloomberg reported that SK hynix shares have fallen 17 percent this month and are now about 9 percent below the ADR reference price of 242,500 won ($159) stated in the SEC filing. As a result, some observers say the ADR listing's implied market capitalization — estimated at $29 billion at the end of last month — could fall to around $28 billion.
The recent volatility is tied to concerns about slowing demand for high-bandwidth memory chips. News on Wednesday that Meta Platforms would launch a cloud business renting out surplus AI computing resources to outside customers fueled fears that big tech's AI infrastructure investment may be entering a short-term oversupply phase. That raised doubts about whether HBM demand growth could be sustained, and the Philadelphia Semiconductor Index fell more than 10 percent over two days.
A $13 billion two-times leveraged exchange-traded fund linked to SK hynix's share price has also been identified as a source of added volatility, as the ETF's mechanical rebalancing to maintain its daily target multiple can amplify price swings. Despite the strong bookbuilding results, analysts say the ADR's premium relative to the domestic share price, the feasibility of conversion between the two securities, and broader semiconductor volatility will be the key variables shaping the stock's early trading performance after the listing.
kacew@heraldcorp.com