Samil PwC holds 2026 tax reform briefing
Over 600 corporate tax and finance officials attend
Briefing covers corporate tax, inheritance tax changes and practical strategies
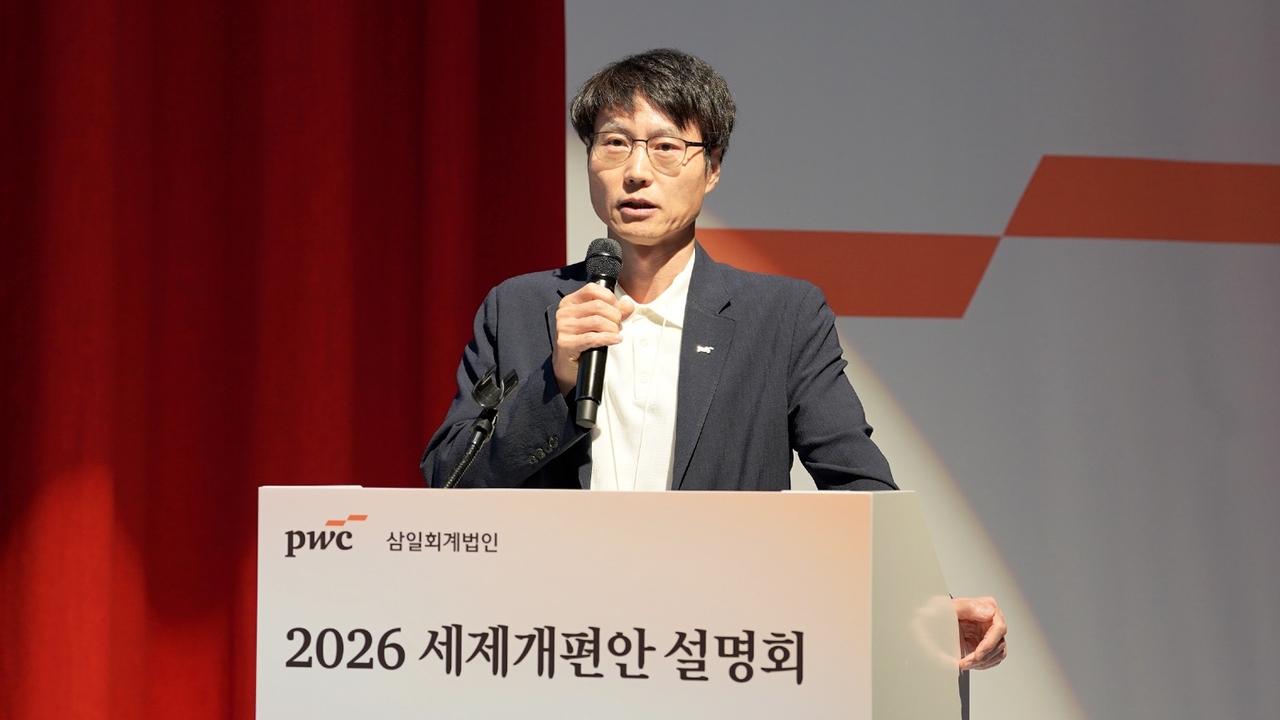
With the government unveiling a sweeping tax reform package covering the Restriction of Special Taxation Act, the Corporate Tax Act, and the Inheritance and Gift Tax Act, a forum was held to help companies build practical response strategies. Experts at the event warned that the breadth and complexity of the proposed changes make it essential for businesses to closely analyze both the rationale behind the revisions and their potential impact on corporate management.
Samil PwC held the "2026 Tax Reform Briefing" on Monday at Amorehall in the Amorepacific headquarters in Yongsan-gu, Seoul, in a hybrid online and in-person format. More than 600 corporate tax and finance officials attended, with specialists from each field taking the stage to outline the key provisions of the revised tax laws and offer guidance on how companies should respond.
Jeong Min-su, head of Samil PwC's tax advisory division, said in his opening remarks that the recently announced reform package centers on three priorities: reversing the decline in potential growth, supporting livelihoods and regional economies, and rationalizing the tax system through fairer assessment. "Since specific details may change during National Assembly deliberations and the drafting of enforcement decrees, companies must keep a close watch on the latest developments before making major decisions," he said.
Lee Jeon-o, a Samil PwC adviser, said in his welcoming address that the reform package includes a wide range of measures — among them a new domestic production tax credit, expanded support for small and medium-sized enterprises and venture companies, and revisions to the family business inheritance deduction. "We need to look beyond what has changed to understand why it changed and where tax policy is headed," he said.
The briefing was structured into two parts comprising seven sessions in total.
Shin Yun-seop, a partner who led the first session, covered changes to the Corporate Tax Act and the Framework Act on National Taxes. He explained revisions to the taxation of deemed dividends and disposal gains and losses linked to the mandatory cancellation of treasury shares under the amended Commercial Act, and examined issues related to overseas restructuring, including tax deferral on foreign subsidiary spin-offs and stock dividends.
Partner Kim Un-gyu then analyzed proposed amendments to the Inheritance and Gift Tax Act, noting that eligibility requirements for the family business inheritance deduction and succession special provisions would be significantly tightened. "Leaving the assessment of whether a business owner possesses specialized technical skills and management know-how to a review committee could increase practical uncertainty," Kim said. He added that listed shares suspected of artificial price suppression would be subject to stricter valuation methods, potentially triggering simultaneous gift tax and corporate tax burdens as well as breach-of-fiduciary-duty concerns, and called for regulatory improvements.
In the session on the Income Tax Act and the Comprehensive Real Estate Tax Act, partner Park Ju-hee said the real estate tax regime was shifting away from the number of homes owned toward the value of properties and whether the owner actually lives in them. She flagged higher tax burdens ahead for owners of high-value homes and for non-resident single-home or multi-home owners.
Opening the second part, partner Park Jong-u covered the Restriction of Special Taxation Act and the Value-Added Tax Act, highlighting the introduction of a new domestic production tax credit targeting strategic items — including semiconductors, secondary batteries, AI and robot components — and the expansion of research and development and investment support outside the greater Seoul metropolitan area.
Lee Dong-yeol, the partner responsible for international taxation, noted that the low-tax threshold for controlled foreign corporations had been lowered to the global minimum tax level of 15 percent. "Because multiple exemption methods will coexist from 2027, each company must analyze which approach works in its favor," he advised.
Kim Su-jeong, who presented on local tax law, analyzed a broader trend toward reducing long-term tax benefits — including tighter requirements for the separate aggregation of corporate-owned land — while also introducing temporary, region-specific tax relief for redevelopment projects and venture facilities.
In the final session, Lee Yeong-mo, a managing partner at PwC Customs & Trade, addressed changes to customs law, citing the expiration of tariff exemptions on goods used for industrial technology research and development and the tightening of penalties for quota tariff violations. He urged companies to overhaul their internal compliance frameworks.
Meanwhile, Samil PwC — which closes its books in June — posted sales of 1.11 trillion won ($825 million) and operating profit of 25.4 billion won for fiscal year 2025, covering July 2024 through June 2025.
an@heraldcorp.com