Samil PwC 'Global Data Centre Outlook' report
"AI data centers require equipment replacement every 4–6 years;
must be valued as 'complex assets,' not simple real estate"
The competitive dynamics of the global AI infrastructure market are rapidly shifting away from securing data center buildings and sites toward ensuring stable power supply and critical infrastructure supply chains. Power availability, semiconductor supply chains and data sovereignty have emerged as the key variables that will determine the direction of future investment.
Samil PwC announced Friday that it has published a report titled "Global Data Centre Outlook 2026–2050," which covers capital expenditure forecasts for data centers across 46 countries and regions and five global zones, along with implications for the South Korean market.
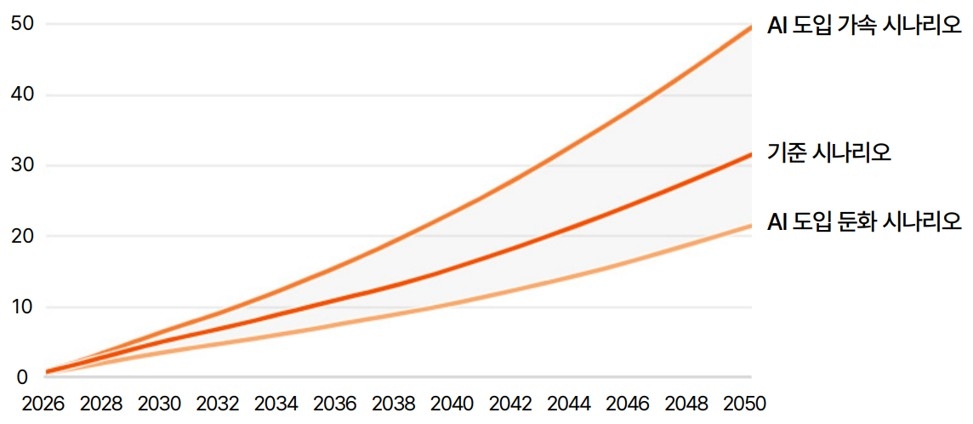
According to the report, cumulative global data center capital investment from this year through 2050 is projected to reach $31.6 trillion under a baseline scenario. If AI adoption accelerates, the figure could expand to around $50 trillion. Annual investment is also forecast to climb steeply, from roughly $800 billion this year to $1.8 trillion by 2050.
By region, the Americas are expected to attract approximately $16.5 trillion — about 48 percent of global investment — through 2050, with the United States alone accounting for $15.1 trillion of that total. The Asia-Pacific region, by contrast, is projected to see cumulative investment of $8.2 trillion, constrained by power supply limitations and regulatory complexity, with China and India expected to drive demand.
The report argues that the current AI infrastructure investment cycle is structurally different from past infrastructure booms in railways, power grids and the internet. While investment in traditional infrastructure typically declines after construction, AI data centers require recurring replacement of major ICT equipment — including GPUs and servers — every four to six years, making long-term, repeated investment unavoidable.
As a result, the share of ICT equipment within total data center investment is forecast to rise from 70 percent in 2026 to 93 percent by 2050. The report finds that the industry's value will shift away from buildings and land toward repeatedly replaced equipment such as GPUs, memory chips, power devices and cooling systems. It concludes that data centers should henceforth be evaluated as "complex assets" combining power infrastructure with advanced ICT equipment.
The report identified five key investment decision factors: power; latency and connectivity; a secure and trusted hosting environment; GPU access and the AI ecosystem; and policy predictability and community acceptance. Of these, securing power was singled out as the single most decisive factor determining when ground-breaking and operation can begin.
South Korea was assessed as globally competitive across a range of critical equipment categories, including HBM and memory chips, power devices, uninterruptible power supplies, ESS, liquid cooling, data center infrastructure management systems and security solutions.
The report particularly said South Korea's opportunity lies not so much in the scale of data center construction as in its position within the global AI infrastructure supply chain. Because the core equipment inside data centers must be continuously installed and replaced regardless of where those facilities are located, the report called for a strategy that simultaneously expands domestic AI computing infrastructure and actively pursues business opportunities in global supply chain markets.
The report also suggested that South Korea's domestic data center market could segment along AI workload lines — AI inference in the Greater Seoul area, AI training outside the metropolitan area, and industrial AI at manufacturing hubs. However, it cautioned that grid interconnection and substation capacity expansion have not kept pace with rising data center demand, meaning the actual availability of power and the timing of operations will likely determine whether projects succeed or fail.
Seo Yong-tae, leader of Samil PwC's AI data center dedicated team, said the core of the AI infrastructure investment race lies in "the ability to secure stable power quickly and convert it into operational computing infrastructure." He added that because South Korea holds competitive strengths across the AI infrastructure supply chain, "execution — connecting domestic AI computing infrastructure expansion and entry into global supply chain markets to tangible industrial growth — is what matters most."
Meanwhile, Samil PwC, whose fiscal year ends in June, posted sales of 1.11 trillion won ($811 million) and operating profit of 25.4 billion won for fiscal year 2025, covering July 2024 through June 2025.
an@heraldcorp.com