BOJ raises benchmark rate to 1.25%, highest since 1995, but yen retreats to 157 per dollar; analysts say tightening signal fell short of market expectations
US-Japan rate gap persists amid Fed hike signals; Takaichi's expansionary fiscal stance and surging oil prices add further pressure on the yen
The Bank of Japan raised its benchmark interest rate for the first time in three months on Friday, but the move failed to arrest the yen's persistent weakness. Analysts say the currency's stubborn slide reflects a market judgment that the pace of tightening fell short of what had been anticipated.
The yen had briefly strengthened to around 152 per dollar in the run-up to the decision, buoyed by rate-hike expectations, but reversed course sharply after the announcement, touching 157.145 per dollar — its weakest level since Sept. 3. The yen also fell 0.8 percent against the euro, to 180.32 yen per euro, even as the BOJ lifted rates to their highest level in more than three decades.
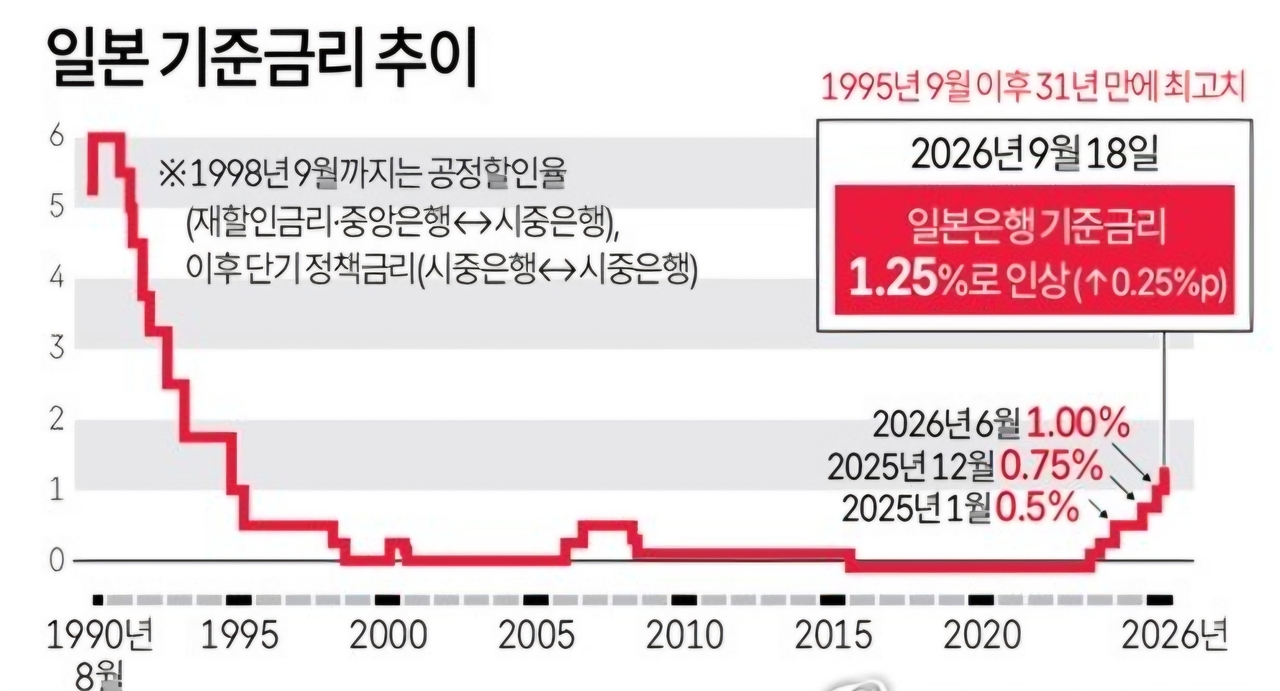
The BOJ's policy board, meeting over two days beginning Thursday, voted to raise its short-term policy rate by 25 basis points, from around 1.0 percent to around 1.25 percent — the highest level since 1995.
In theory, a rate increase supports a currency by raising the yield on assets denominated in it, attracting capital inflows. But the yen's reaction underscored how markets weigh not just the direction of policy but how much of a move has already been priced in and how the gap with other major economies is likely to evolve.
Analysts say the BOJ's failure to meet market expectations was the key factor limiting any yen-strengthening effect from the hike. Financial markets, they note, are more sensitive to whether a decision was already priced in and how the rate differential with other major economies shifts than to the policy direction itself.
The decision was not unanimous. Seven of the BOJ's nine policy board members voted in favor, while two — Asada Doichiro and Sato Ayano — dissented.
Ray Attrill, head of foreign exchange strategy at National Australia Bank, said "the decision clearly fell short of market expectations," adding that "what was particularly surprising was that even the rate hike itself failed to secure a unanimous vote, which significantly deepened market skepticism."
BOJ Governor Kazuo Ueda also disappointed markets by declining to set a fixed schedule for future rate increases. At a post-decision news conference, Ueda said the central bank would continue raising its policy rate to sustainably achieve its 2 percent inflation target, and suggested it could move in consecutive meetings or take a larger "big step" of 50 basis points depending on price conditions.
When asked about the possibility of back-to-back hikes or a 50-basis-point increase in a single move, Ueda said he could not rule out any particular approach depending on how inflation develops — a remark interpreted as stopping well short of a commitment to aggressive near-term tightening. The underlying logic, analysts noted, is that gradual, well-timed increases reduce the risk of being forced into sharp hikes later.
FX Street, a foreign exchange media outlet, said "investors had been buying yen ahead of the September meeting in anticipation that the BOJ would tighten at a faster pace," but noted that "once the expected hike actually materialized without a strong signal of further moves to come, profit-taking selling emerged and pushed the yen lower."
Chris Weston, head of research at Pepperstone Group, said markets would be watching to see whether the possibility of further monetary policy normalization remained on the table, and whether the BOJ felt any urgency to press ahead with additional rate increases.
The still-wide gap between US and Japanese interest rates is adding to the yen's burden. The Federal Reserve raised its federal funds rate target range by 25 basis points to 3.75–4.00 percent on Wednesday (local time), its first increase in three years.
While a BOJ rate hike would normally narrow the US-Japan rate differential and support the yen, the Fed's signal of further increases has spread expectations that the gap will not close quickly, limiting the yen's upside.
Japan's expansionary fiscal policy is also seen as offsetting the BOJ's tightening efforts. Prime Minister Sanae Takaichi is pursuing $2 trillion in public-private investment while maintaining a stance of tax cuts and increased government spending. Reuters reported that while such policies may support economic growth, they raise concerns about fiscal sustainability and add to pressure on the yen and import prices.
Elevated oil prices are piling on as an additional headwind for the yen.
International crude prices above $100 per barrel, driven by Middle East conflict, are compounding the yen's weakness. Japan's heavy dependence on energy imports means rising oil prices swell the country's import bill and strain the trade balance. Growing demand for dollars to pay for crude also weighs on the yen, and when combined with a weaker currency, the yen-denominated cost of energy and other imports rises further — creating an inflationary feedback loop.
FX Street concluded that the yen's latest decline was "not because the BOJ's rate hike was meaningless, but because it failed to convince markets that monetary policy normalization would proceed as quickly as they had hoped."
yckim6452@heraldcorp.com