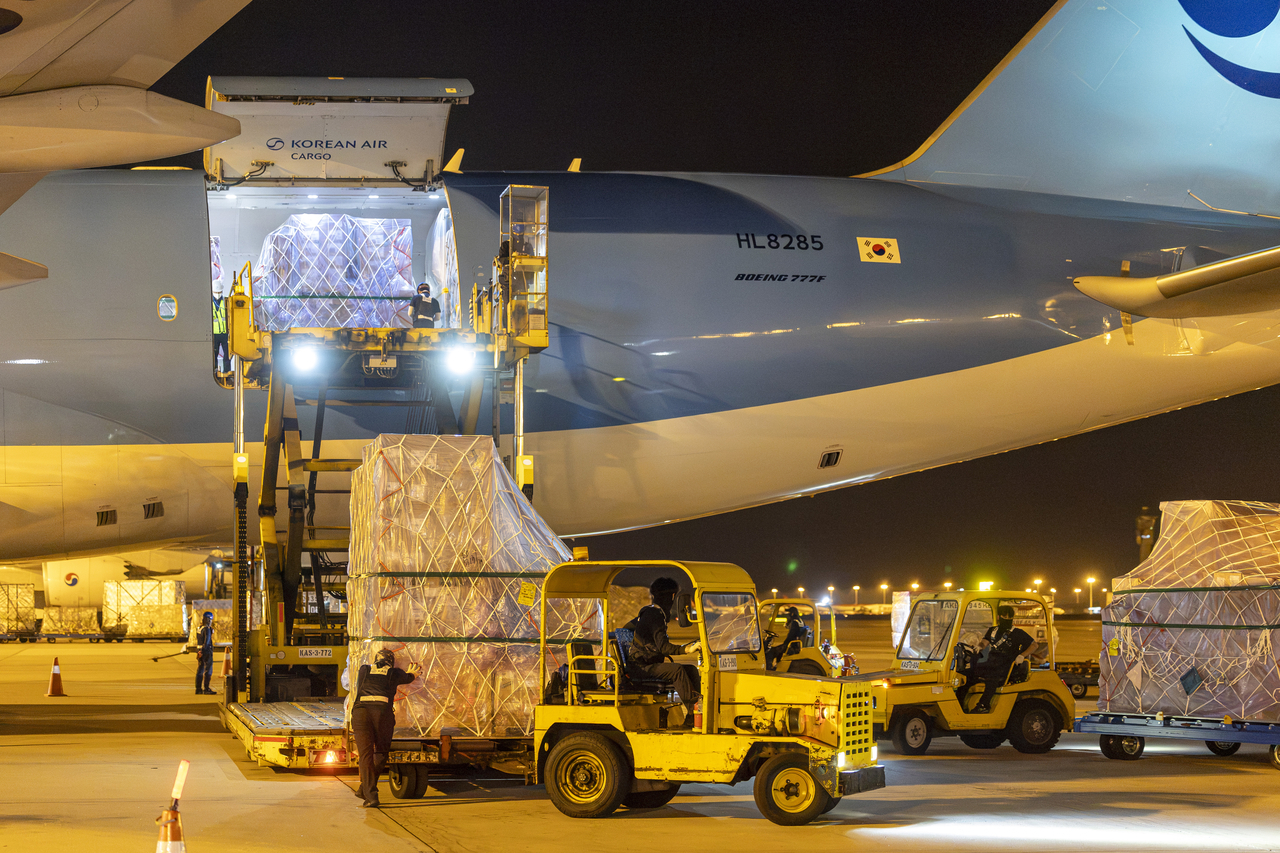
Korean Air is demonstrating a strong ability to defend its profits despite a high exchange rate and elevated fuel prices — two of the biggest headwinds facing the aviation industry.
Airlines typically suffer when the won weakens against the dollar, as jet fuel and aircraft lease payments denominated in dollars become more expensive while demand from Korean travelers heading abroad falls. Fuel costs alone account for roughly 30 percent of an airline's operating expenses, meaning that a combination of a weak won and high oil prices can cause cost burdens to snowball rapidly.
Recently, however, those risks have been offset by two powerful tailwinds: a surge in foreign tourists visiting Korea on the back of the "K-culture" wave, and booming demand to ship AI semiconductors for global technology giants.
According to estimates from domestic brokerages — Sangsangin, iM, Hana Securities and KB Securities — Korean Air's standalone operating profit for the third quarter is expected to reach between 446 billion and 517 billion won ($380 million), an increase of 18 to 37 percent from the same period a year earlier.
That resilience comes despite jet fuel prices surging to around $159 per barrel on average in the second quarter and the won-dollar exchange rate averaging 1,502 won for the quarter. Analysts say the airline's ability to hold up under those conditions reflects structural changes in both its passenger and cargo businesses.
In the past, a rising won-dollar rate would typically lead Korean Air to discount tickets for foreign travelers or transit passengers to fill seats left empty by fewer outbound Koreans, dragging down average yields. The recent trend has been the opposite. Soaring interest in Korea — fueled by the global popularity of K-pop, K-food and K-beauty — has sharply raised the country's appeal as a destination, particularly among travelers from developed nations.
According to the Korea Tourism Organization, the share of Americans who prefer Korea as a travel destination jumped from 22.1 percent in 2022 to 32.4 percent in 2025, and the average daily spending by foreign visitors to Korea more than tripled over the past decade.
That shift means the airline no longer needs to discount internationally issued tickets to attract foreign passengers. Korean Air's international passenger yield for the third quarter is forecast to rise roughly 17 to 18 percent year-on-year, reaching around 142 to 143 won per kilometer. Despite the fare increases, the load factor is expected to remain at a record-high range of 85 to 87 percent.
"As demand from foreign visitors to Korea grows, the discount pressure on internationally issued tickets is easing," said Kang Sung-jin, a researcher at KB Securities. "Passenger fares have remained solid even in a high-exchange-rate environment, and Korean Air's resilience to currency moves has strengthened considerably."
On the cargo side, the global AI infrastructure investment boom has emerged as a decisive new driver of earnings.
According to the International Air Transport Association, about 56 percent of AI servers, 68 percent of data storage devices and nearly 100 percent of memory chips are transported by air.
These shipments are highly sensitive to shock, temperature and humidity, and data center construction schedules leave no room for delay — making it difficult to switch to sea freight even when air cargo rates spike.
The value per kilogram of AI-related cargo is 15.3 times that of other freight, analysts note, which means customers have little reason to push back against rising air cargo rates.
Supply constraints are compounding the pricing power. Delivery delays from aircraft manufacturers Boeing and Airbus have slowed the introduction of new freighters, prolonging a global shortage of air cargo capacity.
With cargo volumes surging and available aircraft in short supply, pricing power has shifted firmly to the airlines. Korean Air's air cargo yield for the third quarter is estimated to have jumped 25 to 39 percent from a year earlier.
"The fourth quarter is the peak season for air cargo, so for now this is a market where air freight carriers can hold the upper hand," said An Do-hyeon, a researcher at Hana Securities.
With both passenger and cargo businesses firing on all cylinders, a broader revaluation of Korean Air's corporate worth is expected to gain further momentum. The integration costs tied to its subsidiary Asiana Airlines — which had weighed on earnings — are now in effect wrapping up, and the completion of the merger in December is expected to unlock meaningful synergies in routes and fares.
Brokerages expect that once Asiana Airlines' reservation and fare systems are unified with those of Korean Air — a process expected to be complete next year — the combined carrier will see an additional annual operating profit improvement of at least 300 billion to 400 billion won.
Major securities firms project that the merged Korean Air's consolidated operating profit next year will range from a minimum of 2.1 trillion won to as much as 2.74 trillion won.
jiyun@heraldcorp.com