First macro-fiscal-financial meeting since deputy PM took office
Policy coordination strengthened amid Bank of Korea rate hike
Emergency buyback planned if government bond yields spike
South Korea's fiscal, monetary and financial authorities have agreed to channel an expected 63.2 trillion won ($46.5 billion) in surplus tax revenue this year into three core social policy areas — housing, employment and financial support for low-income households — as a catalyst for easing economic polarization.
The authorities also agreed to implement market stabilization measures, including emergency buybacks of government bonds if yields rise excessively, and to reduce the volume of new bond issuance by tapping part of the surplus revenue.
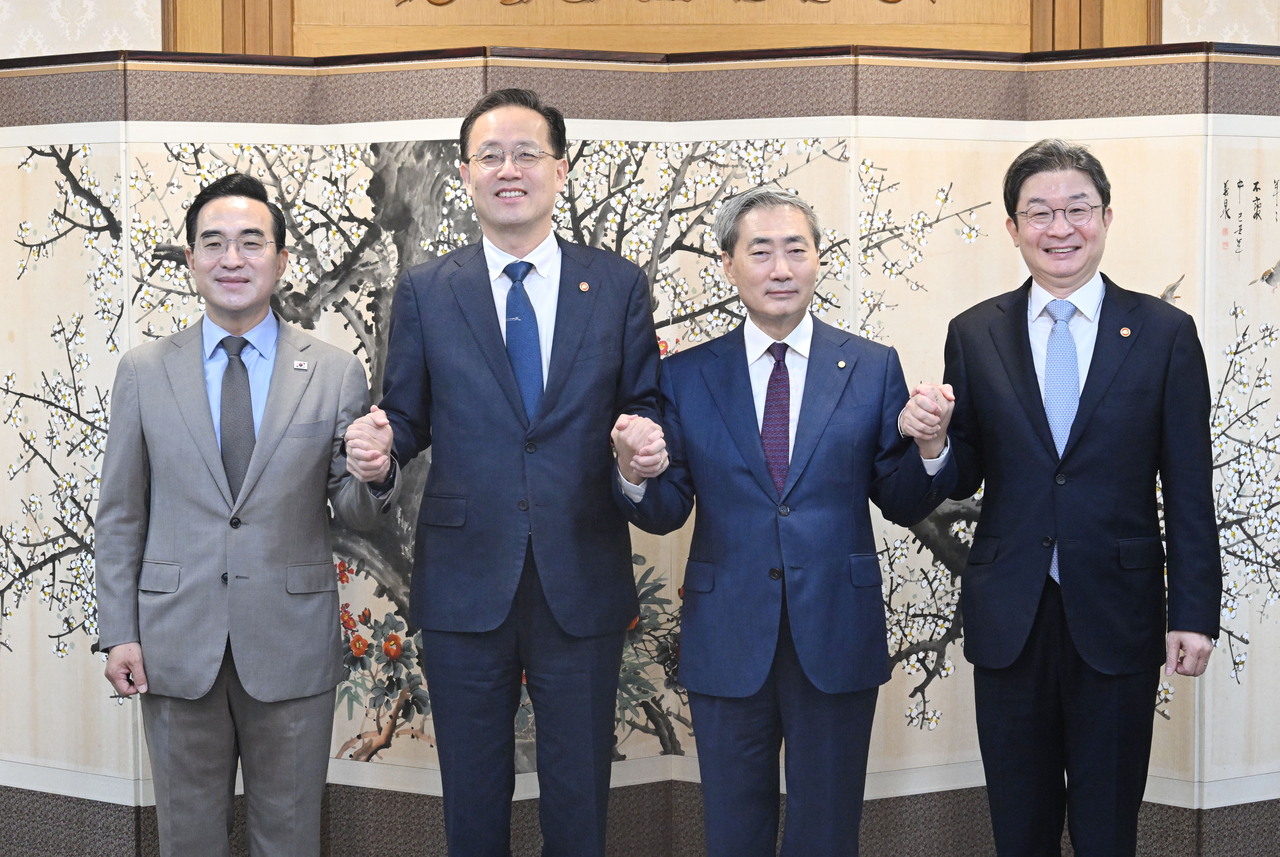
Deputy Prime Minister and Minister of Economy and Finance Lee Hyeong-il convened an expanded macro-fiscal-financial consultative meeting Wednesday morning at Government Complex Seoul, with Minister of Planning and Budget Park Hong-keun, FSC Chairman Lee Eok-won and Bank of Korea Governor Shin Hyun-song in attendance.
The meeting was the first of its kind since Lee took office as deputy prime minister. It was called to assess macroeconomic and financial market conditions and discuss the policy response outlook, ahead of the National Assembly's review of next year's budget and following the Bank of Korea's recent benchmark interest rate hike.
Participants exchanged views on how to deploy the surplus tax revenue, based on a revised tax revenue estimate released Wednesday. Tax receipts this year are projected to exceed the most recent supplementary budget figure by 63.2 trillion won, driven by an accelerating economic recovery fueled in part by strong semiconductor performance.
The participants agreed that the surplus should be deployed strategically given current economic conditions. They particularly emphasized the need to direct the funds toward the three core social policy areas most closely tied to people's daily lives — housing, employment and financial support for low-income households — so that the rapid economic recovery translates into greater stability for ordinary citizens and serves as a catalyst for reducing polarization.
The meeting also addressed the continued rise in bond yields. Participants assessed that domestic bond yields have kept climbing as global interest rates rise — driven by higher oil prices and a pivot toward monetary tightening by major economies — compounding domestic factors.
In response, the authorities agreed to closely monitor government bond market conditions and, if yields rise excessively, to implement necessary stabilization measures including emergency buybacks and a reduction in bond issuance volumes using part of the surplus tax revenue.
Coordination between fiscal and monetary policy was also underscored. Participants said that using fiscal policy to support vulnerable groups and nurture future growth engines could allow fiscal and monetary policy to operate in a mutually complementary manner. They also expressed hope that such an approach would contribute over the medium to long term to raising the potential growth rate and easing inflationary pressures.
However, the participants noted that while growth momentum is broadening on the back of strong economic indicators including exports and investment, significant domestic and external uncertainties remain. They cited rising interest rates in major economies and ongoing geopolitical risks, along with persistent burdens on household livelihoods at home and structural challenges such as deepening polarization that still need to be addressed.
In addition, the fiscal, monetary and financial authorities agreed to strengthen cooperation by maintaining regular communication on macroeconomic and fiscal and financial issues, ensuring that each policy area operates in a coordinated and harmonious manner going forward.
y2k@heraldcorp.com