Cost of hedging against rate spikes on the rise
AI-driven corporate bond issuance adding pressure on Treasurys
Higher mortgage rates spurring increased Treasury selling
Term premium on long-dated bonds also weighing on market
US Treasury yields have soared to their highest levels in more than two decades, heightening tensions in the bond market and fueling fears that rising rates could trigger a self-reinforcing cycle of further selling.
Reuters on Sunday (local time) identified four risk factors that could set off additional selling in the US bond market: growing volatility in the interest rate options market, a surge in corporate bond issuance tied to AI infrastructure investment, an increase in hedging activity linked to mortgage-backed assets, and a steepening yield curve on long-dated Treasurys.
Since the outbreak of the Iran war last February, the yield on the 10-year US Treasury note has climbed roughly 135 basis points to 5.23 percent. The 30-year yield has risen about 110 basis points from its March low to reach 5.614 percent. Both are at their highest levels in more than two decades.
Investors are watching closely whether the recent wave of Treasury selling has entered a phase in which selling begets more selling, as key technical indicators suggest yields could spike further. The concern is that selling driven by a desire to avoid losses from falling bond prices could push yields even higher, amplifying market stress in a vicious cycle.
"Market participants are recalibrating their existing expectations," said Dustin Reid, a bond strategist at Mackenzie Investments.
Hedging costs climb as AI bond issuance adds to market strain
Demand for protection against sudden rate spikes in the interest rate options market is growing rapidly. Investors are turning to options to guard against losses from rising rates without having to sell Treasurys outright.
Short-term hedging demand against sharp moves in the 10-year US swap rate has expanded, pushing the cost of options protecting against a 200-basis-point rise in rates over the next three months to 132 basis points as of Monday, Reuters said. That is the highest level since March 2023, when the collapse of Silicon Valley Bank set off a broader US banking crisis. The swap rate refers to the rate an investor pays to receive a fixed rate in place of a floating one.
Implied volatility, which reflects uncertainty about future rate moves, has also widened. The implied volatility on one-month options based on the 10-year swap rate rose to 21.4 basis points, the highest since late March.
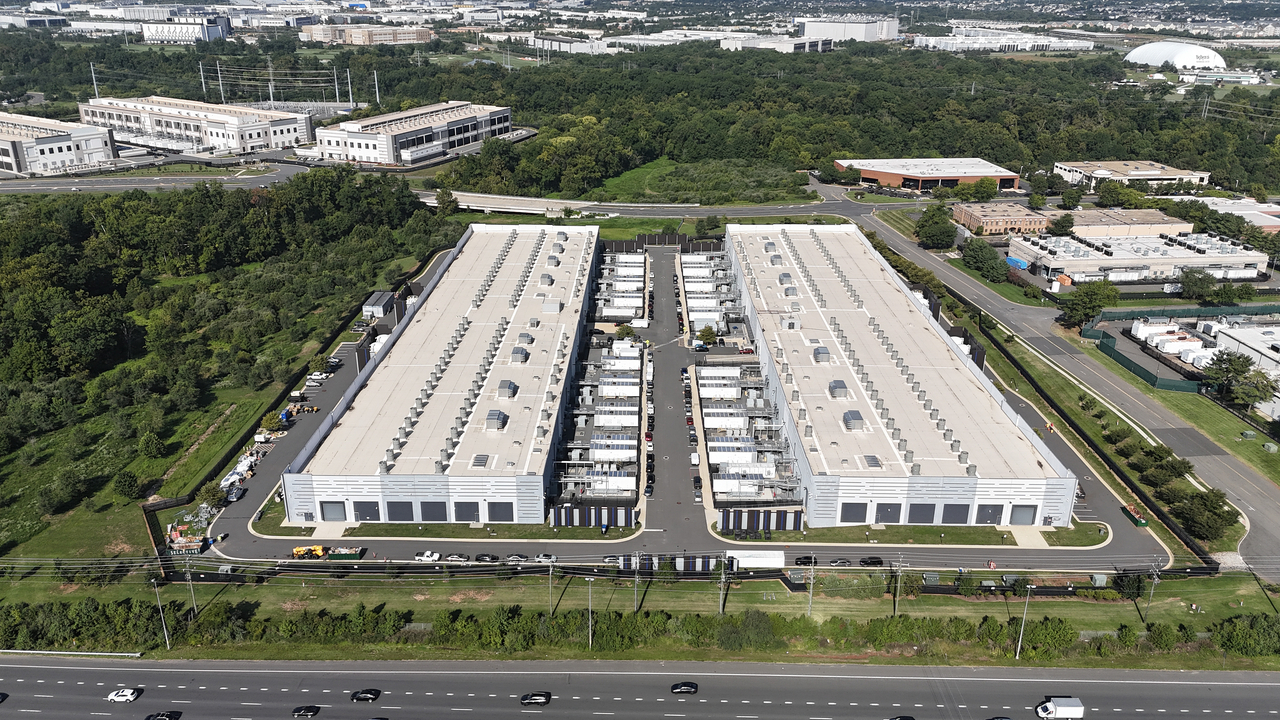
A surge in corporate bond issuance tied to AI infrastructure buildout is adding further pressure on the Treasury market. As major technology companies ramp up long-term corporate bond issuance to fund large-scale data center investments, they are prompting investors to sell Treasurys.
Goldman Sachs projected that AI hyperscalers — companies that operate massive data centers — will issue a record $420 billion in corporate bonds next year. That raises the prospect of even more Treasury futures selling or outright Treasury disposals linked to corporate bond issuance.
"Credit spreads between corporate bonds and Treasurys remain low, but investors who bought long-dated corporate bonds issued by AI hyperscalers are increasingly selling Treasury futures to reduce their exposure to losses from rising rates," Reuters said.
"Once corporate bond pricing is set around noon, everyone sells US Treasury futures in the afternoon," said Neil Sun, a portfolio manager at RBC BlueBay Asset Management.
Rising mortgage rates fuel Treasury selloff as long-bond term premium widens
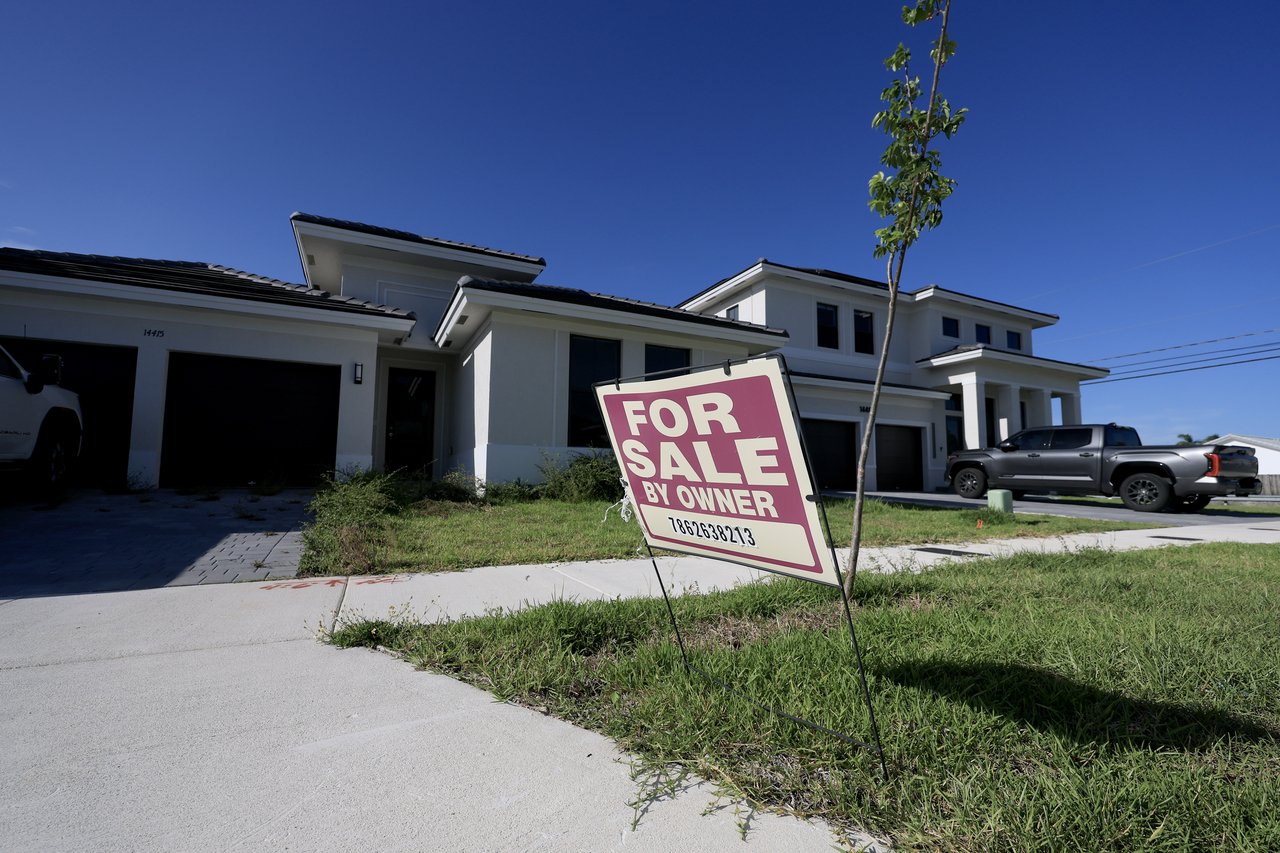
Increased hedging by investors in mortgage-backed assets is also being cited as a factor driving Treasury selling pressure. As US mortgage rates rise, financial institutions sell Treasury futures to protect against losses, which can push Treasury yields even higher.
When interest rates rise, borrowers are less likely to prepay or refinance their mortgages, extending the expected maturity of mortgage-backed securities. This creates duration extension risk, increasing those securities' sensitivity to interest rate movements.
To offset that risk, investors increase rate-hedging activity such as selling Treasury futures — and the more such trades accumulate, the greater the additional selling pressure across the broader bond market.
"There is a significant volume of mortgages originated over the past three years that carry coupon rates relatively close to current lending rates," said Mike Riddle, CEO of derivatives product developer Eris Innovations. "That structure could trigger additional hedging activity. Nine large block trades this month have already shown mortgage-backed securities investors moving aggressively to hedge their risk."
A widening gap between 10-year and 30-year Treasury yields is also being flagged as a warning sign. The fact that the 30-year yield is rising faster than the already-elevated 10-year yield may signal that investors are demanding greater compensation for holding long-dated Treasurys. This suggests anxiety about US fiscal health and the long-term supply-demand balance for bonds is growing, beyond simple concerns about benchmark interest rate hikes. This week, the spread between the two yields widened to about 37 basis points as the 30-year climbed faster than the 10-year.
"In late July, the gap between the two yields had widened to as much as 52 basis points, but what is different now is that long-dated yields are rising faster at a time when Treasury yields are already near multi-decade highs," Reuters said. "This suggests that the rise in the term premium — the extra return investors demand for holding long-term bonds amid rate uncertainty — is playing a larger role in driving yields higher than shifts in expectations about the Federal Reserve's future monetary policy."
The term premium is the additional yield investors require as compensation for the risks — including interest rate fluctuations and uncertainty — that come with holding a bond over a long period. A rising term premium means investors are demanding higher rewards to hold long-dated Treasurys.
Debriefing: The Herald Business international desk unpacks the hidden stories behind the hottest global issues. Have a question? Leave a comment.
yckim6452@heraldcorp.com