Kospi P/E at 11.05x — lowest in 3 years and 9 months
Index up nearly 2.9x, yet stocks remain undervalued relative to earnings
Foreign selling continues despite strong semiconductor results
Analysts advise staged buying as foreign selling pressure eases
The price-to-earnings ratio of the domestic stock market has fallen to its lowest level in three years and nine months.
Corporate earnings have surged on the back of a semiconductor supercycle, but share prices have failed to keep pace, leaving Kospi valuations as depressed as they were in early 2023 when the index hovered around the 2,000 level. Analysts at brokerages are advising investors to respond with staged buying as foreign selling pressure eases.
According to Korea Exchange, the Kospi P/E ratio stood at 11.05 times as of Thursday — the lowest since Jan. 6, 2023, when it was 11.02 times, a span of roughly three years and nine months. The market is now watching closely whether the Kospi P/E will break below the 11-times threshold.
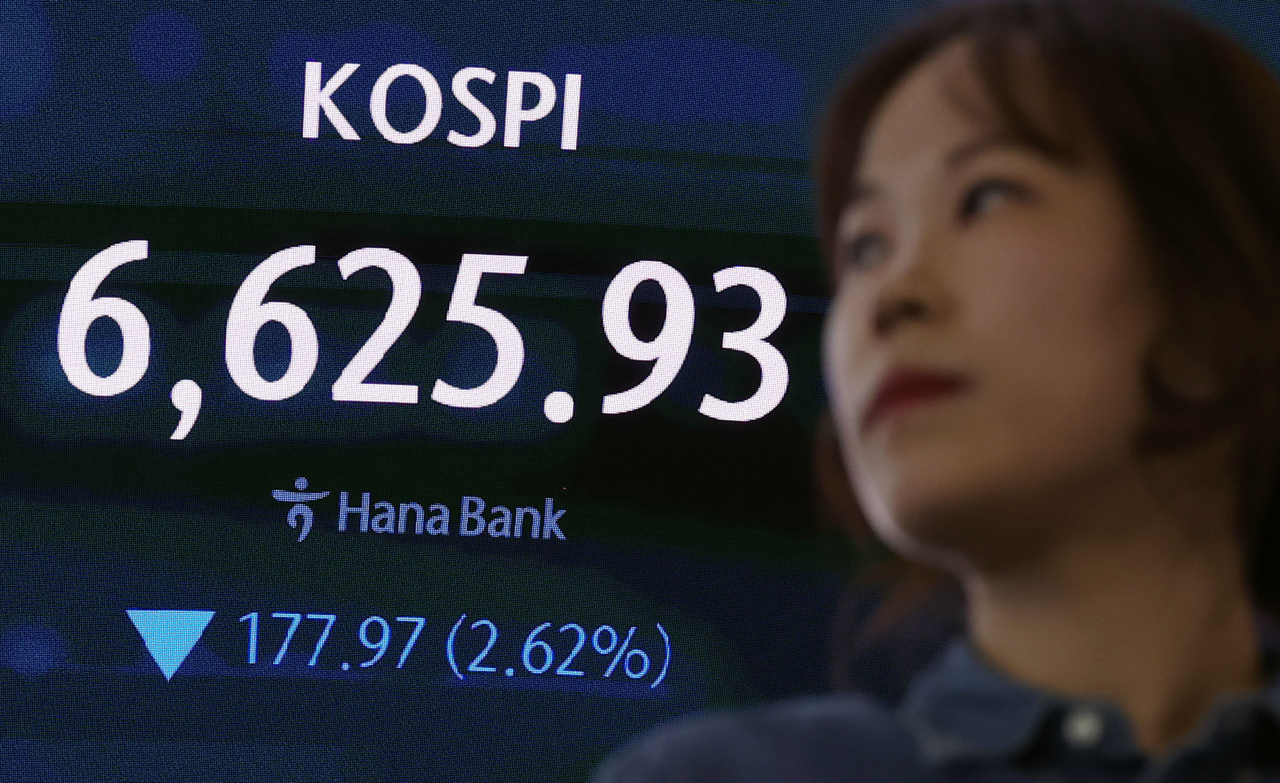
What makes the figure striking is how far the Kospi itself has climbed over the same period. The Kospi closed at just 2,289.97 on Jan. 6, 2023, but reached 6,625.93 on Thursday — a gain of nearly 2.9 times in roughly three years and nine months. Yet despite that rally, the P/E ratio, which measures how richly shares are priced relative to corporate earnings, has returned to roughly where it stood back then.
The explanation lies in how the P/E ratio is calculated. It measures how highly a stock is priced relative to the earnings a company generates. If a share price doubles from 100 won to 200 won but earnings per share triple from 10 won to 30 won, the P/E ratio actually falls — from 10 times to 6.7 times. When earnings grow faster than share prices, the P/E ratio declines.
That is precisely what has happened with the Kospi. Although the index has risen nearly 2.9 times since early 2023, a surge in corporate earnings has pushed the P/E ratio back down to the lows of three years and nine months ago. Share prices have risen sharply, yet valuations relative to earnings are as low as they were when the Kospi was trading around the 2,000 level.
The trend has been compounded recently by heavy foreign selling that has weighed on share prices even as chipmakers report improving earnings and upward revisions to profit forecasts. A sustained overhang from the supply of US government bonds and corporate bonds issued by AI-related companies has also begun to redirect investment flows away from equities.
"The supply pressure from government bonds and AI corporate bonds continues," said Lee Jae-won, a researcher at Yuanta Securities Korea. "Foreign selling has not stopped despite Samsung Electronics posting better-than-expected earnings."
Analysts say expectations for earnings improvement in the semiconductor sector remain intact, but that is not enough to conclude that a share price rebound is imminent. Because it is difficult to predict when foreign selling will subside, they recommend buying in stages as supply-and-demand conditions shift, rather than trying to time the bottom.
Lee maintained a "core" investment view on semiconductors, but stressed that earnings improvement and a normalization of foreign investor flows need to be assessed separately.
"Samsung Electronics' results supported the existing investment thesis, but they were not enough to reverse foreign selling," he said. "It has been reconfirmed that strong earnings alone are not sufficient to turn around supply-and-demand dynamics."
He added that any further increase in exposure should be tied to changes in foreign investor flows. "Rather than waiting for foreigners to turn net buyers, a strategy of responding in stages as selling pressure eases is the more effective approach," he said.
Specifically, analysts say investors should watch whether the volume of foreign selling in both the spot and futures markets shrinks as the rise in long-term US interest rates and bond market volatility begins to stabilize.
"Ultimately, the right response is not to predict when foreigners will return, but to watch for early signs of a shift," Lee said, adding that a cooling of non-arbitrage program selling and an improvement in supply-and-demand conditions for large-cap semiconductor stocks are also key indicators to monitor.
Over the longer term, the durability of chipmakers' earnings is seen as the central variable in resolving the current undervaluation. The low P/E ratio partly reflects investor wariness about the possibility of a slowdown in the sector's business cycle.
"To reduce the discount applied to peak-cycle earnings, profit sustainability beyond 2028 will need to be confirmed," said Kim Jun-young, a researcher at iM Securities. "The profitability of AI labs and hyperscaler operators will need to be demonstrated."
In the near term, Samsung Electronics' earnings release and any additional shareholder return measures scheduled for later this month are seen as potential turning points in resolving the undervaluation. Lee said investors should look to the Oct. 29 earnings announcement for clarity on the 2027 memory chip supply-and-demand outlook, the mass production timeline for HBM4, expansion of long-term supply contracts, and further shareholder return policies.
th5@heraldcorp.com