Woodford laid theoretical groundwork for forward guidance
'A framework for explaining government policy to the public'
'How people expect future policy matters for its actual effect'
Fed Chair Warsh scrapped guidance after taking office
Lawmakers criticize BOK governor's rate signals for driving up bond yields
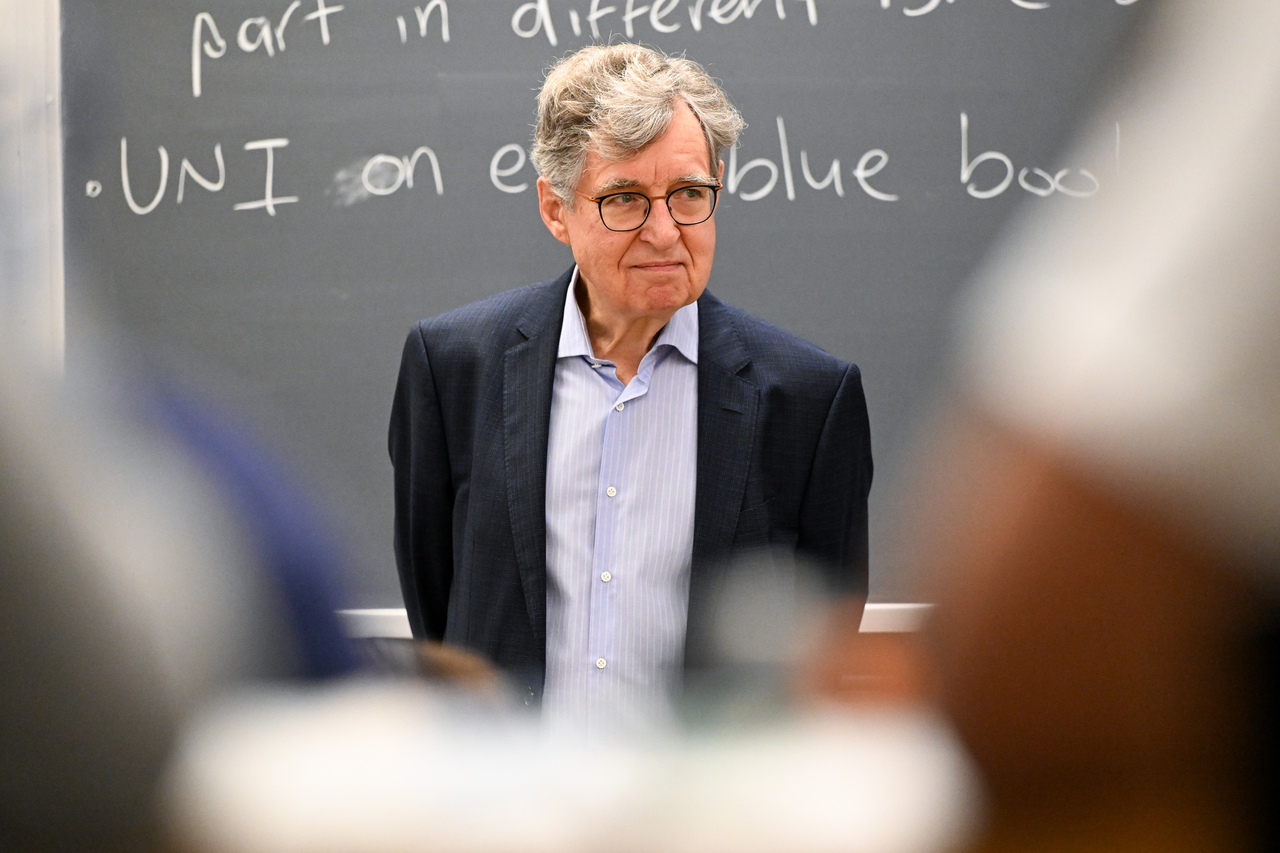
With forward guidance emerging as a flashpoint in financial circles following Federal Reserve Chair Kevin Warsh's decision to scrap the practice, Columbia University Professor Michael Woodford — widely credited with laying the theoretical groundwork for the policy tool — has been awarded the Nobel Prize in Economics.
The Royal Swedish Academy of Sciences named Woodford and Stanford University Professor Robert Hall as this year's Nobel laureates in economics on Monday (local time), according to financial industry sources. The two were recognized for their work establishing the microeconomic foundations of macroeconomic stabilization.
Woodford is particularly known for building the academic case for forward guidance — a monetary policy communication tool in which a central bank signals the future direction of monetary policy based on its assessment of economic conditions. The aim is to reduce uncertainty and stabilize markets through open communication. Woodford has argued that central banks' use of forward guidance during the 2008 financial crisis helped stabilize economies around the world.
In a telephone press conference held shortly after the prize was announced, Woodford cited forward guidance as the clearest example of his research being applied in practice. "Policy should not be conducted as if it doesn't matter how economic actors understand what the authorities are doing," he said. "Governments should not think of stabilization policy as simply pulling a lever to control the economy." He stressed the importance of communication between markets and policymakers.
He added that "how people making decisions about spending and other matters in the market expect and understand future policy is very important for the actual effect of that policy." He also said that "creating a theoretical framework that allows governments to explain and communicate to the public what policies they are implementing is equally important — that was one of the core goals I was trying to achieve in developing my analytical framework."
"This meant explaining more explicitly what path interest rate policy would take going forward, and it was a different approach from simply relying on cutting rates further right away," he said. "It didn't solve all problems like magic, but I believe it made an important contribution to economic stabilization."
However, the effectiveness of forward guidance remains a subject of debate among economists. Warsh moved to abolish forward guidance at the first FOMC meeting he chaired, declining to participate in the dot plot — the committee members' projections of future interest rates — and offering no outlook at his subsequent press conference. At the Jackson Hole symposium in August, he again signaled his skepticism, saying financial market investors had become overly reliant on Fed statements rather than underlying economic fundamentals.
The most commonly cited limitation of forward guidance is that it can lock central banks into a course of action, making it difficult to adjust policy even when economic conditions change. The Reserve Bank of Australia under then-Governor Philip Lowe is often held up as a cautionary example. Lowe had signaled that the benchmark interest rate would not rise until 2024, but surging inflation forced the bank to begin aggressively hiking rates from May 2022. The resulting surge in household interest burdens sent financial markets into turmoil.
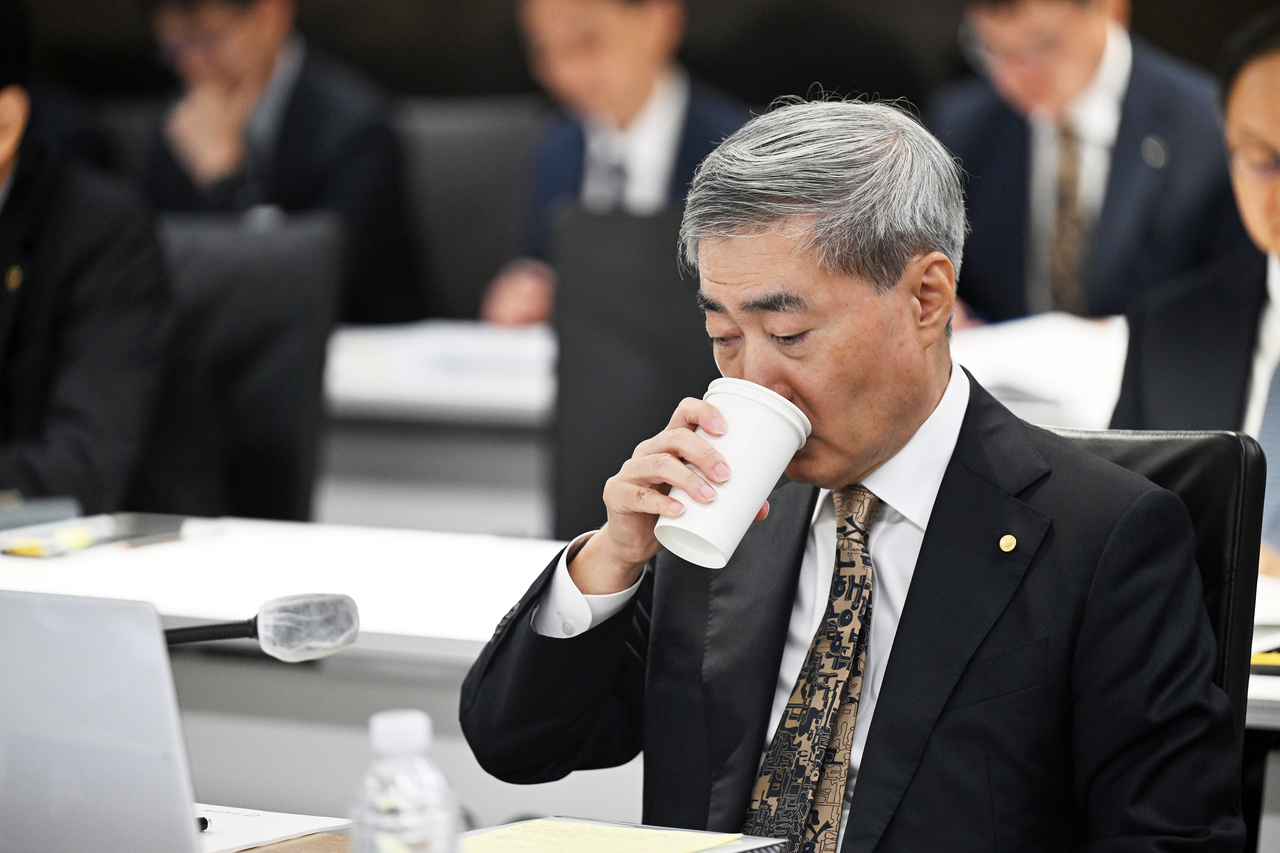
Bank of Korea Governor Shin Hyun-song also raised concerns about the pitfalls of forward guidance during his academic career. He argued that when a central bank provides overly detailed guidance on its future rate path, markets begin reacting solely to the bank's signals, while the bank in turn uses market movements as the basis for its own policy judgments — a distortion he described as the "hall of mirrors" effect.
Forward guidance drew fire at the National Assembly's Finance and Economy Planning Committee national audit of the Bank of Korea on Monday. Democratic Party of Korea lawmaker Moon Jin-seog said markets can "react preemptively to forward guidance during a rate-hiking cycle, causing a range of problems," adding that the recent sharp rise in three- and five-year government bond yields was partly attributable to Governor Shin's repeated rate-hike signals after officially flagging a May rate increase. Rising government bond yields translate into higher borrowing costs for debtors.
Shin sent multiple rate-hike signals shortly after taking office in April. After the Monetary Policy Board held rates steady at its May meeting, he told a press briefing that "whether you look at inflation, growth, the exchange rate or real estate, the direction is clear" — a remark widely read as signaling a rate increase. He went on to send further signals at official events including the bank's founding anniversary address and an inflation-target briefing, before the board raised rates at its July meeting for the first time in three and a half years. According to the Bank of Korea, the monthly average yield on three-year government bonds rose 0.578 percentage points, from 3.413 percent in April to 3.991 percent in September. The five-year yield climbed 0.618 percentage points over the same period, from 3.598 percent to 4.216 percent.
The Bank of Korea's Monetary Policy Board will hold its monetary policy direction meeting on Oct. 22 to set the benchmark interest rate. Markets widely expect the board to hold rates steady this time and raise them once more in November. With no dot plot scheduled for release at the meeting, market participants are expected to pay particularly close attention to what Shin says at his post-meeting press briefing.
kimstar@heraldcorp.com