Sales at 834.8 billion won, down 4.6% on year
Energy materials operating profit at 51.8 billion won, including customer compensation
Pohang cathode line to convert to LFP, targeting 105,000-ton capacity
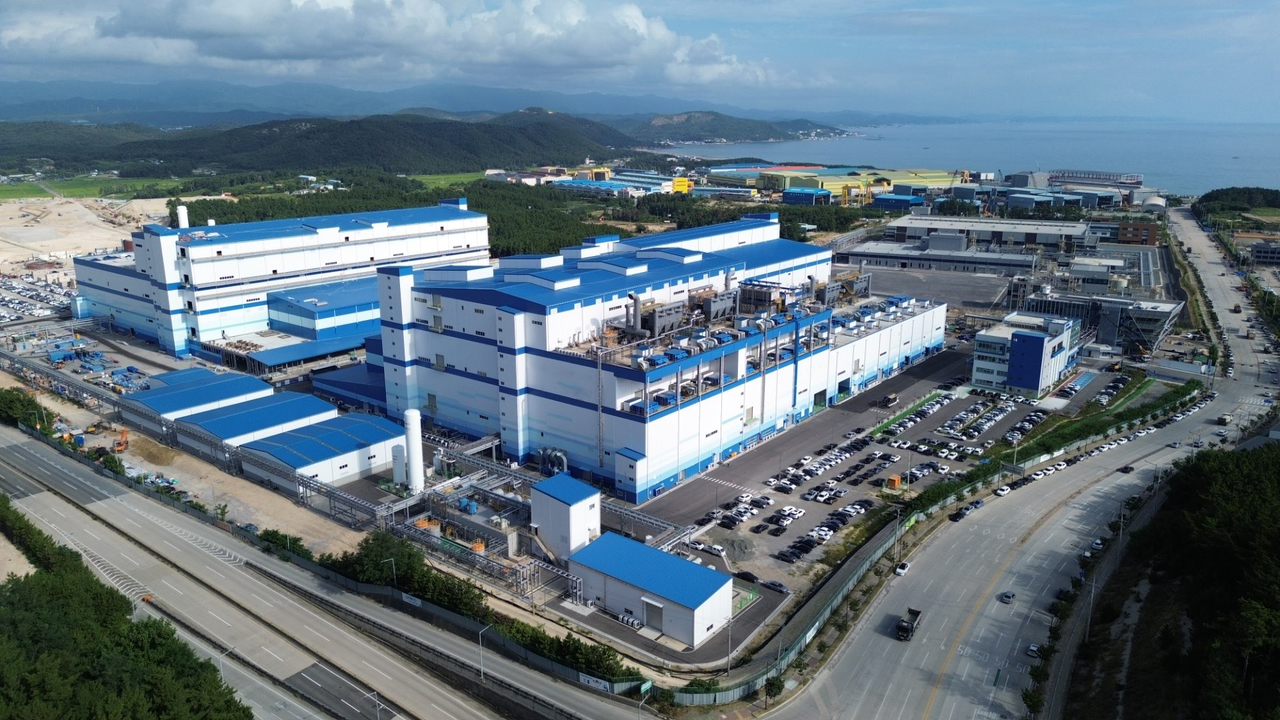
Posco Future M improved its profitability in the third quarter, driven by a recovery in cathode material sales.
The company said Monday that its consolidated operating profit for the third quarter reached 82.1 billion won ($61.4 million), up 23.2 percent from a year earlier. Compared with the previous quarter, operating profit surged 207.8 percent.
Sales for the same period came in at 834.8 billion won, down 4.6 percent on year but up 22.9 percent from the previous quarter. Net profit for the period was 46.4 billion won, roughly flat from a year ago and up 88.3 percent from the prior quarter. The operating profit margin rose to 9.8 percent, up 2.2 percentage points from 7.6 percent a year earlier.
Cumulative sales for the first three quarters totaled 2.27 trillion won, down 4.6 percent from the same period last year. Cumulative operating profit rose 49.6 percent to 126.5 billion won, while cumulative net profit grew 29.3 percent to 77.4 billion won.
The energy materials segment led the earnings improvement. The segment's third-quarter operating profit reached 51.8 billion won, a sharp increase from 2.5 billion won in the previous quarter and above the 47.4 billion won posted a year earlier. The operating profit margin stood at 11.3 percent. Sales came in at 459.6 billion won, up 40.2 percent from the prior quarter but down 13.8 percent on year.
Cathode material sales rose 44.3 percent from the previous quarter to 432.3 billion won, which the company attributed to a recovery in sales volumes to existing customers and higher selling prices. The bottom line also reflected compensation received from customers for contract non-fulfillment, alongside the volume increase.
Anode material sales totaled 27.3 billion won. The company said sales volumes to overseas customers increased despite pricing pressure from China. However, the recognition of inventory valuation losses caused profitability to deteriorate from the previous quarter.
The basic materials segment recorded sales of 375.2 billion won and operating profit of 30.3 billion won. Operating profit rose 25.2 percent from the prior quarter and 57.0 percent on year, with an operating margin of 8.1 percent. In the lime and Hwaseong businesses, selling prices for Hwaseong products — which are linked to oil prices — rose, and lime sales volumes increased. Higher lime output also reduced fixed costs per unit. In the refractories and plant business, sales declined due to lower refractory prices and reduced volumes, but profit improved as one-off costs recognized in the previous quarter did not recur.
Posco Future M is converting its ternary cathode material lines to lithium iron phosphate (LFP) lines. The company plans to convert its No. 1 cathode factory in Pohang and a second factory currently under construction, targeting a combined capacity of 105,000 tons. Additional cathode lines will be converted as new LFP orders come in, and the company has separately secured LFP output from C&P Advanced Materials starting in the fourth quarter of 2027.
In the anode material segment, the company signed long-term supply contracts with a global automaker — one worth 700 billion won in October 2025 and another worth 1 trillion won in March 2026. The company outlined a medium-term strategy to grow its secondary battery materials business on the strength of a supply chain with reduced dependence on China and its technological competitiveness.
eyre@heraldcorp.com