Industry calls for standalone 'Lending Finance Business Act,' separate legislation on illegal private lending
Licensing regime for debt-buying firms should apply only to direct collectors, sector says
Existing operators seek phased-in capital and staffing requirements
Calls have emerged for a clearer legal distinction between licensed lending firms and illegal private lenders, along with a dedicated regulatory framework befitting an independent financial sector. Proponents argue that strengthening the role of licensed lenders is, in fact, the most effective way to stamp out illegal lending.
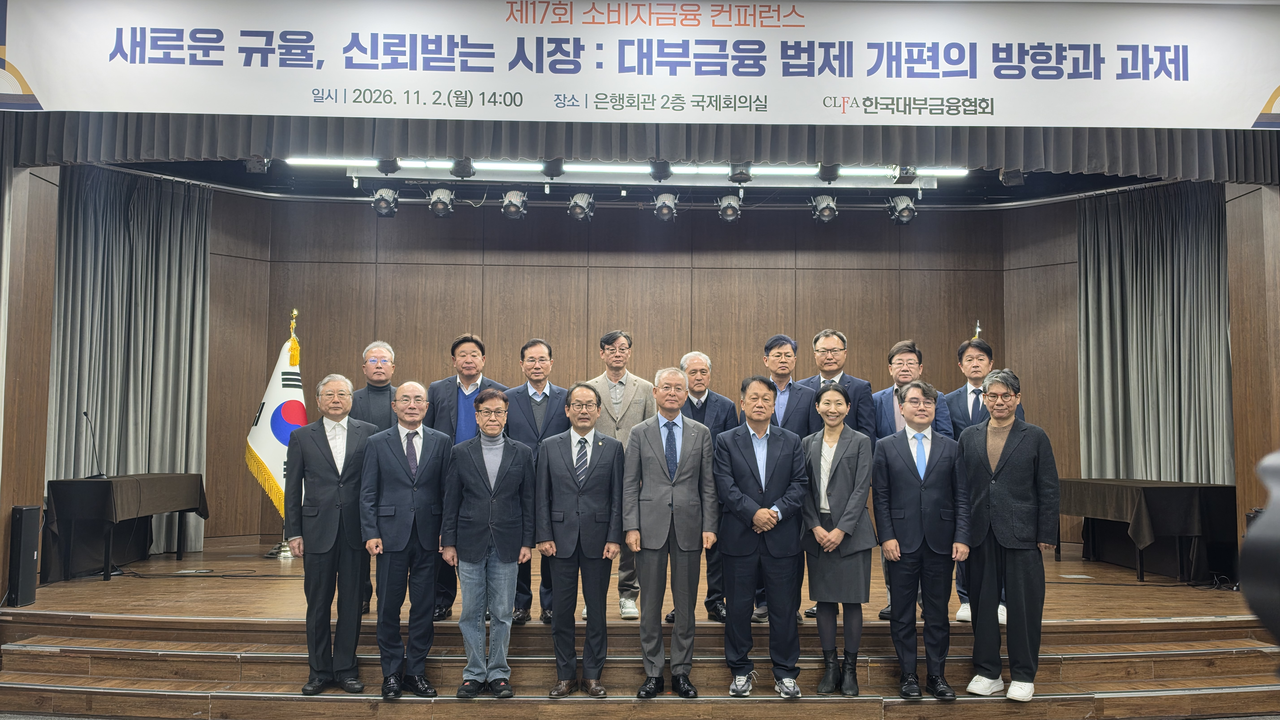
The Korea Loan Finance Association held its 17th Consumer Finance Conference on Monday at the Korea Federation of Banks building in Jung-gu, Seoul, under the theme "New Rules, Trusted Markets: Directions and Challenges for Reforming the Legal Framework of Lending Finance."
Association President Jeong Seong-ung said in his opening remarks that lending finance has served as a last-resort social safety net for low-income borrowers since it was brought into the regulated sector in 2002. "Despite being a legal form of finance, it still carries a negative stigma simply because of the word 'daeboo' (lending)," Jeong said.
Jeong added that regulations squeezing the lending industry had paradoxically fueled the illegal private loan market. "Illegal private lending must be firmly eradicated, but sound lending finance should be restructured under an independent 'Lending Finance Business Act,'" he said.
A central problem identified at the conference was that the current Loan Business Act governs not only registered lenders but also illegal private lenders and credit-providing financial institutions such as banks — all under a single statute. Joo Seong-hwan, an attorney at Law Firm Gwangjang who delivered the keynote presentation, said that while other financial sector laws — such as the Banking Act, the Savings Bank Act and the Specialized Credit Finance Business Act — each center on their respective industries, the Loan Business Act lumps together entities of fundamentally different characters.
This structure, Joo said, deepens negative perceptions of lending finance while also creating regulatory overlap and confusion. Joo proposed reorganizing the Loan Business Act into a tentatively named "Lending Finance Business Act" and separating regulations on illegal private lending into standalone legislation. He also suggested transferring conduct-of-business rules that currently apply to banks and other credit-providing institutions to the Financial Consumer Protection Act.
Democratic Party of Korea lawmaker Kang Jun-hyeon also expressed support for improving public perceptions of the lending industry. "Using the term 'registered loan company' can lead people to mistakenly think it might be illegal," Kang said, adding that a name change may be warranted. Kang said he would consult with the Financial Services Commission on ways to ease funding difficulties for lending firms and support high-performing operators.
Beyond the legislative overhaul, participants said tightening entry requirements should also be calibrated to reflect how firms actually operate. The FSC announced May 28 a plan to convert the current registration system for debt-purchasing and collection firms — which buy overdue loans and recover them — into a licensing regime, in order to prevent market overcrowding and excessive or prolonged collection practices. The key requirements under the plan include at least 50 percent investment by a financial company, minimum paid-in capital of 3 billion won ($2.24 million) and a permanent workforce of at least 20 employees.
However, pushback emerged over the fact that not all firms that purchase delinquent loans actually demand repayment directly from debtors. Applying the same licensing requirements to firms that outsource collection to third parties or recover debts through legal proceedings or debt-restructuring repayment plans was described as excessive.
A survey of association members presented by Lee Han-gyeong, another attorney at Law Firm Gwangjang, found that 56 of 120 responding firms — 46.7 percent — conducted no direct collection at all. Firms where direct collection accounted for 20 percent or less of activity reached 84, or 70 percent of respondents.
Lee proposed classifying firms that do not engage in direct collection as a separate category — tentatively called "loan debt purchase management businesses" — and keeping them under the existing registration system, while applying the licensing regime only to "loan debt purchase collection businesses" that carry out direct collection. The rationale was that the risks of holding purchased debt and of directly demanding repayment from debtors differ, and regulation should reflect that distinction.
The burden the tightened licensing requirements would place on existing operators was also flagged as a concern. Among 816 debt-purchasing and collection firms that submitted capital data as of the end of last year, 716 — about 88 percent — had paid-in capital below 3 billion won. A sudden increase in the capital threshold could make it difficult for a significant number of firms to continue operating.
The FSC has said it will grant existing operators a three-year transition period from the date the law takes effect, during which the requirement for at least 50 percent investment by a financial company will not apply. However, any firm that fails to obtain a license before its registration expires must sell or cancel its holdings of overdue debt within six months. Lee argued that additional transitional measures should be put in place to allow existing firms to meet the capital and staffing requirements in stages, and that firms not engaged in direct collection should be permitted to continue operating under the registration system.
Association President Jeong said he agreed with the financial authorities' policy goals of strengthening debtor protection and preventing excessive collection, but stressed that "rather than uniform entry regulations, what is needed is a phased and flexible policy design that allows operators to continue their role within the bounds of the law."
snsd@heraldcorp.com