Won could bridge retail and wholesale payments
Legal conflicts, AML checks among key concerns
Smaller remittance firms risk being left out
Stablecoin-based transfers called costly in practice
South Korea could serve as a bridge between Nexus, Asia's real-time cross-border remittance network, and Agora, an international tokenized payment project, a banking official said Wednesday. However, a cautionary note was also raised that joining Nexus as a latecomer could leave South Korea with little say over the project's rules and direction.
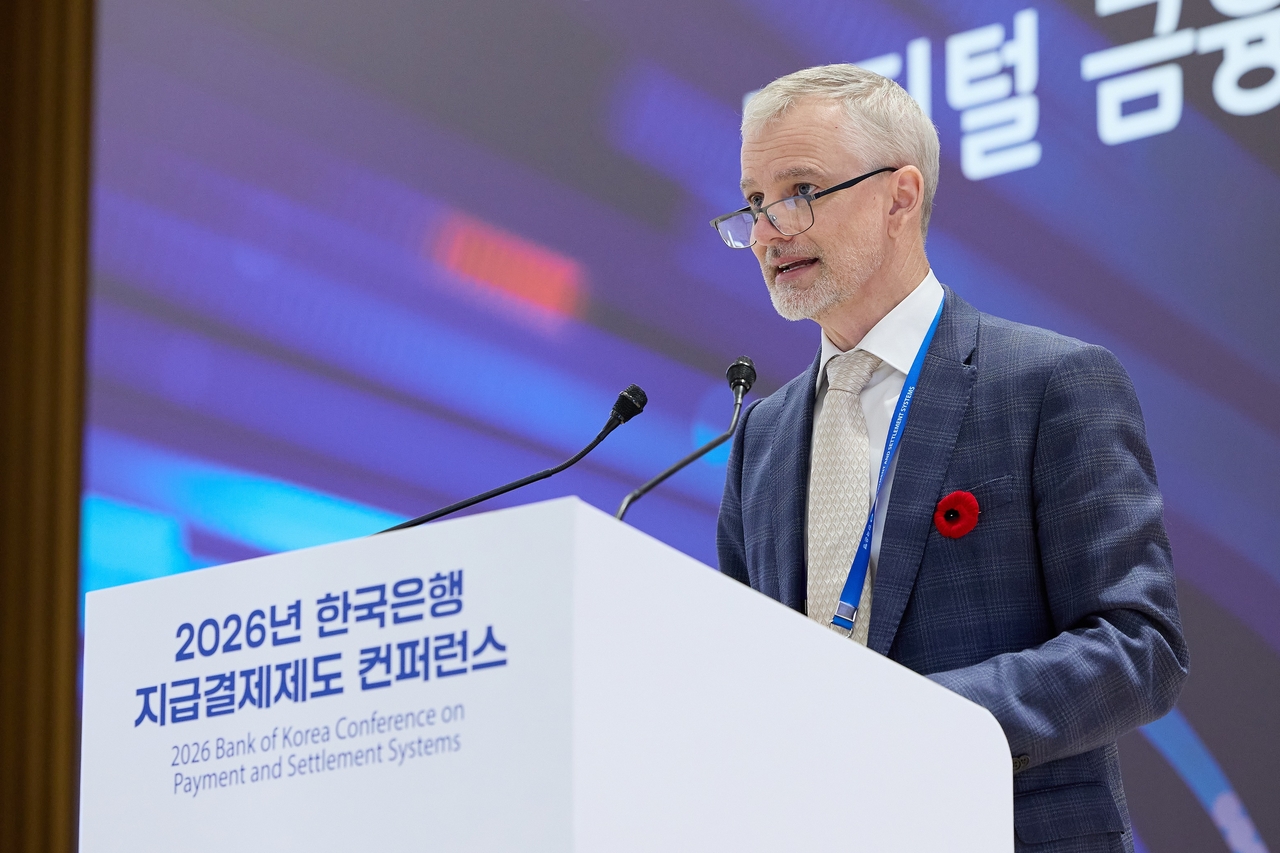
Choi Cheol, head of Shinhan Bank's Web3 financial business division, made the argument at the second session of the Bank of Korea's 2026 Payment and Settlement Systems Conference. "Nexus and Agora have no overlapping participating currencies at all," Choi said. "When the EU joins Nexus down the road, the euro will likely become the first cross currency — but if South Korea moves quickly, the won could become one too."
The European Central Bank is already pursuing a plan to connect its own instant payment system to Nexus.
Both Nexus and Agora are global financial infrastructure projects aimed at improving the speed and efficiency of cross-border remittances and payments. Nexus involves countries from the Association of Southeast Asian Nations, while Agora counts eight countries as participants — South Korea, the United States, France, the United Kingdom, Japan, Switzerland, Mexico and Canada.
"Because the won is already in Agora, connecting South Korea to Nexus would link retail and wholesale payments in won," Choi said. "I think it could become one way to tie the two infrastructures together."
While Nexus is a retail-focused network that links each country's fast payment system to enable cross-border transfers, Agora is a wholesale platform that processes international settlements using tokenized central bank reserves and commercial bank deposits.
Ko Young-mi, a professor at Soongsil University, urged caution. Joining the Singapore-centered Nexus project as a latecomer, Ko said, could make it difficult for South Korea to have its legal framework, interests and arguments reflected in the system. "In the long run, we also need to take a leading role in shaping the system ourselves," Ko added, "but we should also keep in mind that we could miss the window if we wait too long."
Ko identified five legal issues that would arise from adopting Nexus: conflicts between national laws, differences in when payment finality is determined, anti-money-laundering screening within transactions that complete in seconds, cross-border transfer of personal data, and allocation of liability in the event of an incident. Ko added that it would also need to be examined whether adopting the system domestically would require amendments to the Foreign Exchange Transactions Act.
Ko also raised competition law concerns, warning that if a public platform offered services at ultra-low fees, existing private remittance operators could suffer serious damage. Ko further said that only banks and large fintech firms equipped with anti-money-laundering infrastructure would be able to participate, potentially leaving smaller remittance providers behind.
Meanwhile, Andrew McCormack, chief executive of Nexus Global Payments, compared stablecoins with the Nexus project. He acknowledged that stablecoin-based overseas remittances are in actual use, noting that so-called "stablecoin sandwich" transactions — where funds are converted into a stablecoin in one country, sent across a border, then converted back into local currency in another — do in fact occur. However, he said the costs of buying and selling stablecoins make such transactions considerably more expensive in practice.
McCormack also said that stablecoin transactions follow only the rules of individual issuers and lack any overarching framework. "Nexus is infrastructure built from the design stage to comply with regulation, and banks and payment service providers can compete on top of it," he said.
kimstar@heraldcorp.com