Global ranking climbs from 25th to 15th after integrated entity launch
China's share of sales falls sharply; North America, Europe gain ground
High-margin engine business added to portfolio boosts growth prospects
Sales, production integration and aftermarket competitiveness reinforced
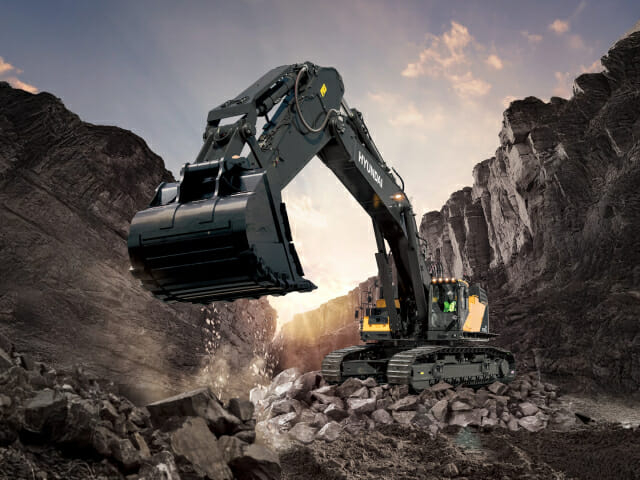
HD Construction Equipment has been shoring up its earnings stability this year by diversifying its global sales regions and expanding its business portfolio following the launch of its integrated entity. The company's ability to weather regional demand swings in the construction equipment business has improved, and the addition of a high-margin engine segment has strengthened its medium- to long-term profit base.
According to Korea Ratings, HD Construction Equipment has secured a top-tier position in the domestic construction equipment market since the merger and has also climbed in global rankings — rising from around 25th place to 15th, with a market share of 2.3 percent. The company still trails industry leaders such as US-based Caterpillar and Japan's Komatsu in construction equipment sales, but has established a strong standing in select emerging markets including Brazil, India and Africa.
HD Construction Equipment has been diversifying its sales footprint across the domestic market as well as China, Europe, North America, India and Brazil, bolstering its resilience against economic fluctuations in any single region. The construction equipment business is heavily export-dependent, making earnings vulnerable to shifts in construction activity and mining development demand in key markets. Broadening the regional sales mix can help cushion the impact when demand weakens in a particular market.
In practice, the shift is already visible in the numbers. Comparing 2021 figures with cumulative third-quarter results this year, China's share of construction equipment sales fell sharply from 25.9 percent to 8.1 percent, while the domestic market's share edged down from 14.9 percent to 13.3 percent. By contrast, North America's share rose from 9 percent to 12.7 percent, Europe's from 15.1 percent to 18 percent, and India's from 4.2 percent to 7.6 percent. The share attributed to other regions expanded from 30.9 percent to 40.4 percent. Korea Ratings said the post-merger integration of the two companies' sales networks has improved the overall level of regional diversification.
The merger is also bearing fruit on the portfolio side. The addition of the high-margin engine segment has broadened the company's profit base and reinforced a business structure that can offset volatility in the construction equipment business. Global demand for construction equipment is expected to remain solid, supported by data center and rental demand in North America and mining and infrastructure demand in emerging markets. However, sales in the Middle East and Africa have recently declined due to logistics disruptions stemming from the prolonged war in the Middle East.
The engine segment continues to post strong operating profitability, driven in part by growing demand for industrial engines. In October last year, the company signed a gas power generation engine supply contract with US-based Enchanted Rock worth 387.9 billion won ($291 million), securing a portion of its supply volume for 2027 and 2028 and improving earnings visibility for its power generation engine business. Capacity expansion is also expected to support growth in the segment. Korea Ratings said that with the completion of a new factory in Gunsan and the scale-up of the Incheon factory this year, production capacity is expanding, and earnings from the engine segment — led by power generation engines — are expected to grow for now.
Strengthening competitiveness in the aftermarket segment is also seen as a factor that will support future profitability. The post-merger integration of sales and production systems is expected to drive cost efficiencies, while the consolidation of service networks and standardization of parts are seen as enhancing the segment's competitive edge. Korea Ratings said that given these merger synergies and the engine segment's growth trajectory, the company's improved profit-generating capacity is expected to be sustained over the medium to long term.
keg@heraldcorp.com