South Korea's simplified-underwriting insurance market — which allows people with pre-existing conditions to obtain coverage — surpassed 13 trillion won ($9.4 billion) in premiums in the first half of this year alone. That figure represents nearly 75% of last year's full-year total of about 17.8 trillion won, achieved in just six months, and analysts expect annual premiums to far exceed 20 trillion won for the full year. The market is also widely expected to overtake the so-called "second national health insurance" — the actual-loss insurance segment — this year.
Challenging actual-loss insurance dominance — market up 50% in 3 years
Combined first-half premiums written for simplified-underwriting insurance at 10 major life and non-life insurers reached 13.21 trillion won on Wednesday, surpassing the full-year 2023 total of 11.84 trillion won in just six months and amounting to 74.3% of last year's full-year figure of 17.79 trillion won.
The simplified-underwriting insurance market has grown more than 50% over the past two years, from 11.8 trillion to 17.8 trillion won, with the non-life insurance sector leading the expansion by posting roughly 30% annual growth. At this pace, full-year premiums are widely expected to well exceed 20 trillion won, and the market is likely to surpass the actual-loss insurance segment as well. The gap has already narrowed sharply: actual-loss insurance premium revenue stood at 18 trillion won last year, leaving a difference of only about 180 billion won with the simplified-underwriting segment across the 10 insurers.
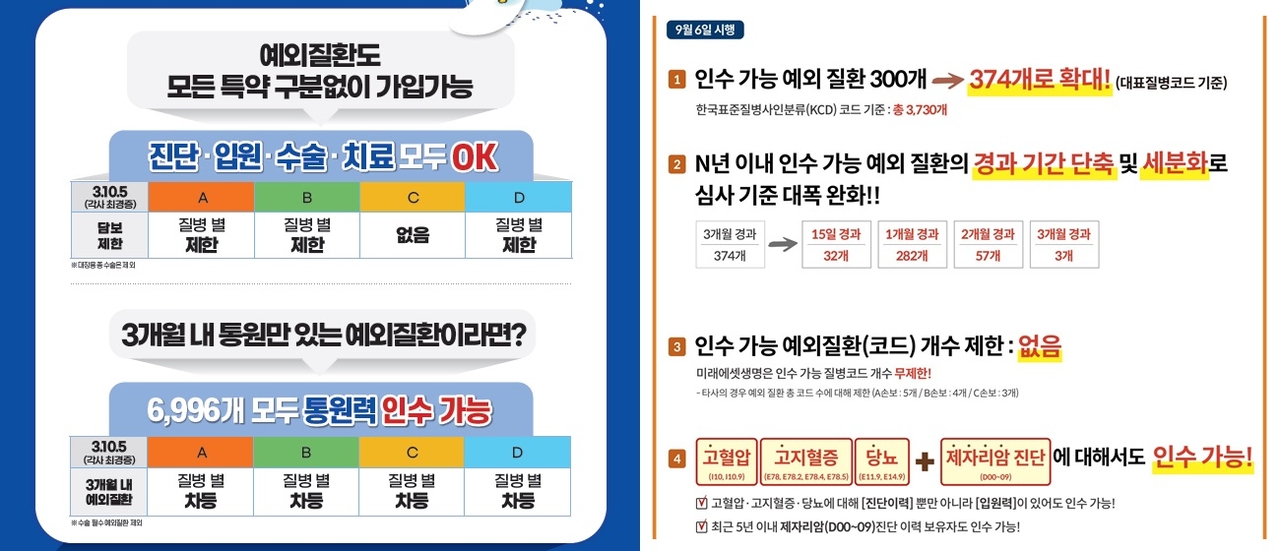
Simplified-underwriting insurance is a form of health coverage with relaxed underwriting standards that allows people with chronic conditions such as hypertension or diabetes, or those with a past medical history, to enroll. Products are typically labeled with numbers such as "3·10·5," meaning applicants need only disclose whether they were hospitalized or underwent surgery within the past three months, whether they were diagnosed with cancer within the past 10 years, and whether they have a history of serious illness within the past five years.
Industry observers attribute the market's rapid growth to two converging forces: the fast-growing population of people managing chronic conditions, and the well-known insurance-industry dynamic that those who have been ill are more motivated to seek coverage. For insurers, simplified-underwriting products also carry higher premiums than standard offerings, making them attractive vehicles for building contractual service margin — the key forward-looking profitability metric under the IFRS17 accounting standard.
Competition has evolved beyond simply lowering enrollment barriers. Insurers are now slicing disclosure requirements and premium structures into finer gradations based on the type of medical history and the length of a claim-free period. One insurer recently launched a simplified-underwriting product that requires separate disclosure for cancer history and cardiovascular disease history. Another operates a product requiring only cancer-related disclosure for enrollment, alongside a separate product that lowers premiums for applicants who additionally disclose whether they have hypertension, diabetes or dyslipidemia.
The market's rapid growth does not mean consumers should sign up without scrutiny. Simplified-underwriting products accept applicants with medical histories but charge accordingly — premiums typically run 20 to 50 percent higher than standard health insurance for equivalent coverage, and hospitalization and surgery benefit limits are often set lower. Even non-renewable base policies can see total premiums rise over time if riders are structured to auto-renew.
However, as more products now offer premium discounts for applicants with minor medical histories or long claim-free periods, consumers are advised to select the disclosure category that matches their health status and compare two or three products. Omitting a past diagnosis can result in a claim being denied, so applicants should review medical records and prescriptions in advance and disclose their history accurately.
"The market is shifting toward segmenting rates by each customer's medical history to support the most suitable premium structure for each individual," an industry official said. "In an era when healthy enrollees are shrinking, there is a race to identify relatively healthier customers even from among those with medical histories."
A bigger market, but falling new contracts and regulatory headwinds remain challenges
Even as the overall market has expanded, the flow of new customers has slowed. New-contract counts for simplified-underwriting insurance at the 10 life and non-life insurers peaked at about 6.16 million in 2024 before turning lower. The figure fell 14.4% to about 5.27 million last year, and the decline has continued this year, with only about 2.43 million new contracts recorded in the first half.
Industry officials attribute the trend to a broader contraction in the long-term personal insurance market, as well as a strategic shift by insurers toward managing portfolios around appropriately priced contracts rather than high volumes of small-premium policies. "There are some loss-ratio pressures from the expansion of the health insurance market, but we are managing underwriting standards and loss ratios in tandem," another industry official said.
Regulatory uncertainty adds another layer of complexity. Financial authorities have recently required insurers, when designing new coverage items, to apply a conservative projected loss ratio of 90% if sufficient claims data has not yet accumulated. The complication lies in a quirk of simplified-underwriting products: even a coverage item sold under a standard policy for years — and therefore carrying an established claims record — is reclassified as a "new" item once repackaged under a new disclosure structure for a simplified-underwriting product, triggering the conservative standard. The result is that profitability appears lower than it actually is, reducing insurers' incentive to launch new simplified-underwriting products.
Despite these concerns, the industry expects the market to keep growing. Super-aging demographics are structurally expanding the pool of people seeking simplified-underwriting coverage, creating a baseline level of sales that does not depend on aggressive marketing. "People who have been ill are more motivated to seek insurance, and simplified-underwriting products are in effect the only option available to them," another industry official said. "There may be some moderation in pace, but this is not a market where demand disappears."
psj@heraldcorp.com