Remarks at monetary policy press conference
Preemptive policy seen helping cool housing prices
October decision to hinge on inflation data, nominal GDP
Exchange rate still elevated versus historical norms
One more hike possible over next four Monetary Policy Board meetings
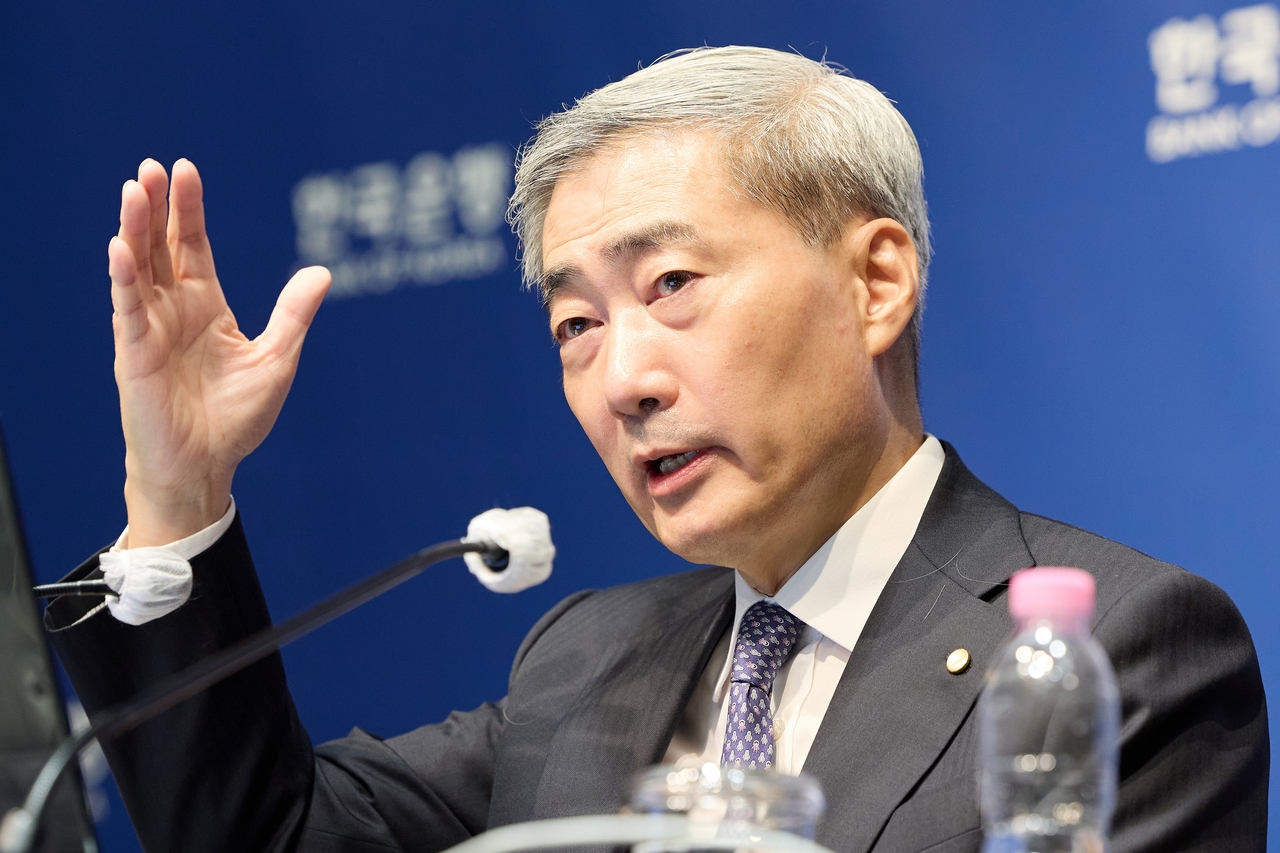
Bank of Korea Governor Shin Hyun-song said Thursday that consecutive interest rate hikes were necessary because "preemptive action on monetary policy is needed to pursue macroeconomic stability."
Shin made the remarks at a monetary policy press conference Thursday morning. He said South Korea's economy is expected to maintain solid growth next year on the back of strong semiconductor demand and improving income conditions, and that core inflation will remain elevated, keeping overall price pressures persistent. The Monetary Policy Board raised the benchmark interest rate by 25 basis points to 3 percent from 2.75 percent on Thursday — the second consecutive hike following last month's increase.
Shin said most research findings show that preemptive monetary policy action "quickly stabilizes inflation expectations, reduces the degree of tightening needed, and eases the burden on growth." He added that such an approach "will also help moderate housing prices in the Greater Seoul area."
He also invoked a Korean proverb about using a small hoe rather than a large spade to fix a problem, saying the Bank of Korea had taken the "small hoe" approach this time. The remark was widely interpreted as meaning the central bank had moved to raise rates before demand-side pressures from the semiconductor boom could fully feed through to inflation.
On Monetary Policy Board member Hwang Geon-il's dissenting vote in favor of a hold, Shin said Hwang "agreed on the big picture" and that the board had engaged in deep discussion about how best to proceed, adding that the difference came down to "a tactical disagreement."
Shin said the market had anticipated a rate hike in August or October, and that by acting early the Bank of Korea had reduced costs. He noted that the exchange rate had moved further in the won's favor and that government bond yields had edged down despite the rate increase. "We believe the market has reacted positively to the Bank of Korea," he added.
Shin also cited a deepening of financial instability as a factor behind the consecutive hikes. He said the Financial Vulnerability Index, which measures medium- to long-term fragility in the financial system, had risen above its long-term average. "Interest rates are not a cure-all, but broadly speaking, when rates go up, the vulnerability index tends to come down," he said.
Shin assessed the won-dollar exchange rate as still elevated. "The exchange rate has stabilized to some extent, but it remains high compared with previous years," he said, adding that preemptive monetary policy action helps anchor the foreign exchange market and contributes to exchange rate stability.
"In that sense, I think the preemptive response was appropriate," he said. He added that further preemptive action leaves room for the won to strengthen further, which would offset a significant portion of import price increases and contribute to price stability.
On the future direction of monetary policy, Shin said the dot plot of board members' six-month rate projections points to a gradual further increase. "The median of the current dot plot is 3.25 percent," he said. "There are four Monetary Policy Board meetings over the next six months, which means one more hike from the current level." He explained that because two hikes had already been delivered, the board needed to assess their effects, and expressed confidence that the two preemptive increases would help bring down the exchange rate and stabilize import prices and inflation.
Shin identified August and September inflation data and the second-quarter nominal GDP figure as the key indicators for the October monetary policy decision. "We will have the August and September inflation data before the October meeting — those figures are important," he said. "We also need to look at the preliminary second-quarter GDP figure, and particularly the nominal GDP data due for release in early September." He added that sentiment indexes also matter, noting that business confidence appears to reflect strong growth and improving income conditions but that the benefits have been slow to reach all economic actors.
Shin also said the output gap — the difference between actual and potential GDP — is expected to turn positive significantly earlier than initially forecast. A positive output gap indicates the economy is running above its potential, while a negative gap signals that actual output is falling short. "We appear to be almost at the threshold for a positive output gap," he said. He added that the Bank of Korea is revisiting concepts such as the potential growth rate and the neutral interest rate and will have an opportunity to share further findings.
In its revised economic outlook released Thursday, the Bank of Korea raised its growth forecast for this year to 3.3 percent, up 0.7 percentage points from its May projection of 2.6 percent.
On the debate over whether the government's expansionary fiscal policy is out of step with the central bank's monetary tightening, Shin said the answer depends on the nature, scale and purpose of fiscal spending. "If fiscal spending is directed toward investment that can lift future growth, it can raise the potential growth rate and the two policies need not be out of sync," he said.
"The principle is fairly clear: can fiscal policy raise the growth rate?" he said. "If so, it can actually work in a direction that supports monetary policy."
kimstar@heraldcorp.com
forest@heraldcorp.com