Interview with Athanasios Vamvakidis, deputy director
Central banks must anchor trust as payments go digital
Tokenized asset market at $65 billion, led by bonds and money market funds
Wider adoption could amplify leverage and liquidity risks
Repo market flagged as key concern; hedge funds seen at the forefront
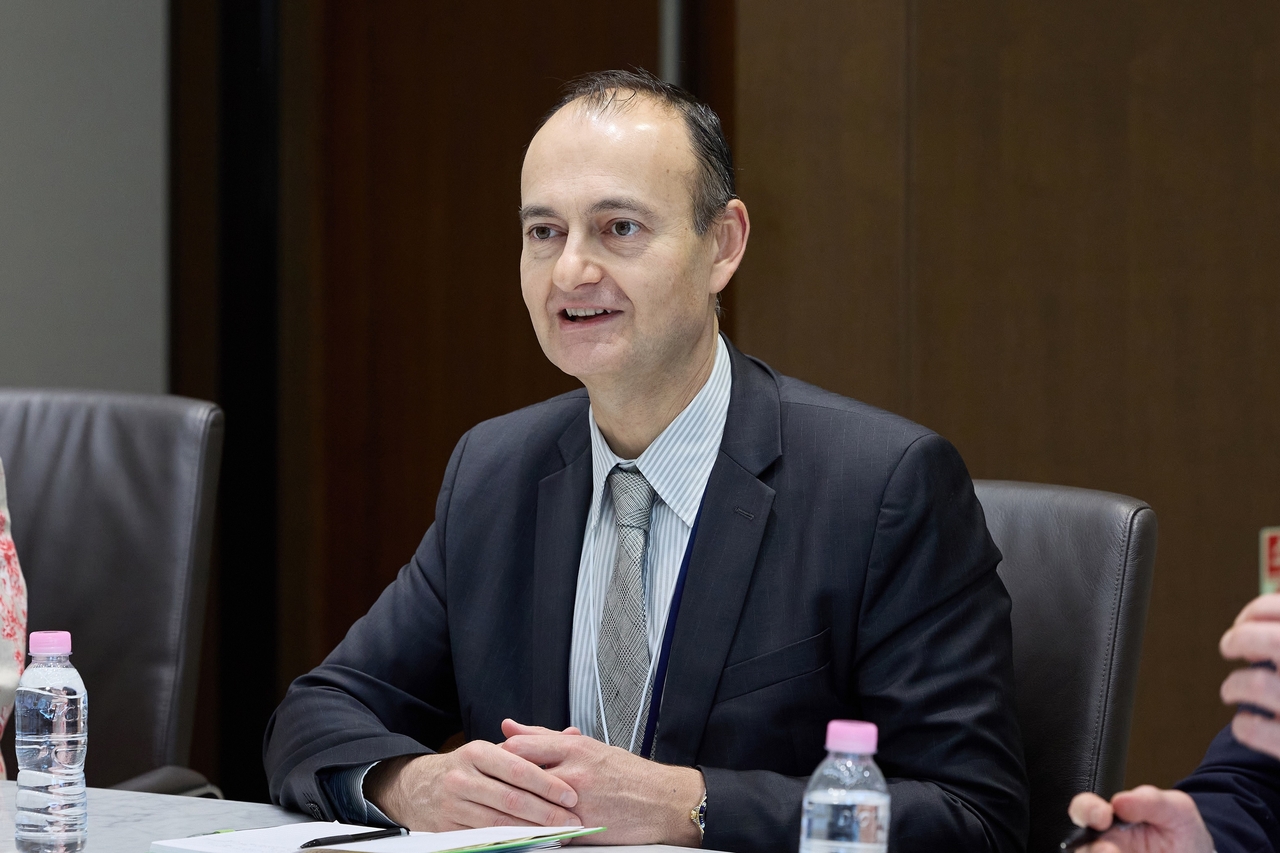
Athanasios Vamvakidis, deputy director of the IMF's Monetary and Capital Markets Department, said central banks must remain at the center of the payments process as the world moves toward digital settlement.
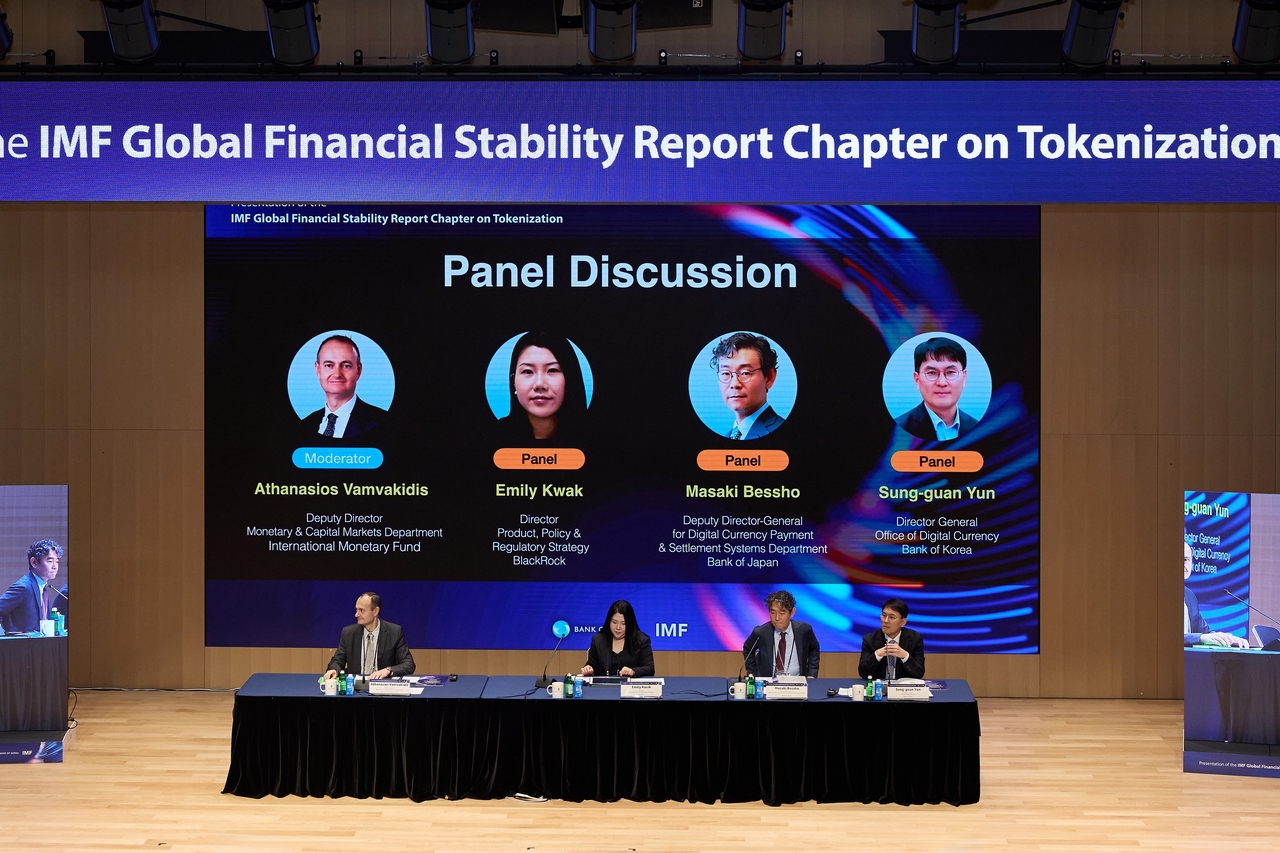
Vamvakidis made the remarks Thursday in an interview with reporters following a joint Bank of Korea-IMF event presenting a report titled "The Tokenization Expansion: New Efficiencies and Vulnerabilities."
The report was included as a standalone chapter in the IMF's Global Financial Stability Report, which the fund publishes twice a year to assess risks and vulnerabilities in the global financial system.
Tokenization refers to the technology of recording financial assets — such as bonds and shares — as digital tokens on a distributed ledger such as a blockchain. By consolidating ledgers that multiple intermediaries previously maintained separately, it can reduce transaction costs and speed up settlement. The market remains small: as of July, the tokenized real-world asset market stood at $65 billion, according to the report. Of that, bonds and money market funds accounted for roughly $48 billion, while equities totaled about $2.3 billion.
The report also identified regulatory clarity and safe, scalable settlement assets as conditions for tokenization market growth, arguing that money changing hands in securities transactions should ideally settle in central bank money. Using privately issued deposit tokens or stablecoins, it warned, could introduce credit and liquidity risks tied to the issuer, contagion risks, and concentration risks from over-reliance on a single issuer.
"In a world where payments are going digital, trust is paramount — and that is why central banks need to be at the center," Vamvakidis said. Caio Fonseca Ferreira, deputy division chief at the IMF, added that when infrastructure becomes systemically important, international standards typically recommend the use of central bank money.
On privacy concerns surrounding CBDC adoption, Vamvakidis said cash transactions offer complete anonymity, but that privacy concerns become real the moment a transaction goes digital — which is precisely why appropriate regulation is needed. "There is no reason these concerns cannot be resolved in a world moving toward tokenization, stablecoins, deposit tokenization or CBDCs," he said. "Ultimately, it is a matter of regulation." Ferreira said the issues could also be addressed through framework design, citing the need for regulatory clarity on the legal and institutional status of tokenization and the availability of safe, sound and scalable settlement assets.
The report also warned that risks could grow if tokenization spreads further. Wider adoption would increase dependence on operational infrastructure and could amplify traditional risks — such as leverage and liquidity — through new channels. While systemic risks from tokenization remain limited at current scale, the report said broad adoption could make financial market infrastructure, legal foundations and liquidity management central challenges for financial stability.
"As collateral management becomes more efficient, financial institutions may take on considerably more leverage," Ferreira warned. "If an external shock hits under those conditions, the knock-on effects from that added leverage could be far greater than what we see today."
The repo market stands out as a prime example. A repo transaction involves borrowing short-term funds against collateral such as bonds, and the speed at which collateral can be moved and reused determines the scale of borrowing — making repos a tool hedge funds use to build leverage. The report noted that tokenized repo is drawing growing attention for its collateral management efficiency, with transaction volumes rising. On a 30-day moving average basis, volumes stand at around $371 billion. "Hedge funds are often the first movers and leaders at the frontier of change, so some of the related risks may become most visible first in their behavior and operations," Vamvakidis said.
The report further noted that round-the-clock trading combined with automated clearing could accelerate margin calls and liquidations, heightening liquidity risks — including redemption pressures — during periods of stress. An IMF analysis of the US tokenized equity market found that liquidity was lower and volatility roughly 1.5 times higher than in traditional equity markets.
The officials stopped short of specifying the scale at which tokenization could become a systemic risk. "You cannot determine systemic risk by looking at a single dimension," Ferreira said. "You need to examine overall scale, user characteristics, and whether alternative products or substitutes exist."
Tokenization is also expected to affect foreign exchange markets and monetary policy. On the foreign exchange implications, Vamvakidis said investors could find themselves exposed to currency risks they did not previously bear, potentially amplifying volatility in FX markets — though he added that the foreign exchange market is the largest in the world and excessive concern is unwarranted. Ferreira noted that while tokenization could improve access to overseas assets and make it easier for foreign investors to enter domestic markets, such access would still flow through regulated financial institutions. "If capital flows reach a level of concern, governments can implement capital flow management measures as needed," he said.
On monetary policy, Vamvakidis said exchange rate overshooting driven by capital flows would directly affect how monetary policy stances are set, and that countries with weak fundamentals could face risks of currency dollarization. "Strengthening macroeconomic fundamentals and improving underlying conditions will become even more important," he added.
Asked about Bank of Korea initiatives such as "Project Han River," Vamvakidis said briefly that he understood South Korea to be pursuing "reserves tokenization." Ferreira said the IMF had not conducted a separate assessment of the Korean project, but that he understood South Korea's efforts to address some of the report's recommendations.
The Bank of Korea is advancing the second phase of Project Han River, under which commercial banks would issue deposit tokens backed by a wholesale CBDC. The Ministry of Economy and Finance said it plans to launch a government bond tokenization pilot linked to the wholesale CBDC next year.
kimstar@heraldcorp.com