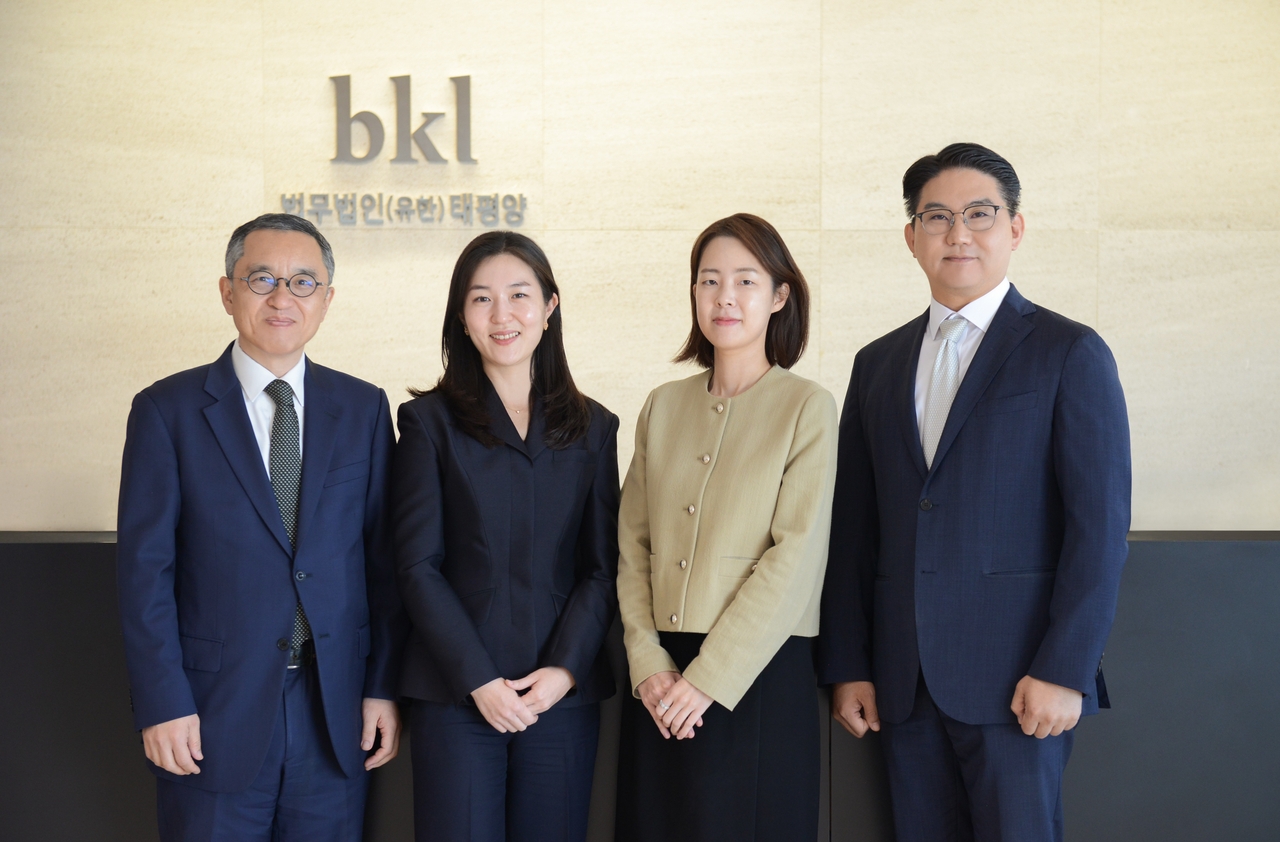
[Interview with Bae, Kim & Lee's IPO team: Shin Hee-kang, Jung Hee-seok, Ha Young-jin, Hyun Ye-rim]
Expanded regulation raises bar for subsidiary listings
Group governance and parent shareholder impact require thorough review
Best-efforts clauses and M&A among exit paths gaining traction
The rollout of new dual-listing reform measures has sent shockwaves through Korea's capital markets. With the regulation's scope now extending beyond subsidiaries spun off through physical divisions to cover newly established or acquired subsidiaries and affiliates in vertical control relationships, companies are being forced to revisit M&A structures, pre-IPO investment arrangements and financial investor exit strategies that were built around the assumption of a subsidiary listing.
Attorneys Shin Hee-kang, Jung Hee-seok, Ha Young-jin and Hyun Ye-rim of Bae, Kim & Lee's IPO team sat down Wednesday to discuss how the dual-listing regulation is reshaping Korea's capital markets and what strategies companies are adopting in response.
Subsidiary IPOs evolve into 'governance transactions' — overseas listings also in regulators' sights
The Bae, Kim & Lee IPO team said subsidiary IPOs have evolved into a form of "governance transaction." A subsidiary listing is no longer a standalone deal judged solely on the subsidiary's own listing eligibility — it has become a higher-order transaction that must account for the interests of the parent company's general shareholders and the capital allocation of the entire group.
It is still too early to conclude that subsidiary IPOs are structurally declining, given that the reform measures only recently took effect, but the changes felt on the ground are significant. Companies are visibly revisiting the timelines and structures of planned subsidiary listings and working to flesh out shareholder protection measures for parent company investors.
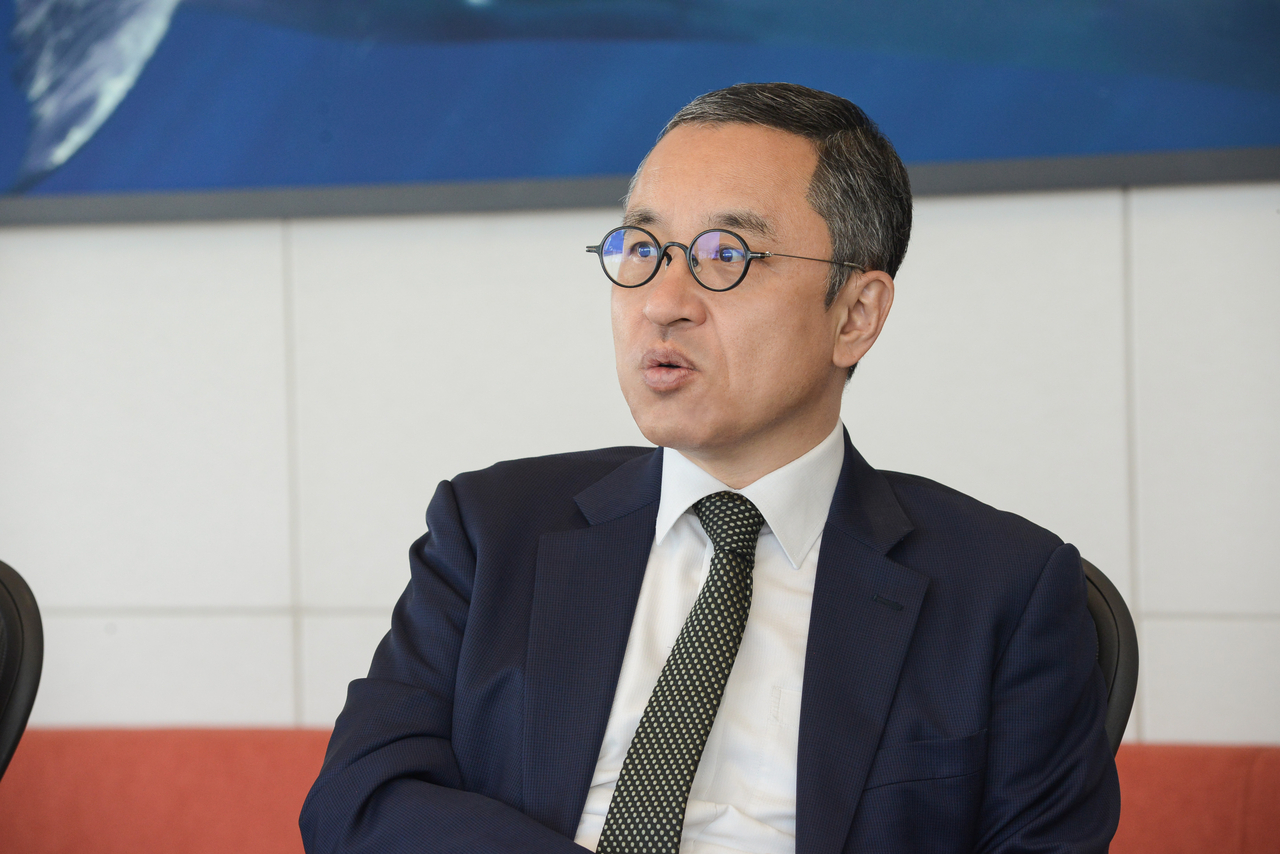
Shin, who leads the IPO team, said the dual-listing regulation "is operating less as an outright ban on subsidiary IPOs and more as a requirement to rigorously demonstrate the necessity of the listing and the adequacy of shareholder protections." He added that because parent company boards must now assess the listing's impact on shareholders and carry out shareholder communications, "changes to deal structure, preparation timelines and costs ahead of filing a preliminary review application have become unavoidable."
Even listing an overseas subsidiary on a foreign exchange does not allow a company to fully escape the dual-listing regulatory net. The five core obligations — including a shareholder impact assessment and the preparation of protection measures — apply in principle regardless of where the listing takes place. While Korea Exchange cannot directly block an overseas listing, a domestically listed parent company that fails to fulfill those obligations could face sanctions.
Hyun said overseas listings "come with a range of challenges, including meeting local listing requirements and schedules — governance included — filing registration statements, coordinating disclosure timing between Korea and the overseas market, and managing foreign exchange and tax risks." She added that while an overseas listing can be chosen as an alternative to a domestic one, "it cannot be seen as an easy option for circumventing the regulation."
Pre-IPO contract terms shift — from guaranteed IPO to multiple exit paths
The dual-listing regulation is also having a significant impact on investment contract terms across the capital market ecosystem. Pre-IPO investment contracts have traditionally required an IPO to be pursued and completed by a set date, with put options or return guarantees triggered in the event of failure.
But as subsidiary listings have become harder to secure through the will of the company or its controlling shareholder alone, issuers and those seeking investment are increasingly inclined to adjust terms — replacing a firm commitment to complete an IPO by a specific date with a "best efforts" obligation. Moreover, because a failed IPO may now fall outside the control of the issuer or its largest shareholder, companies have little choice but to consider a broader range of exit paths, including attracting strategic investors, secondary transactions and M&A.
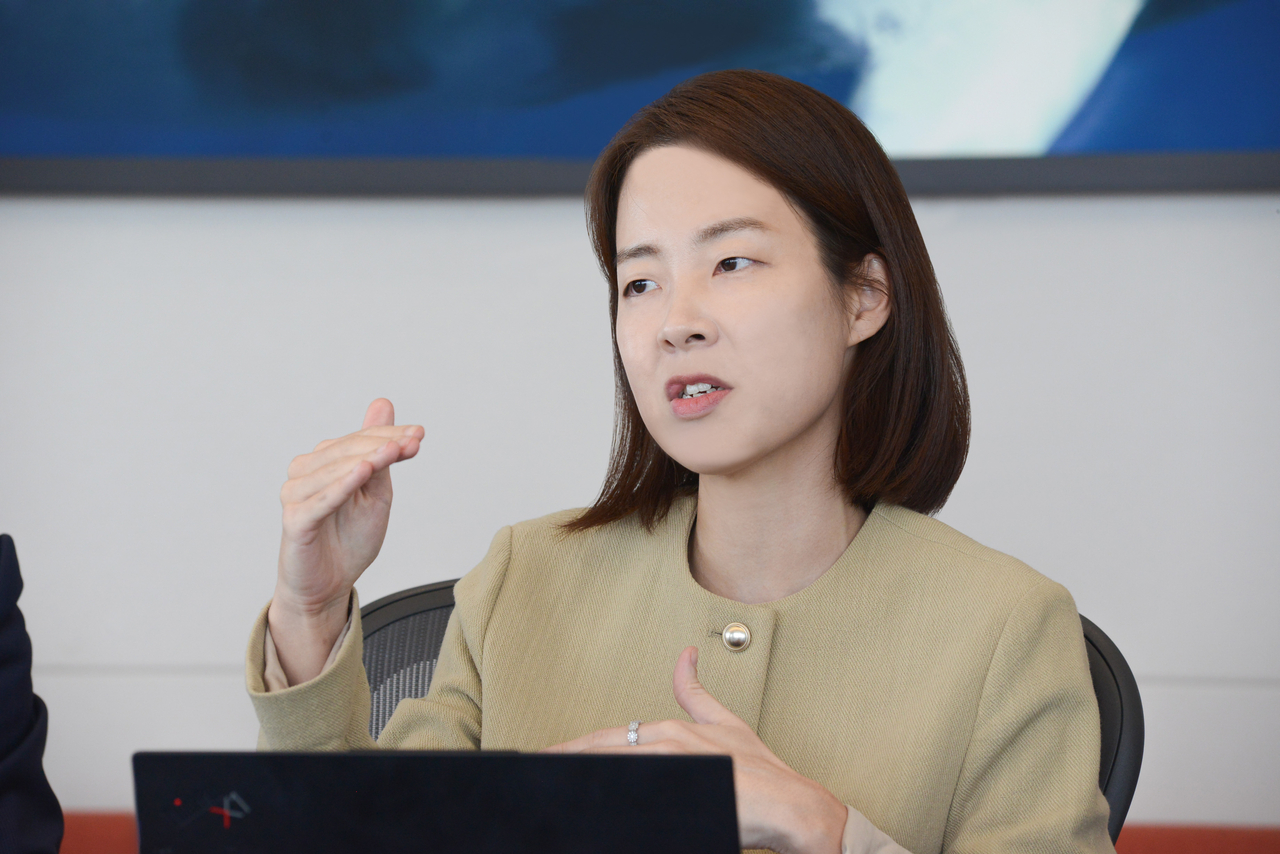
Ha said future pre-IPO contracts will involve "more nuanced negotiations that set different trigger conditions and thresholds for investor protections such as put options, depending on whether an IPO failure stems from the controlling shareholder or the company itself, or from market conditions and regulatory changes."
For deals already signed, there is a growing trend of revisiting IPO deadline extensions and existing put option and return guarantee clauses. When an IPO looks uncertain, parties are discussing realistic alternatives such as third-party sales, reinforcing drag-along rights and providing early liquidity on a portion of the stake.
Ha said a structure in which a put option is triggered upon failure to complete an IPO "can become an unexpected financial risk for the parent company under the dual-listing regulatory environment," adding that "when exercising an option, one must comprehensively examine the parent company's financial soundness, whether the board has breached its duty of loyalty, and the fairness of the transaction terms."
US biotech Ingenia lists on Kosdaq — attracting 'pure foreign companies' amid tighter rules
As the bar for subsidiary listings rises, domestic securities firms and Korea Exchange have greater incentive to identify new listing candidates. Independent startups, family-owned businesses and foreign companies — entities less affected by dual-listing concerns — are emerging as prime targets.
Against this backdrop, the recent Kosdaq listing of US biotech company Ingenia Therapeutics is drawing attention. Ingenia Therapeutics completed its Kosdaq listing on Aug. 18, and what sets it apart is that it is a "purely foreign company" — independently founded and grown in Boston — not an overseas subsidiary or affiliate of a Korean-listed company.
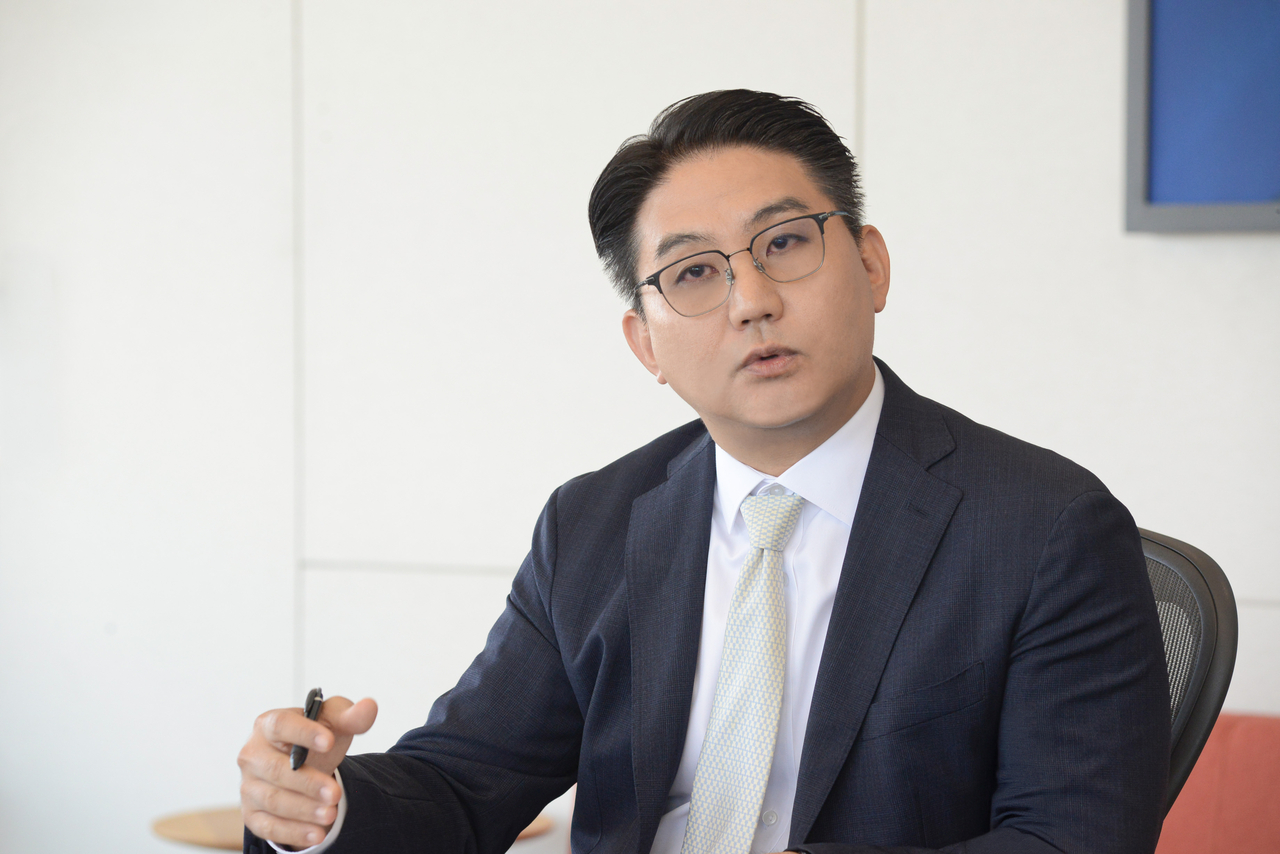
Jung said Ingenia Therapeutics "was a case where domestic investors had a high level of familiarity, because while the company's business and R&D are centered in the United States, its core technology originated from KAIST and the Institute for Basic Science." He said the team focused on "harmonizing the governance and disclosure framework of the Delaware corporation with Korea Exchange standards, and on designing from scratch a Korean depositary receipt issuance and settlement structure based on US shares."
The Bae, Kim & Lee IPO team agreed that improving the predictability of Korea Exchange's review process is the single most important factor in activating foreign company listings in Korea. They particularly advised adopting a "functional equivalence" perspective — recognizing that even when a foreign jurisdiction's rules differ in form from Korea's, they should be accepted if they offer the same substantive level of investor protection.
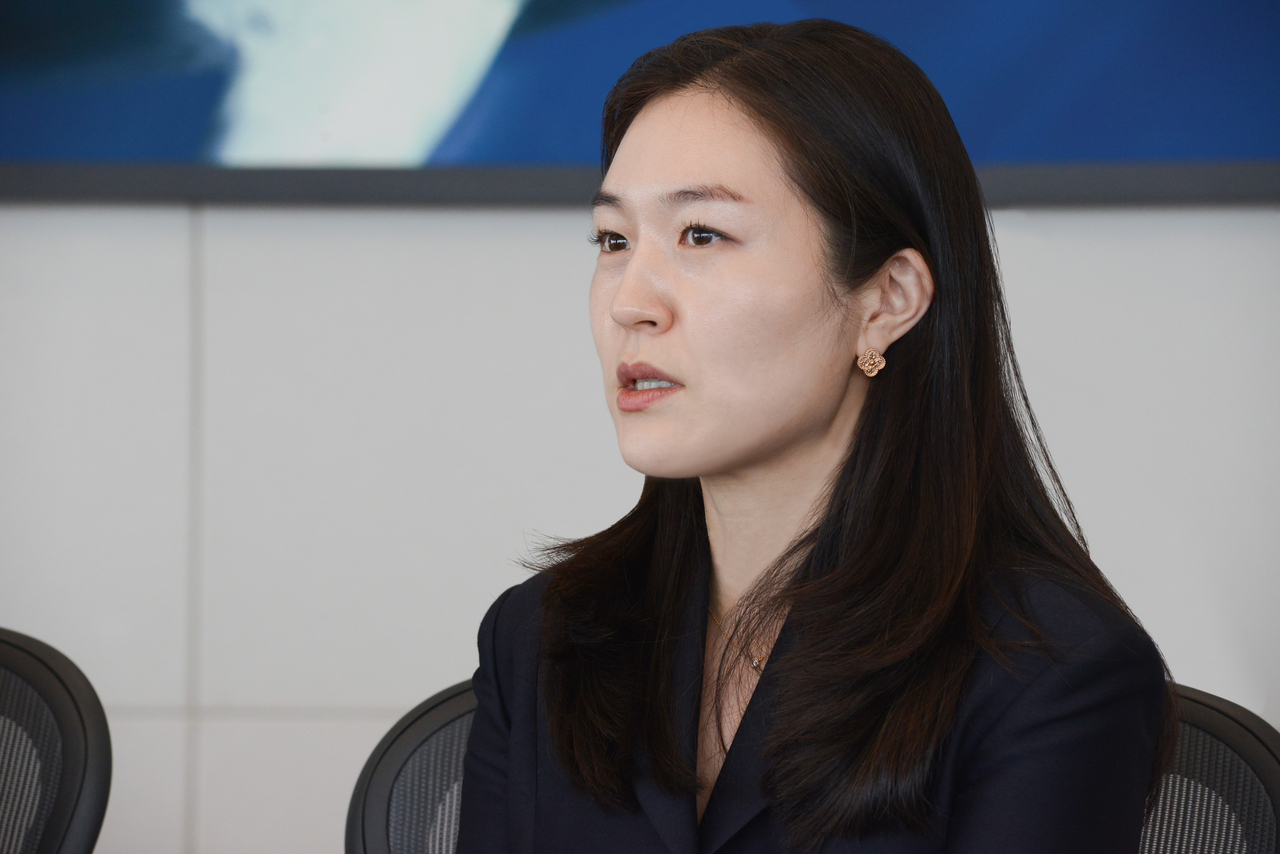
Hyun said the real difficulty in listing foreign companies "often arises not from satisfying any single regulation, but from having to redesign articles of incorporation, board structures, committees and stock option schemes — already built to comply with the home country's law — to fit Korea's system in a way that Korea Exchange and Korean investors can understand."
Jung said "there is a need to present predictable standards that allow companies to make maximum use of the governance and institutional frameworks already established under their home country's law, as long as there are no gaps in investor protection," adding that "an approach centered on the substantive level of investor protection, rather than formal identity, is important for attracting foreign companies."
Shin noted that the Singapore Exchange recently introduced a system allowing companies listing on NASDAQ to simultaneously list in Singapore using only the disclosure documents filed for the NASDAQ listing and subsequent filings — without additional document reviews or disclosures. He said Hong Kong Exchange is also working to attract Korean companies under more relaxed standards, and that "domestic exchanges likewise need a more flexible shift in thinking to keep pace with these trends."
A higher bar for IPOs — 'integrated strategy is the core competitive edge'
Experts said the nature of IPO advisory work itself is changing since the regulation took effect. A piecemeal approach of simply checking listing requirement checklists has clear limitations. They said "integrated advisory" — covering not only the economic rationale for a listing and governance design, but also the alignment of interests between financial investors and general shareholders, as well as alternative financing and M&A structures in case an IPO falls through — has become essential.
Shin said "it is increasingly important not only to review the legal and regulatory requirements of an IPO, but also to persuasively explain, through objective data and appropriate procedures, why the transaction is reasonable for both the company and its general shareholders." He added that the team works with corporate law and capital markets groups "to analyze individual precedents and applicable standards, and to help companies fulfill their shareholder protection obligations in accordance with proper procedures as they pursue a listing."
Meanwhile, Bae, Kim & Lee's IPO team advises on the full range of initial public offerings — Kospi and Kosdaq listings for domestic and foreign companies, technology-exception listings, foreign company listings in Korea and pre-IPO investments. The team has advised on major IPOs including Samsung Biologics, LG Energy Solution and Big Hit Entertainment, and most recently handled the listings of K bank and Ingenia Therapeutics.
The team has bolstered its IPO and capital markets advisory capabilities by bringing in foreign attorney Kim Hak-kyun, a former standing commissioner of the Financial Services Commission and former chairman of the Kosdaq Market Committee; senior specialist Kim Ki-yong, formerly head of the technology-listing review team at Korea Exchange's Kosdaq division; adviser Ra Seong-chae, a former executive director at Korea Exchange's Kospi division; and adviser Kim Kyung-kyu, formerly a department head at Korea Exchange's market surveillance division.
an@heraldcorp.com
park.jiyeong@heraldcorp.com