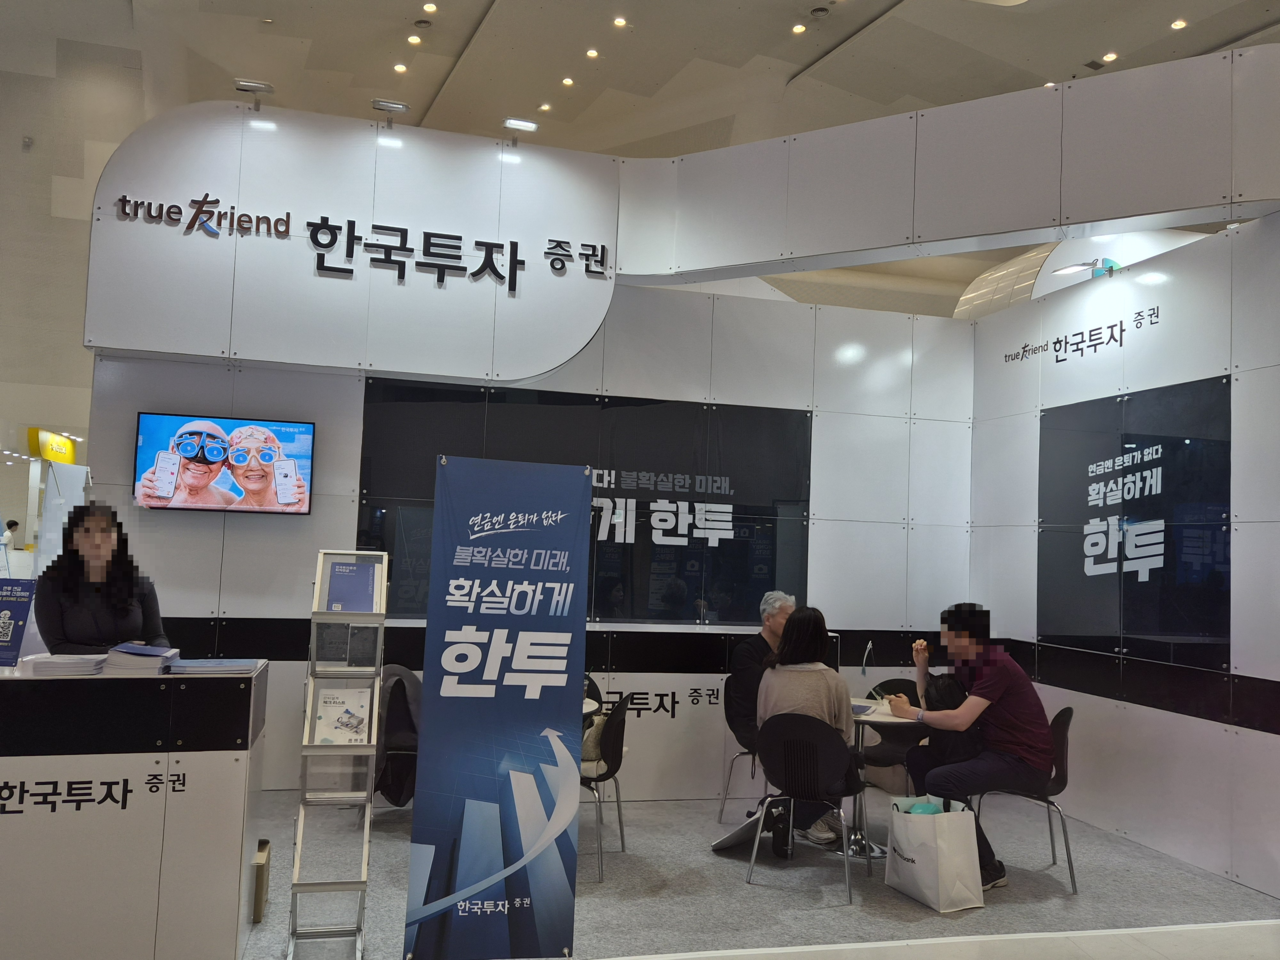
Korea Investment & Securities retirement pension booth
Step-by-step explanations of DB and DC plans
"I opened a pension savings fund account for tax benefits and have been investing in it every year — but is that different from a retirement pension? And what exactly is an IRP?"
The question came from A, a seven-year office worker, as she flipped through a pamphlet at the Korea Investment & Securities booth at the Herald Money Festa 2026, held Saturday at Dongdaemun Design Plaza in Jung-gu, Seoul. Retirement pensions had long been a topic she was curious about whenever friends brought them up, but the system always seemed too complicated to approach. Beyond the seminar rooms buzzing with debate over the 2026 and 2027 share and real estate market outlook, visitors were asking earnest questions about life in retirement 20 or 30 years down the road.
Korea Investment & Securities set up a retirement pension consultation booth that day. Under the slogan "Pensions never retire — trust Korea Investment," staff walked visitors through the basics of the retirement pension system, the differences between defined-benefit (DB) and defined-contribution (DC) plans, individual retirement pension (IRP) accounts, and the range of products available within retirement pension accounts — all tailored to each visitor's age and investment experience. The focus was on helping people move beyond short-term investing and start planning for a stable retirement decades away.
Visitors spanned a wide range of ages. Job-seekers in their 20s, people in their 30s and 40s juggling asset-building and child-rearing, and workers in their 50s with about 15 years left until retirement all stopped by. Retirement pensions are no longer a financial product only those nearing the end of their careers pay attention to — they are increasingly becoming a wealth-management tool for younger investors seeking tax benefits and long-term returns.
"I opened a pension savings fund account for tax purposes, but after hearing the explanation of DC and IRP plans today, I'm thinking about investing directly," A said. "It was great to be able to ask all the questions I'd had on my mind."
The shift in how people think about retirement pensions is also showing up in actual fund flows. According to the Financial Supervisory Service, as of end-2025, DB plan reserves stood at 228.9 trillion won ($168 billion), accounting for 45.7 percent of the total, while DC plans and corporate IRPs held 141.6 trillion won (28.2 percent) and individual IRPs 130.9 trillion won (26.1 percent) — meaning DC and IRP accounts together held more than half. Individual IRP reserves have grown more than 30 percent annually, rising from 75.6 trillion won in 2023 to 98.7 trillion won in 2024 before surpassing 100 trillion won last year.
Under a DB plan, the company manages the retirement pension assets, while under a DC plan the account holder decides how to invest. Individual IRP accounts also allow the holder to choose their financial institution and products. As the retirement pension market shifts toward DC and IRP plans, individual investors' judgment and financial firms' product and asset management capabilities are becoming increasingly important.
Korea Investment & Securities has been expanding its product lineup to keep pace with this shift. As of late August, the firm's retirement pension accounts offered access to 1,021 ETFs and 24 listed real estate investment trusts. In September, it also introduced 10- and 20-year individual investor government bonds available for purchase through DC and IRP accounts.
B, a worker in his 50s who visited the booth that day, was also wrestling with how to manage his retirement pension. Already enrolled in a DC plan, he sought advice on how to structure his portfolio.
"I had built my portfolio around dividend funds, but returns had been falling lately and I wasn't sure what to do," B said. "It was helpful to be able to ask someone from the financial industry directly about the types of products available through DC and IRP accounts."
As the retirement pension market enters what industry insiders are calling an "era of active management," competition among securities firms is intensifying. Korea Investment & Securities' retirement pension reserves grew from 15.81 trillion won in 2024 to 20.09 trillion won in 2025.
park.jiyeong@heraldcorp.com