Acquisitions of Yulgok and PTC mark push into manufacturing
'Connected investment' strategy links portfolio insights to new deals
Credit unit VAC to spin off as independent firm in January
Some buy, some sell, and others reload for the next deal. Even in the same M&A market, private equity firms pursue different strategies and deliver different results. House Review takes a close look at where major firms invested this year, what returns they achieved, and where they are looking next. [Editor's note]
For VIG Partners, 2026 has been a year of expansion. The firm moved beyond its traditional strength in mid-cap buyouts of consumer goods and services companies, broadening its investment reach into manufacturing sectors such as aviation components and semiconductors, as well as health technology. Rather than charging blindly into unfamiliar industries, VIG Partners has pursued a deliberate strategy of extending insights gained from managing existing portfolio companies into adjacent sectors.
The firm has also accelerated efforts to build its credit business into a new growth pillar. VIG Alternative Credit (VAC) is being spun off as an independent management firm, and VIG Partners is already preparing to raise its next fund on the back of the investment and exit track record established by its existing blind funds. With credit now joining buyouts as a second engine of growth, the firm is positioning itself for a broader platform.
Fund V levels up through manufacturing bets and connected investments
The fifth blind fund has been at the center of VIG Partners' new investment activity, and its portfolio profile has sharpened considerably as industrial-sector deals have taken shape. The firm has focused on identifying hidden gems — companies with irreplaceable technology within their industry value chains that stand to benefit from structural growth in their end markets over the long term. Once the Yulgok deal closes, the fifth fund's deployment rate will reach approximately 80 percent.
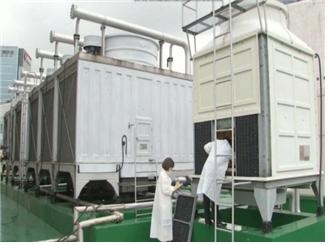
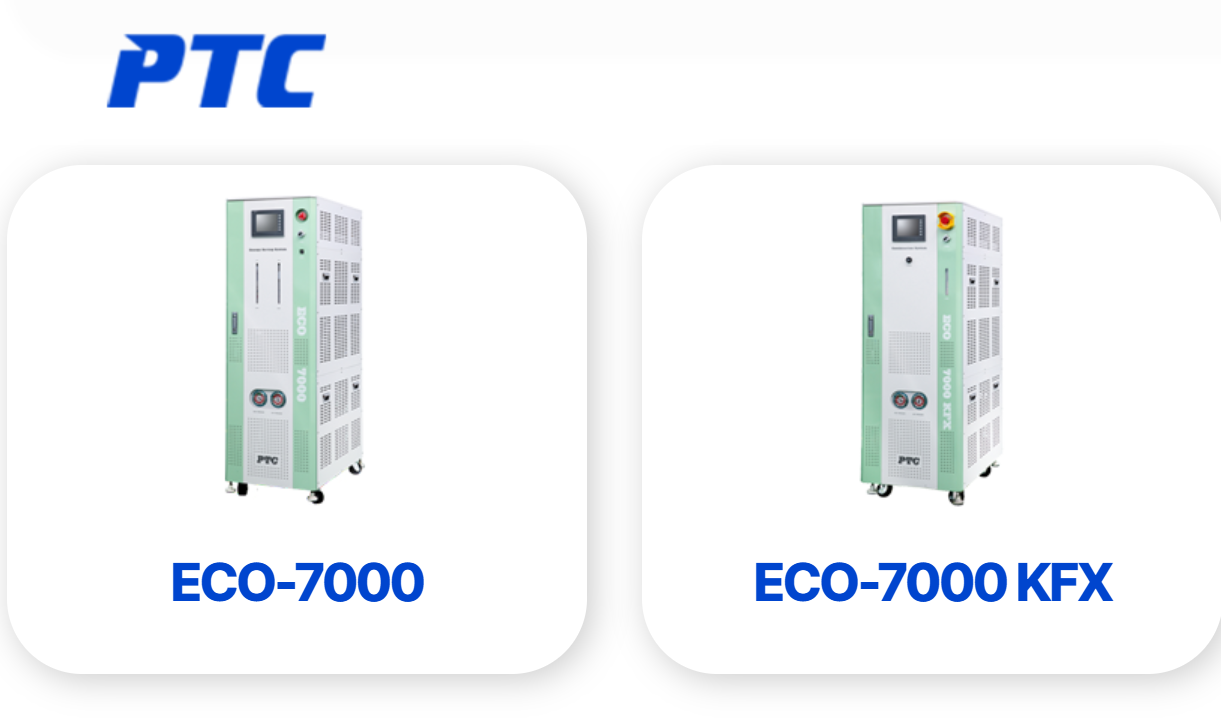
The standout investment of the fifth fund is PTC, a deal that closed in June. PTC manufactures process equipment — including chillers, scrubbers and chambers — used in semiconductor production. SK hynix is among its key customers, and PTC supplies essential equipment installed alongside semiconductor factories as they are built.
This marks VIG Partners' first investment in a semiconductor materials, components and equipment company. The firm identified the company's core competitive strengths as its accumulated technical expertise in specific manufacturing processes, its market share within customer facilities, and the structural growth potential of its end markets.
Earnings have grown rapidly. PTC's sales nearly doubled from 46.9 billion won ($34.5 million) in 2024 to 85.4 billion won in 2025. With domestic semiconductor companies continuing to expand their capital expenditure, PTC has significant room to grow over the medium to long term — and beyond benefiting from increased investment by domestic customers, its potential entry into overseas markets is also drawing attention.
Another defining feature of VIG Partners' investment approach this year has been what the firm calls "connected investment" — a strategy of channeling insights gained from managing existing portfolio companies directly into new deals.
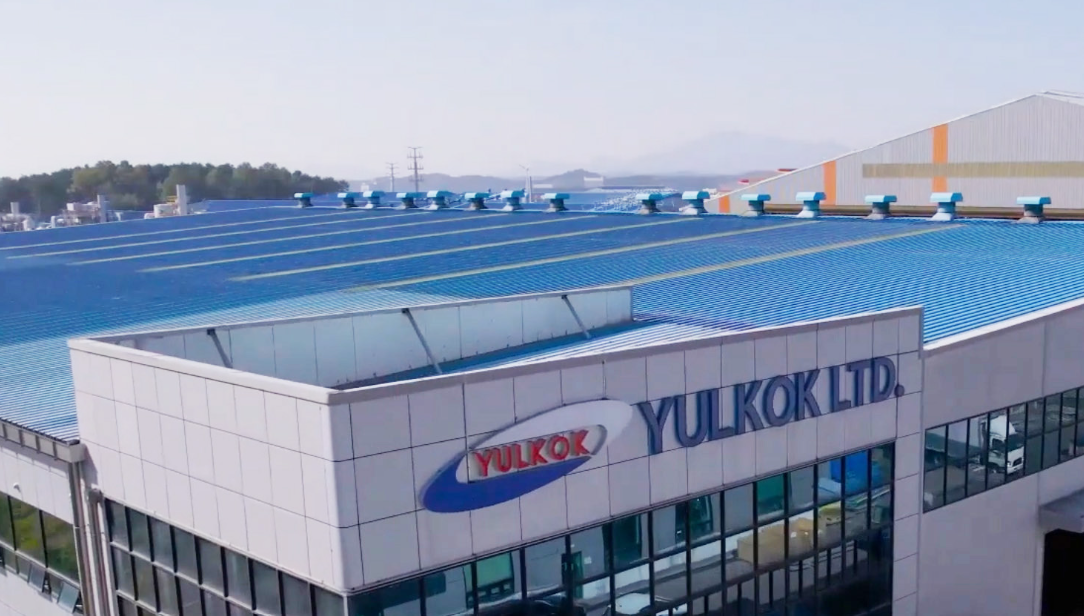
The clearest example is the acquisition of Yulgok, an aircraft components manufacturer. VIG Partners beat out a competitive field that included Stic Investments, Anchor Equity Partners and KCGI to be named the preferred bidder, and signed a share purchase agreement in August. The transaction is expected to close as early as the end of this month.
The aviation industry has moved beyond its post-COVID-19 recovery and into what many describe as a supercycle. VIG Partners concluded that the surge in passenger demand and the reshaping of global supply chains would open a new era for domestic aviation component manufacturers. The firm drew on the industry knowledge it accumulated while operating Eastar Jet and extended that understanding into the adjacent value chain of aircraft parts manufacturing.
The same logic of connected investment has played out in the medical aesthetics space. VIG Partners acquired aesthetic medical device maker Viol in 2025 and carved out LG Chem's aesthetics division to launch Liv Science, establishing a meaningful foothold in the medical aesthetics market.
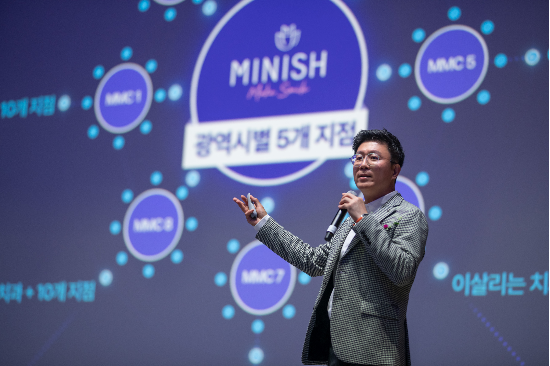
This year, the firm extended that market insight into health technology. In May, VIG Partners invested 30 billion won in Minish Technology, a dental restoration solutions company, acquiring a roughly 20 percent stake. Minish Technology was founded in 2021 by Kang Jeong-ho, a dentist-turned-entrepreneur. The company supplies dental restoration solutions to clinics at home and abroad, distinguishing itself by offering not just treatment services but also the related materials, equipment, IT systems and integrated solutions.
Credit unit to go independent in January, powering VIG's second engine
As VIG Partners has widened its investment scope, it has also reorganized internally. The most notable development is the planned independence of the credit division. The firm has been preparing the VAC spinoff since the start of the year, with the unit set to operate as a separate legal entity from January. Han Young-hwan, a managing director who joined VIG Partners in 2021 after spending a decade at Goldman Sachs building expertise in special situations investing, is expected to lead the new firm.
VAC's third blind fund, which closed at 300 billion won last year, has already deployed 60 to 70 percent of its capital. A 60 billion won corporate dormitory loan in Songdo — the fund's inaugural investment — was repaid early in September, 18 months after it was made. Following its independence, VAC plans to immediately begin raising a new blind fund, leveraging its established investment and exit track record to pursue meaningful growth as a standalone manager.
VAC was built by VIG Partners to specialize in credit investment strategies. Unlike buyouts, which center on acquiring management control, VAC targets mid-range returns of around 15 percent by deploying capital through direct corporate lending, mezzanine financing and structured finance. The unit captures investment opportunities that fall outside the scope of buyout strategies, diversifying the firm's investment pipeline, and serves as a safety net by providing capital in complex structures that conventional banks cannot accommodate.
There have also been notable changes within VIG Partners itself. Yoo Shin-hyuk, a managing director who joined last month, will work alongside Chief Executive Shin Chang-hoon on investment review and portfolio management to strengthen the firm's buyout capabilities. Yoo brings more than 18 years of M&A experience across Deutsche Bank, Valtec, Roland Berger and Boston Consulting Group. Kang Sung-wook, who joined at the same time as general manager, will support the firm's overseas expansion and cross-border M&A activity.
Three managing directors — Kang Ki-jeong, Kim Gyu-myeong and Bae Jong-hyun — have also taken on greater responsibilities. Each has been with VIG Partners for more than a decade and has grown alongside the firm. Together with Shin and Yoo, they lead investment sourcing and portfolio company management, reinforcing the cohesion of the investment team.
Bonchon, PNC Labs sold as Fund III nears full wind-down
The third blind fund, formed in 2017, is in the final stages of being wound down. Earlier exits included Starvision in 2022, Foodist in 2024 and Freed Life in 2025.
This year, VIG Partners completed an approximately eight-year investment cycle by selling global fried chicken franchise Bonchon International to Thailand's Minor Group. Minor Group had already been operating Bonchon in Thailand as a business partner and acquired the stakes held by both VIG Partners and the founding shareholders.
Mask pack sheet maker PNC Labs was sold to Young Chemical. Footwear materials company Yooyoung Industrial signed a share purchase agreement with Pocom Partners, and VIG Partners is in discussions with Hyundai Glovis over the sale of AutoPlus, the operator of used-car retail brand Ribbon Car.
park.jiyeong@heraldcorp.com