Crude secured for September–October; short-term supply stable
Prolonged disruption could hit Middle East supply from December
Shift to non-Middle East crude raises freight and procurement costs
Domestic supply priority may squeeze export volumes
Fixed refining margins point to improved third-quarter earnings
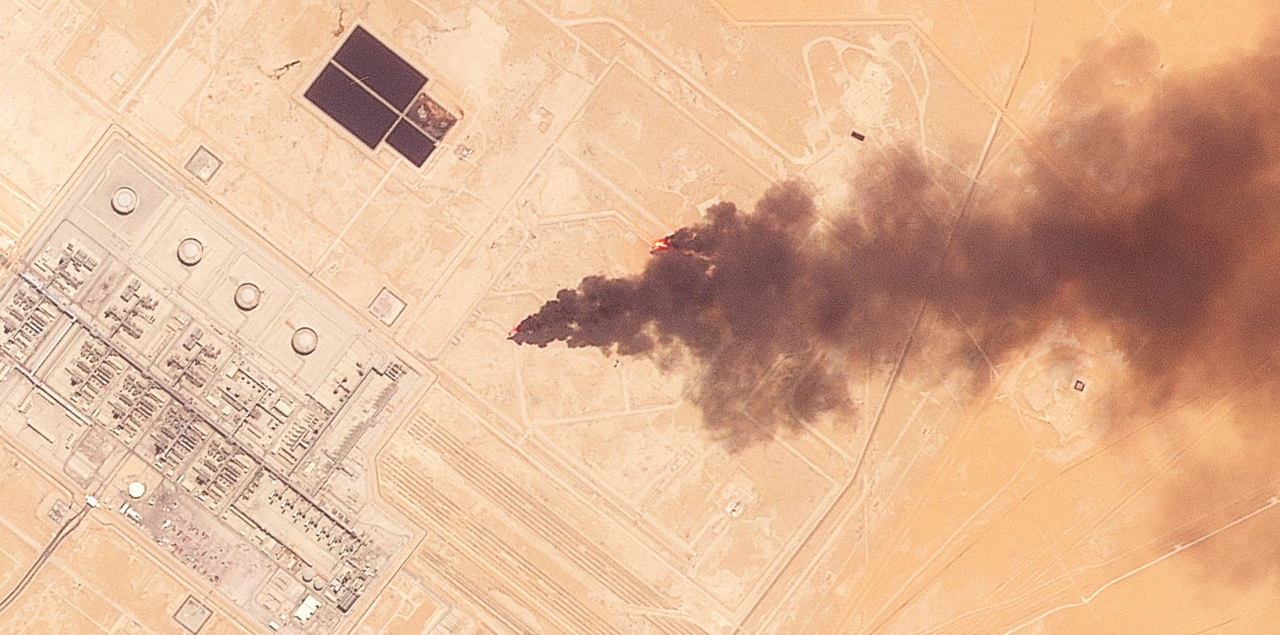
South Korea's refining industry is on alert over potential crude supply disruptions stemming from the Middle East, with uncertainty growing after Saudi Arabia's East-West pipeline was shut down. While refiners say domestic petroleum product supplies face no immediate threat, a prolonged disruption could put export volumes and profitability at risk.
Domestic refiners have secured a substantial portion of their crude import volumes through next month, industry officials said Thursday. The Ministry of Trade, Industry and Energy said at an industry review meeting Monday that crude secured for September and October stood at more than 90 percent of the same period last year. Because contracted and loaded cargoes are arriving in sequence, the near-term impact on supply is expected to be limited.
The concern begins this winter. Since crude purchases are typically decided months in advance, refiners say they can manage supply through November with existing volumes — but the outlook beyond that depends on whether alternative crude can be secured. "About 80 to 90 percent of import volumes through November have been locked in, but if the situation drags on, serious concerns could emerge from December," an industry official said.
Prolonged disruption would drive up freight and procurement costs
The impact on individual refiners will vary depending on their reliance on Middle Eastern crude. Some companies source more than half their crude from non-Middle East suppliers — one refiner already procures over 50 percent of its crude outside the region, and another does not import Saudi crude on a monthly basis, limiting their direct exposure to the pipeline outage. However, a prolonged disruption would raise freight and procurement costs as refiners shift to alternatives such as North American crude. Crude from North America takes about 40 days to reach South Korea — roughly twice the transit time for Middle Eastern shipments, which typically ranges from 20 to 25 days.
The industry believes domestic supply can be managed through a combination of alternative crude procurement and the government's strategic reserve swap program. The government resumed its reserve swap scheme on Aug. 24, under which refiners can borrow from state stockpiles in advance and repay the volumes once their actual crude shipments arrive. One official described the mechanism as "a safety valve that can help close supply gaps."
However, if crude supplies tighten, refiners would need to prioritize domestic gasoline and diesel supply, potentially leaving less crude available for export. Given the different pricing structures for domestic and export sales, a reduction in crude availability could affect not only production but also export earnings and overall profitability.
'Maintaining export volumes and margins is the key challenge'
Domestic petroleum product prices are subject to a price ceiling, making it difficult for refiners to fully pass on rising international crude costs to consumers. Export products, by contrast, are priced on international markets. With refining margins — the spread between crude prices and refined product prices — currently elevated, refiners can capture relatively higher margins through exports. A drop in crude supply that reduces output would therefore shrink those profit opportunities.
If the disruption proves short-lived, refiners can sustain domestic supply through reserve swaps and alternative procurement. But a prolonged crisis would change the calculus. "The challenge is how to keep domestic supply stable while at the same time maintaining export volumes and profitability," one industry official said.
Meanwhile, strong refining margins and rising oil prices are expected to lift third-quarter earnings above second-quarter levels, as higher crude prices boost the value of existing inventories and generate inventory-related gains. According to data compiled by Korea National Oil Corp.'s Petronet, the average price of Brent crude in September stood at $100.4 per barrel, while West Texas Intermediate averaged $96.3. Wednesday's closing futures prices for both Brent and WTI reached their highest levels in about four months, since May 19.
However, this is largely an accounting effect that could reverse into inventory valuation losses if oil prices fall again. The fourth quarter carries significant uncertainty: a price decline could trigger such losses, and a shift from Middle Eastern to non-Middle Eastern crude — at higher purchase prices and freight costs — could weigh on profitability.
keg@heraldcorp.com