Debt restructuring, rate-cut request rights, fixed-rate loan expansion under review
Vulnerable borrowers to be identified early; job and welfare linkages to be strengthened
The Financial Supervisory Service is treating the sharp rise in interest rates as the primary risk facing financial markets and is reviewing measures to ease the burden on borrowers. The regulator is examining options including debt restructuring, activation of the right to request rate cuts, and expansion of fixed-rate loans, while also planning to strengthen early identification of borrowers at risk of delinquency and support for vulnerable groups seeking financial recovery.
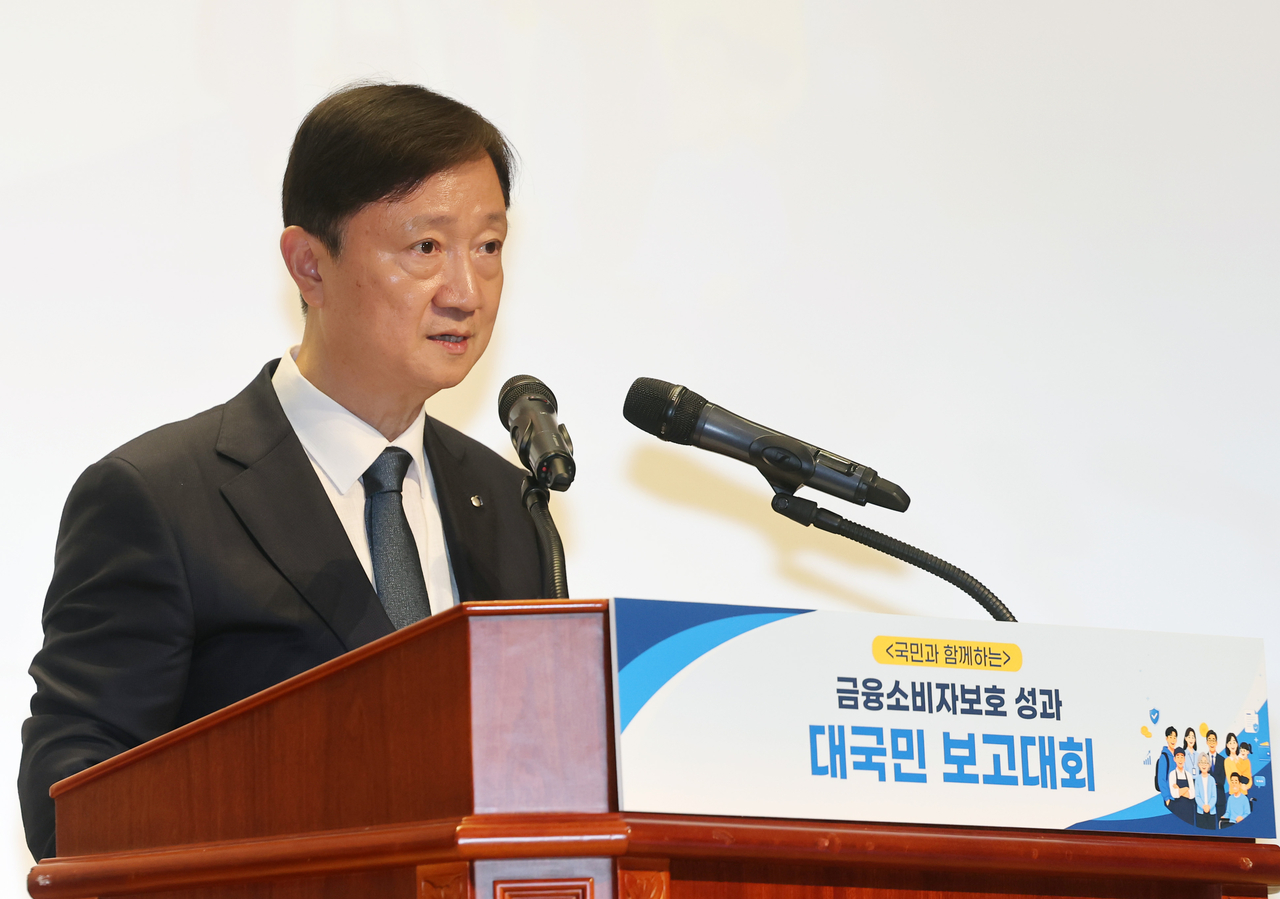
Lee Se-hun, senior deputy governor of the Financial Supervisory Service, said at a pre-briefing Thursday ahead of a public reporting event on consumer financial protection held at the FSS headquarters in Yeouido, Seoul, that the regulator views interest rates as "the most immediate risk factor in the current financial market." He added that "as the pace of rate increases is steep, we are paying close attention not only to market stability but also to the growing financial burden on ordinary citizens."
Lee said the FSS is "considering measures such as debt restructuring, activation of the right to request rate cuts, and expansion of fixed-rate loans to reduce the interest burden on consumers."
The FSS also plans to broaden its support for vulnerable groups beyond simple credit supply to encompass recovery assistance. To reduce the rate at which borrowers who have undergone debt restructuring fall back into delinquency, the regulator will strengthen linkages between financial support and employment and welfare programs.
"Support for vulnerable groups must not stop at simple loans or expanded financial access," Lee said. "To reduce re-delinquency after debt restructuring, it is important to link financial assistance with employment and social welfare programs so that people can achieve genuine recovery and restore their repayment capacity."
The FSS will also upgrade its system for early detection of at-risk borrowers through information sharing with related agencies. The regulator plans to standardize criteria for identifying borrowers at risk of delinquency and for providing debt restructuring support, and will build an "inclusive finance integrated monitoring system" that consolidates and analyzes credit loan and policy guarantee data for mid- and low-credit borrowers to identify areas of insufficient credit supply.
Financial support for vulnerable groups is also being expanded. The supply target for the Saeheuimang Holssi loan program this year is 5.1 trillion won ($3.73 billion), up 20.1 percent from last year. As of July, 3.1 trillion won had already been disbursed. In the secondary financial sector, a living-expense stabilization loan was launched for mid- and low-credit borrowers, and improvements to the interest rate calculation method drove rate reductions of up to 1.24 percentage points.
On the faster pace of household lending growth this year compared with last year, the FSS said it does not yet consider the increase excessive.
"While household loan growth this year has been faster than last year in some respects, we also need to consider the demand for investment funds driven by the stock market rally in the first half of the year, as well as the base effect from the aggressive household loan management last year," Lee said. "Given our management target of 3 percent growth this year, we do not currently judge the increase to be excessive, but we will closely monitor the situation through December and examine whether any corrective action is needed."
The FSS said that while financial soundness and consumer protection may conflict in the short term, consumer trust can ultimately translate into institutional soundness over the long run.
"Soundness and consumer protection may be at odds in the short term, but in the long run, the soundness of a financial institution ultimately depends on how solid a customer base it builds and how much trust it earns," Lee said.
rim@heraldcorp.com