Shortest closures last year were 30–31 days; this year a borrower shut down in 3
All top 5 closures within 30 days tied to 'innovation growth promotion fund'
Screening under scrutiny as declining foot traffic, weak trade areas were detectable before loans
A small-business owner who received 60 million won ($43,300) in government policy funds shut down operations just three days after the loan was disbursed, it has been confirmed. The Small Enterprise and Market Service, known as SEMAS, recorded the reason for closure as "closure and relaunch due to declining franchise popularity and falling customer foot traffic." The case comes a year after a national audit revealed instances of businesses closing 30 to 31 days after receiving policy loans — this time, the gap between disbursement and closure has shrunk to three days.
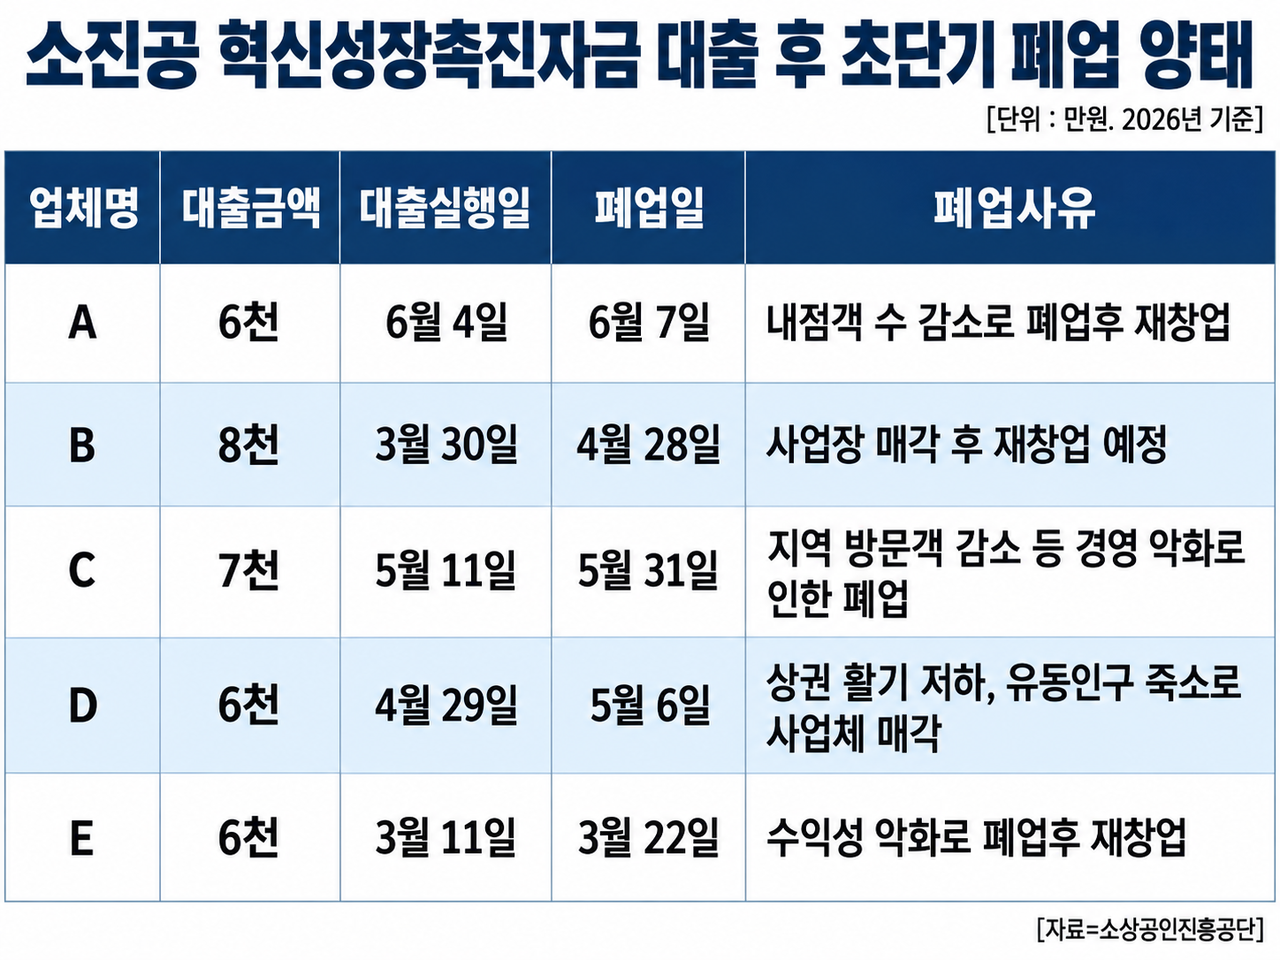
According to data submitted by SEMAS to the office of Rep. Heo Seong-mu of the Democratic Party of Korea, a member of the National Assembly's Trade, Industry, Energy, SMEs and Startups Committee, a business identified as Company A received 60 million won under the "innovation growth promotion fund" on June 4. It closed just three days later, on June 7. The stated reason was "closure and relaunch due to declining franchise popularity and falling customer foot traffic."
The business owner shut down before the policy funds could have any meaningful effect on operations. Notably, the conditions SEMAS cited — declining franchise popularity and falling foot traffic — are the kind of deteriorating business environment that typically accumulates over time. Questions remain about how thoroughly the loan screening process examined the business's declining sales, changes in the surrounding trade area, or any plans to close and reopen elsewhere.
The timeline has grown even shorter compared with the ultra-short closure cases disclosed last year. Data released by Rep. Heo's office in October last year showed that among the 100 businesses that closed most quickly after receiving direct policy loans between 2021 and July 2025, the closure period ranged from 30 to 31 days, with an average of 30.5 days. At the time, a lodging and food-service business in North Gyeongsang Province closed within a month of receiving 40 million won in smart funds, while a manufacturer in Gyeonggi Province shut down 30 days after borrowing 70 million won in small manufacturer specialized funds.
The ultra-short closure cases separately tallied by SEMAS this year were far more extreme. All five of the largest borrowers among businesses that closed within 30 days had received the innovation growth promotion fund, and all shut down between 3 and 29 days after receiving their loans.
Company B, which borrowed 80 million won, closed on April 28 — 29 days after its loan was disbursed on March 30. The stated reason was "planned relaunch after selling the business premises." Company C closed 20 days after borrowing 70 million won, citing "deteriorating management due to declining regional visitors."
Company D, which also received 60 million won, shut down just seven days after disbursement. Its stated reason was "sale of the business due to deteriorating management caused by a weakening trade area and declining foot traffic." Company E, another 60 million won borrower, closed after 11 days, citing "closure and relaunch due to declining franchise popularity, rising unit costs and worsening profitability."
Three of the five ultra-short closure cases cited "relaunch" or "planned relaunch" as a reason, while two involved the sale of the business or its premises. The pattern suggests that policy funds were disbursed not only to businesses that abruptly failed, but also to owners already in the process of winding down one operation to start another or to sell.
Ultra-short closures are not isolated incidents. According to SEMAS, a total of 2,910 small-business owners who received policy loans closed within one month between 2022 and July this year, with total loan amounts reaching 60.88 billion won. The annual breakdown was 1,187 cases in 2022, 465 in 2023, 472 in 2024 and 467 in 2025. Through July this year, 319 businesses had already closed within a month of receiving policy funds, with 9.2 billion won ($6.65 million) disbursed to those businesses this year alone.
The core problem lies in loan screening and post-disbursement oversight. SEMAS said it verifies whether applicants have suspended or closed operations through National Tax Service inquiries during the application, screening and agreement process, and conducts on-site inspections to assess business viability and industry conditions. For small-business owners with weak credit, on-site inspections are mandatory if certain criteria are met, it added.
However, the suspension and closure checks SEMAS described are designed to screen out businesses that have already closed — they cannot detect owners who plan to shut down within days of receiving a loan. On-site inspections also have inherent limits: if a borrower has ulterior motives, inspectors may find little to flag.
SEMAS said it runs a separate post-management process for ultra-short closure cases. "When a business closes within 90 days of loan disbursement, we review how the funds were used and take follow-up action based on the findings," it said.
Gaps in policy loan screening were flagged last year as well. SEMAS detected 23 cases of malicious or suspected closures involving falsified documents in 2025, with related loan amounts totaling 540 million won. Some cases were referred for investigation. SEMAS said at the time that it verifies closure status during the loan application and agreement process.
Rep. Heo was sharply critical. "Extending funds to a business that closes three days later and reopens elsewhere is shoddy screening dressed up as rapid disbursement," he said. "Opportunities that should reach the countless hardworking small-business owners across the country are being squandered through poor management."
Heo called for systemic reform. "To prevent policy funds from being poured into a bottomless pit, a pre-screening system linking public and financial data must be built immediately," he said. "For marginal small-business owners with little hope of recovery, the policy paradigm must shift from piling on debt to an 'exit package' — a pathway through closure, debt restructuring and restart support."
hong@heraldcorp.com
snsd@heraldcorp.com