Pre-Chuseok currency issuance reaches 3.94 trillion won, down 17% from last year
Shorter holiday weighs on figure, but issuance still exceeds 2024 level
Banknote balances rise 9.1% last year, led by 50,000-won notes
Demand shifts from payments to gifts, storage and asset holding
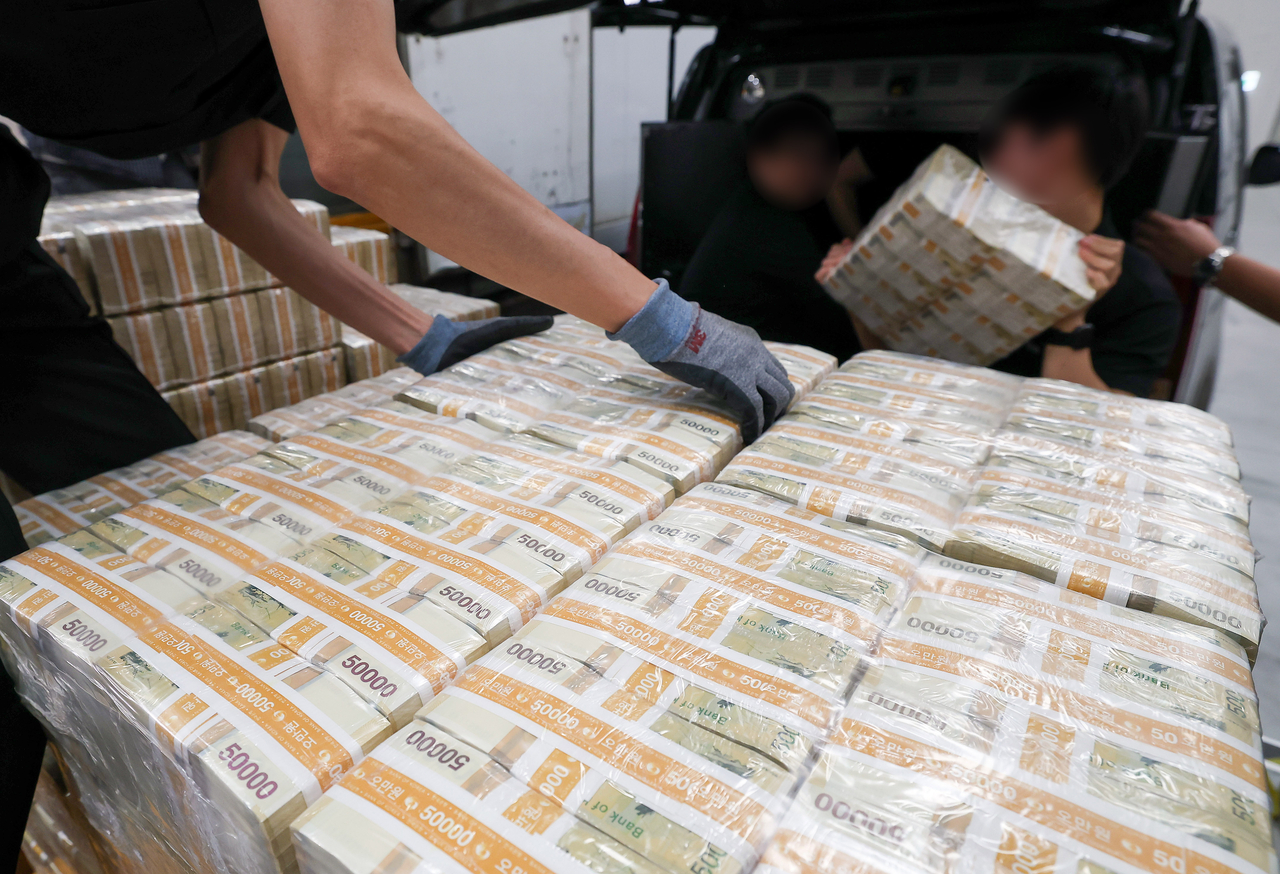
Cash is rapidly losing ground as a payment method, but holiday gift money remains a stubborn exception. The Bank of Korea supplied nearly 4 trillion won ($2.94 billion) to financial institutions ahead of this year's Chuseok holiday. The figure fell 17% from last year due to a shorter holiday period, but it still exceeded the amount issued for the 2024 Chuseok, which had one more day off.
The Bank of Korea said Wednesday that currency issuance to financial institutions over the 10 business days before Chuseok — from Sept. 10 through Wednesday — reached 3.94 trillion won. That was down 808.3 billion won, or 17%, from the 4.75 trillion won issued in the same period last year.
The central bank said the decline was "mainly attributable to a reduction in the Chuseok holiday period." Last year's Chuseok stretch ran for seven days in total, extended by National Foundation Day on Oct. 3 and Hangul Day on Oct. 9. This year's Chuseok holiday spans four days.
Compared with 2024, however, the picture looked different. Although this year's holiday is one day shorter than the five-day break in 2024, issuance still came in 29.8 billion won, or 0.8%, above the 3.91 trillion won recorded that year.
Net issuance — the gross figure minus the amount returned to the Bank of Korea by financial institutions — stood at 3.65 trillion won this year. That was down 792.3 billion won, or 17.9%, from 4.44 trillion won in the same period last year, and down 101.6 billion won, or 2.7%, from 3.75 trillion won in 2024.
The rapid shift toward a cashless society has steadily eroded the role of physical currency as a payment tool. Even so, the volume of notes in circulation for holiday gift-giving, storage and other non-payment purposes has continued to grow.
According to the Bank of Korea, the total outstanding currency in circulation at the end of last year reached 210.7 trillion won, up 9.1% from 193.15 trillion won at the end of 2024. That was the fastest annual increase since 2021, when the balance surged 13.6% as liquidity expanded during the COVID-19 pandemic. Outstanding currency refers to the total amount of money supplied to the public — calculated as the amount issued by the central bank minus the amount recovered.
Within the overall currency stock, banknotes and coins are moving in opposite directions.
The outstanding balance of 50,000-won notes at the end of last year stood at 189.54 trillion won, accounting for 90% of total currency in circulation. The balance and share of the 50,000-won note have consistently grown since the denomination was first issued in 2009. The balance of 10,000-won notes edged down from 15.76 trillion won at the end of 2024 to 15.63 trillion won at the end of last year, with its share of total currency shrinking from 8.2% to 7.4%. The balance of 5,000-won notes rose slightly over the same period, from 1.45 trillion won to 1.49 trillion won.
Coins, by contrast, have been declining. The outstanding balance of coins at the end of last year fell to 2.22 trillion won, marking six consecutive years of decline since 2019, when the balance stood at 2.38 trillion won.
"The role of cash as a payment instrument is gradually disappearing," a financial industry official said. "Coins are generally used for payments, so it is natural that issuance is also trending downward." The official added that banknotes serve functions beyond payments — including as a store of value and for gift-giving and safekeeping — and tend to grow alongside the broader economy and financial markets.
Analysts expect the pace of growth in outstanding currency to slow for some time. The Bank of Korea has raised its benchmark interest rate twice in consecutive meetings and signaled that it intends to maintain a tightening stance over an extended period. Higher interest rates generally increase the opportunity cost of holding cash and boost demand for deposits, leading to more currency flowing back to the central bank.
kimstar@heraldcorp.com