Gap of up to 7.2 million won a year on 400 million won mortgage
Refinancing rates exceed new-loan rates at 11 of 16 banks for mortgages, 10 for personal loans
Analysts call for closer scrutiny of whether loan-switching system delivers real savings
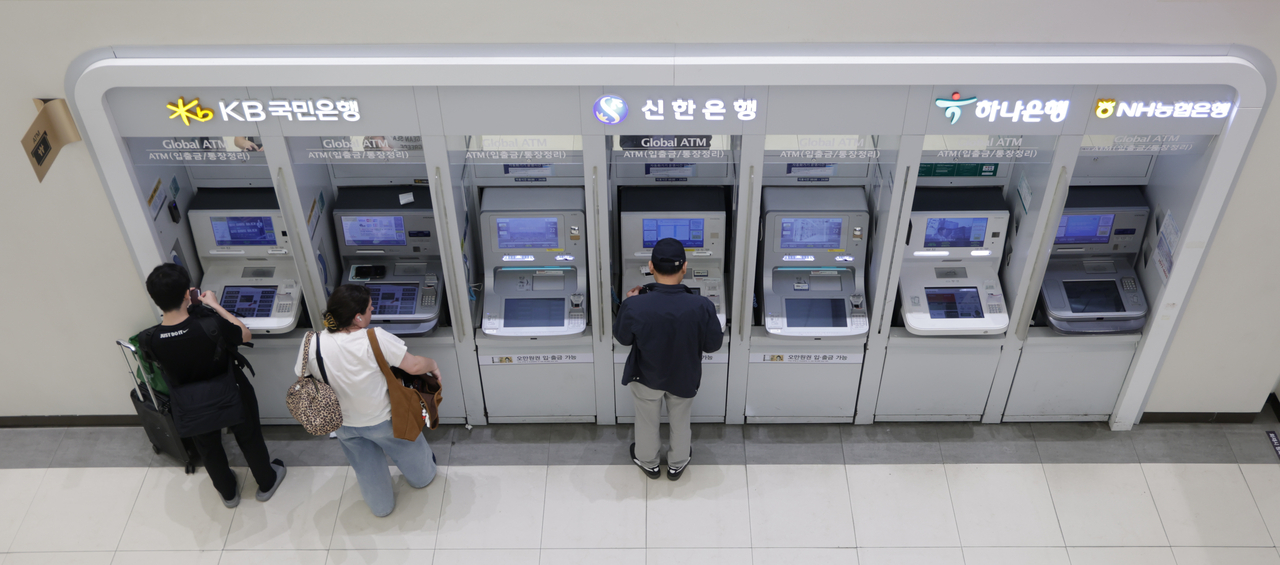
For a borrower repaying a 400 million won ($294,000) mortgage over 30 years on a fixed equal-installment schedule, the difference between an annual rate of 4.84 percent and one of 7.17 percent works out to roughly 600,000 won a month — or nearly 7.2 million won a year.
Those two figures are the average rates iM Bank applied in July to ordinary new mortgages and to refinanced mortgages, respectively, based on a straightforward calculation. Actual rates vary with a borrower's credit profile and collateral value, but the gap is difficult to explain to anyone who switched lenders specifically to cut their interest burden.
Across the 16 banks that offer mortgage refinancing, 11 charged higher average rates on refinanced loans than on new ones — a phenomenon critics are calling a "rate inversion." The same pattern held for personal loans, where 10 of the 16 banks posted higher average rates on refinancing than on new lending. Observers say the inversion undermines the very purpose of the loan-switching system, which was designed to help borrowers find cheaper financing by moving between lenders.
The data, submitted to People Power Party lawmaker Park Sung-hoon of the National Assembly's Political Affairs Committee by the Financial Supervisory Service, showed that as of July, 11 of the 16 banks offering mortgage refinancing charged higher average rates on those loans than on ordinary new mortgages.
The widest gap was at iM Bank, where the average refinancing rate on mortgages stood at 7.17 percent per year — 2.33 percentage points above the bank's average new-mortgage rate of 4.84 percent.
Jeonbuk Bank, Jeju Bank, Busan Bank and Suhyup Bank also posted refinancing rates 0.39 to 0.53 percentage points above their new-loan rates.
Among the five major banks, rate inversions were confirmed at Hana Bank, Woori Bank and NH NongHyup Bank. Woori Bank's average refinancing mortgage rate was 4.71 percent, compared with 4.34 percent for new mortgages — a gap of 0.37 percentage points. NH NongHyup Bank and Hana Bank followed, with refinancing rates running 0.24 and 0.18 percentage points higher, respectively.
The picture was similar for personal loans. Of the 16 banks surveyed, 10 posted higher average refinancing rates than new-loan rates.
Gwangju Bank had the largest gap at 1.29 percentage points, followed by Toss Bank and Busan Bank, each at 1.22 percentage points.
Among the five major banks, four — all except Woori Bank — charged more for refinanced personal loans than for new ones. Hana Bank stood out: its average new personal loan rate was 4.70 percent per year, while its refinancing rate reached 5.72 percent, a difference of 1.02 percentage points.
The loan-switching system was introduced to help borrowers reduce their interest burden by moving to a lender offering a lower rate. According to the Financial Services Commission, about 420,000 people had used the online loan-switching service through the end of 2025. The total volume of loans transferred came to 22.8 trillion won, with average rates falling by 1.44 percentage points and annual interest savings per borrower averaging 1.69 million won.
However, as interest rates have risen and banks have tightened their lending standards, the experience for borrowers seeking to switch has changed. Even when a borrower shops around, the rate they are actually offered can differ significantly from the advertised minimum, because lenders reassess income, credit scores, collateral value, debt service ratio, salary transfers and card-use conditions from scratch.
Mortgage refinancing is also subject to a six-month waiting period after the original loan is taken out, and borrowers cannot increase the loan amount when switching. The repayment term must also stay within the remaining term of the existing loan. When early-repayment fees on the old loan and the costs of taking out a new one are factored in, even a modestly lower rate may not translate into meaningful savings.
The options are particularly limited for borrowers who need to reduce their monthly repayments even slightly. A borrower who tries to switch because their current rate is too burdensome may find that the new loan comes with a lower credit limit or a higher rate, leaving them with no choice but to stay with their existing loan. Even after comparing terms across multiple banks, it can be hard to judge which product is genuinely better, given that credit conditions and preferential rate criteria differ from lender to lender.
The average rates in the data alone do not necessarily mean banks are systematically pricing refinancing loans higher than new ones. The two groups of borrowers differ in credit quality, collateral value, loan maturity and product mix. If refinancing borrowers tend to carry higher risk on average, that would push up the average rate.
Even so, observers say a more precise analysis — comparing rates among borrowers with similar credit and collateral profiles — is needed to determine whether the loan-switching system is actually reducing borrowers' interest costs. They add that the rate-setting structures at individual banks and whether preferential rates apply to refinancing-specific products also need to be examined.
"Since the system was designed to let borrowers switch to a cheaper rate, consumers have every reason to question whether it is working," Park said. "The financial authorities should look into the causes of the rate inversion and assess how much the system is actually reducing borrowers' interest burden."
attom@heraldcorp.com