298.3 billion won lent to affiliated lenders at 2.3–4.6% annual interest
Franchisees charged 12–18% annual interest on startup loans
Special relationships and loan terms omitted from disclosure documents
Myeongyundang, the operator of the galbi franchise Myeongyun Jinsa Galbi, has been hit with a fine of 14.87 billion won ($11 million) and referred to prosecutors after regulators found it had funneled hundreds of billions of won in low-interest loans to lending companies owned by the chairman's family while charging franchisees far higher rates on startup financing.
The Korea Fair Trade Commission said Monday it plans to impose a provisional surcharge of 10.47 billion won for unfair support practices and 4.4 billion won for violations of the Franchise Business Act — totaling 14.87 billion won — along with a corrective order and referrals to prosecutors against Myeongyundang and its Chairman Lee Jong-geun.
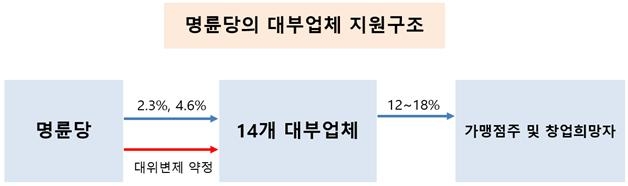
According to the Fair Trade Commission, Myeongyundang lent funds from December 2021 through April this year to 14 lending companies in which Lee and his relatives held most of the shares, at annual interest rates of 2.3 or 4.6 percent. The cumulative amount lent over that period was 298.3 billion won.
Myeongyundang had originally operated an "angel investment agreement" from 2018 through late 2021, providing franchisees with interest-free startup loans to support franchise expansion.
In the second half of 2021, however, a deteriorating restaurant industry environment made it difficult for franchisees to repay their loans, raising concerns about bad debts at Penple, the affiliate that administered the program. The company concluded it could no longer sustain interest-free lending and decided to establish separate lending companies that would charge franchisees interest.
Myeongyundang went on to set up a total of 14 lending companies between 2021 and 2024. Demand surged particularly in 2023, when the company was pushing a remodeling initiative for existing Myeongyun Jinsa Galbi locations — driving up capital needs among existing franchisees — while a recovery in the restaurant sector also drew more prospective franchisees seeking startup funds. Ten of the 14 lending companies were established that year alone.
The commission's probe found that all 14 companies were established under Lee's direction. Lee personally decided key matters in Myeongyundang's lending process and was involved in the overall management of the lending companies. Most of the companies had no dedicated on-site staff; their representatives were current or former employees of Myeongyundang or Penple, and they operated out of shared office spaces of little more than 3.3 square meters — just enough to meet the minimum registration requirements under the Moneylending Business Act.
Myeongyundang extended credit lines of 10 billion to 15 billion won to each company, allowing them to draw and repay funds freely. It also signed subrogation agreements under which Myeongyundang would repay principal on behalf of a lending company if a franchisee defaulted, effectively eliminating most of the credit risk the lending companies would otherwise have faced.
The commission calculated a normal market interest rate of 8.73 to 13 percent per year — the most favorable rate available to the lending companies, based on responses from 27 financial institutions. On that basis, the interest the lending companies should have paid came to about 31.6 billion won, but the interest they actually paid was limited to about 9.9 billion won.
The commission determined that the 14 companies collectively saved about 21.7 billion won in interest costs, giving them a significantly more favorable competitive position than rival lenders.
The combined loan receivables of the 14 lending companies ranked 27th among all 8,203 registered lending businesses as of 2025; individually, each ranked between 149th and 392nd. The commission concluded that companies that would otherwise have struggled to enter the market due to insufficient independent funding capacity were able to establish themselves in the lending sector through Myeongyundang's support, strengthening their market position.
The information provided to prospective franchisees also drew scrutiny. Despite channeling startup funds to prospective franchisees through affiliated companies, Myeongyundang listed "not applicable" in the "credit provision and brokerage details" section of its franchise disclosure document.
The commission found that Myeongyundang's franchise agreements and the lending companies' loan contracts were linked throughout the entire process — from initial startup consultations through the signing of franchise and loan agreements.
Myeongyundang employees handled all practical work from loan consultations through contract signing. Loan interest rates were set regardless of a franchisee's repayment capacity: 12 percent per year for remodeling loans, 15 percent for new franchisees, and 18 percent for new loans issued after late 2024.
Franchisees who took out loans repaid principal and interest through a commodity-repayment arrangement: when purchasing raw meat — a mandatory supply item from Myeongyundang — they paid a fixed additional amount per box on top of the purchase price. The average monthly repayment per franchisee came to about 36,000 won ($27), which Myeongyundang settled at the end of each month and transferred to the relevant lending company.
Myeongyundang did not, however, disclose to prospective franchisees the loan terms, the relationship between the franchise and loan agreements, or the connection between the lending companies and Myeongyundang itself — nor were any of these details included in the franchise disclosure document. The commission said this information was material to a prospective franchisee's decision on whether to sign a franchise agreement and how to finance the cost of opening a location.
The commission said the action was significant because it "detected and sanctioned conduct in which a franchisor pursued private gain by establishing lending companies owned by the owner's family and providing them with low-interest funds in the course of supporting franchisee startup financing." It added that it had made clear "that loan terms linked to a franchise agreement, and the fact that a lending company is a specially related company of the franchisor, constitute important information that must be provided to prospective franchisees, as they are decisive to the decision of whether to enter into a contract."
y2k@heraldcorp.com