Tax expert Kim Hye-ri speaks at Herald Money Festa 2026
Tailor inheritance deduction strategy to family structure
Get an appraisal even when no inheritance tax is due — it cuts capital gains later
Spread deposit and savings maturities across different years
Use the 2.5 million won annual overseas stock deduction every year
"Even if you earn the same investment return, your after-tax profit will differ depending on when you realize it and whose account it sits in."
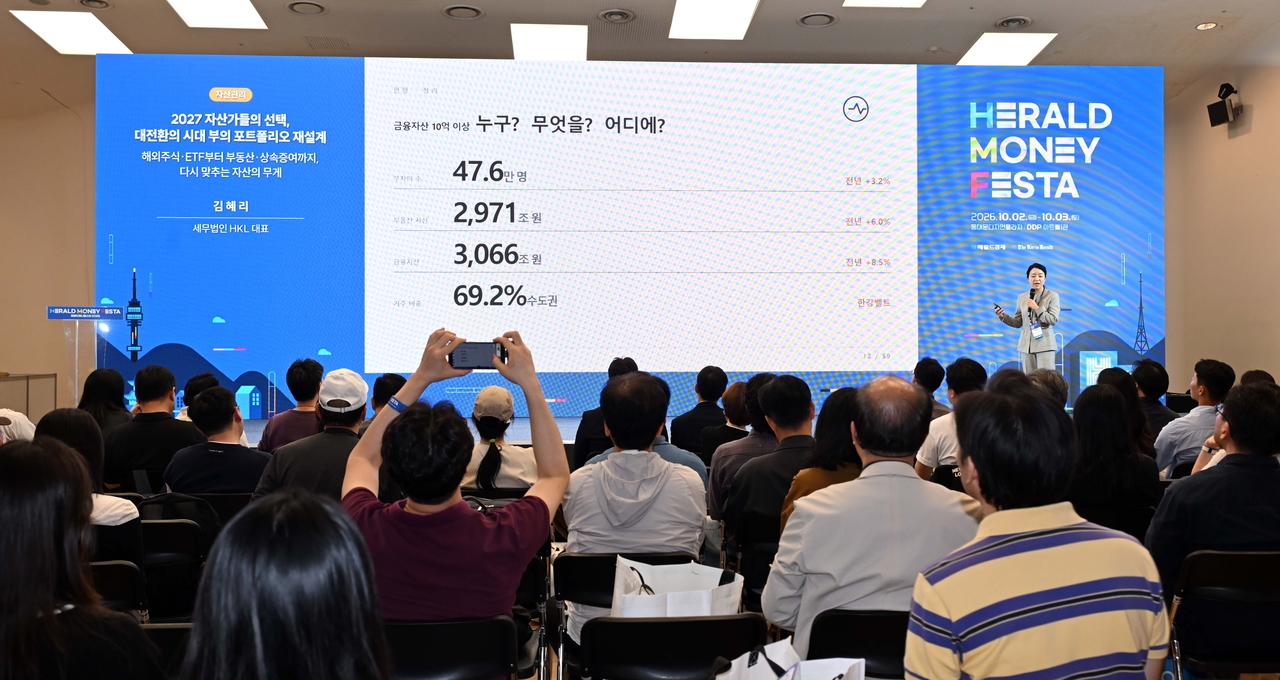
Kim Hye-ri, a former National Tax Service official known by the nickname "NTS Sister" and head of HKL Tax Corporation, made the remarks Saturday at Herald Money Festa 2026, held at the art hall of Dongdaemun Design Plaza (DDP). She said investors must rebalance not only their choice of assets but also the type of income they generate, when they realize it, and how assets are distributed among family members.
In her lecture, Kim laid out an asset redesign strategy linking inheritance and gift planning, financial income, shares and ETFs, and the use of corporate structures. Of late, she noted, wealthy individuals have been raising their target wealth levels and showing a growing preference for financial assets and holding assets under a corporate name.
Kim said the average target wealth among affluent Koreans more than doubled — from 7.5 billion won ($5.52 million) in 2011 to 15.2 billion won last year. As asset sizes grow, she said, the importance of "rebalancing" — restructuring one's asset base to account not only for investment returns but also for the tax burden during holding and transfer — grows with them.
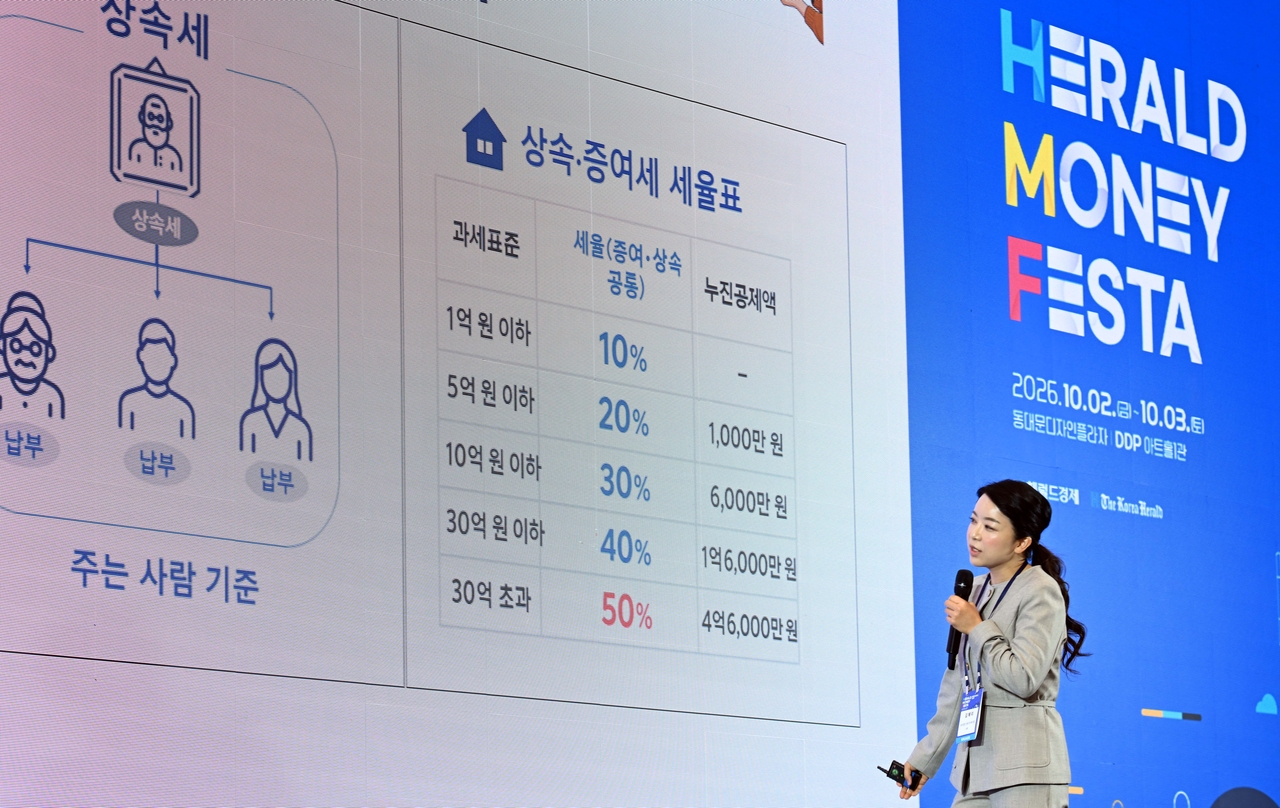
On inheritance, Kim began by challenging the common assumption that "there is no tax on up to 1 billion won." While a tax-free threshold of up to 1 billion won is available when a spouse and children inherit together, deduction limits vary depending on the relationship — spouse, adult child or minor child — making it important to plan transfers by recipient and timing.
She also pointed to a growing number of cases in which children who inherit an apartment are forced to sell it quickly or take out a loan because rising apartment prices have left their parents' estates heavily concentrated in real estate, leaving heirs without enough cash to pay the inheritance tax. "There are cases where heirs cannot sell the inherited apartment when they want to and have to accept a lower price, or end up drawing on their own savings and even taking out loans," Kim said. "You need to prepare not only for the size of the estate but also for the family's composition and the cash needed to pay the tax."
She stressed that even when no inheritance tax is owed, capital gains tax on a future sale of the property must be considered separately. Because the assessed value at the time of inheritance becomes the acquisition cost for a later sale, it is more tax-efficient to obtain an appraisal within six months before or after the date the inheritance opens and report the property at its market value — even if no inheritance tax is due, she said.
On advance gifting, Kim said timing is critical. Even if a parent gifts assets to a child and pays the gift tax, if the parent dies within 10 years the gifted amount can be added back into the inheritance tax calculation. "Rather than rushing to transfer assets after reaching old age, preparing gifts under a long-term plan will maximize the tax-saving effect," she said.
On financial assets, Kim cautioned against letting interest and dividend income pile up in a single year. She said the threshold for comprehensive financial income taxation is based on interest and dividend income — not principal — and that when annual financial income exceeds 20 million won, it must be assessed together with other income, potentially raising the overall tax burden.
The fact that a bank or brokerage has withheld tax at source does not mean all tax obligations are settled, she said. "You should spread the maturities of deposits and savings accounts across different years and explore the use of tax-advantaged accounts such as an ISA," Kim said.
She also introduced intra-family gifting as a way to shift where financial income is attributed. "If you genuinely transfer assets to a spouse, the interest and dividends generated afterward become the spouse's income," Kim said. "So it is worth considering the family's overall asset allocation alongside each member's income level."
On stock investment, Kim stressed that the overall profit and loss across an investor's accounts can differ significantly from what is taxable under the tax code. She described a scenario in which an investor loses 100 million won on domestic shares and gains 50 million won on overseas shares — ending up in the red overall — yet still owes capital gains tax on the overseas profit.
"Offsetting gains and losses is only possible between taxable items," Kim said. "Losses from domestic small-shareholder exchange-traded transactions, which are tax-exempt, cannot be offset against overseas stock gains — so capital gains tax on overseas shares can arise even when the overall investment account is in the red."
She also proposed a strategy of realizing 2.5 million won in overseas stock gains each year. "If you make good use of the 2.5 million won annual capital gains deduction every year, you can reduce your tax bill," she said. "If you realize five years' worth of accumulated gains all at once, you get only one 2.5 million won deduction — but if you sell in stages once a year, you can claim 12.5 million won in deductions over five years."
Kim also suggested breaking investment and tax management into a year-round calendar. From January through March, investors should map out expected returns and profit-realization plans; from April through June, they should file returns on the previous year's transactions. July through September is the time to review cumulative gains and losses and decide which holdings to sell or keep before year-end, while October through December should be used to offset gains against losses and lay out the investment plan for the following year.
She also outlined how high-net-worth individuals and business owners can use corporate structures to their advantage. Holding commercial real estate or financial assets through a corporation, she explained, allows for integrated planning of business expense deductions, asset management and equity-based succession.
However, Kim cautioned against comparing only the corporate-level tax burden in isolation. "When a corporation pays funds to an individual as salary or dividend, personal income tax is triggered, and the costs of setting up the corporation and handling its accounting, bookkeeping and filings must also be borne," she said. "The actual business purpose and operating structure must also be clearly defined."
forest@heraldcorp.com