Woodford argued at Jackson Hole for full transparency
Shin countered in 2002 with the 'public information paradox'
Woodford fired back three years later, stressing the role of expectations
Warsh's silence on guidance lends weight to Shin's position
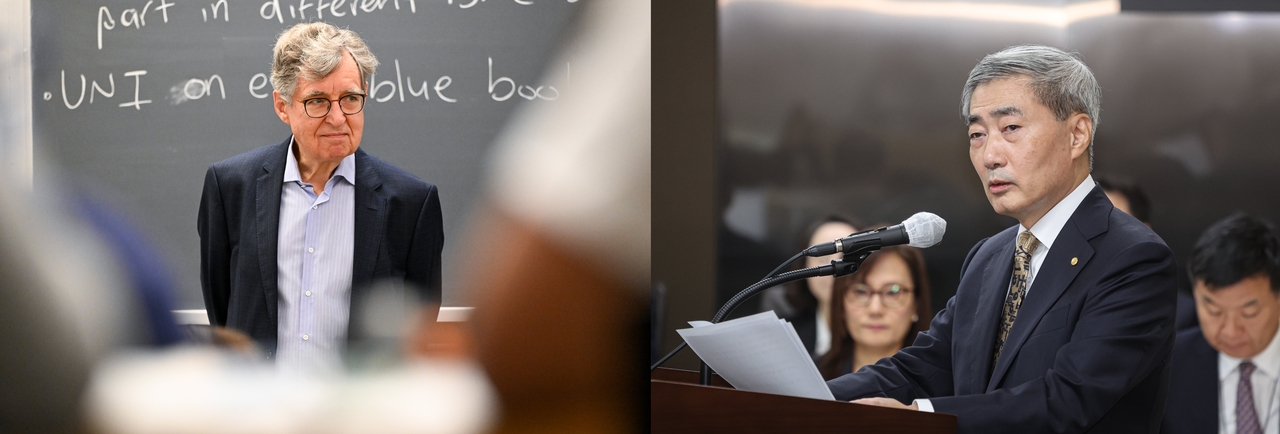
Michael Woodford, the Columbia University professor who won this year's Nobel Prize in economics, and Bank of Korea Governor Shin Hyun-song have been on opposite sides of a theoretical debate over central bank communication for more than two decades. While Woodford laid the intellectual groundwork for forward guidance — the practice of signaling future interest rate intentions — Shin warned of its unintended consequences.
The debate has flared up again in financial circles after Woodford received the Nobel Prize shortly after Federal Reserve Chair Kevin Warsh scrapped forward guidance, a move grounded in Shin's theoretical framework.
Shin's 2002 'public information paradox' and Woodford's Jackson Hole rebuttal
According to financial industry sources, the theoretical clash between Shin and Woodford dates to the early 2000s. In 2002, Shin co-authored a paper titled "The Social Value of Public Information" with Stephen Morris, now a professor at MIT, arguing that excessive reliance on public signals — such as central bank announcements — could amplify herding behavior in markets.
At the time, major central banks were steadily expanding their communications. The Federal Reserve began issuing statements with every rate change in 1994 and started commenting on the future policy direction at each meeting from 1999.
A year before Shin published that paper, Woodford had presented research at the Jackson Hole symposium in 2001 arguing that monetary policy need not surprise markets to be effective — that central banks should instead be transparent about their policy goals and intended measures. Shin's paper the following year amounted to a direct challenge to that view.
In August 2005, Woodford returned to Jackson Hole to present a paper titled "Central Bank Communication and Policy Effectiveness," mounting a frontal rebuttal of Shin's theory.
Woodford defined the core function of a central bank as "the management of expectations." In his view, the only rate a central bank can directly control is the overnight rate, while actual consumption and investment are driven by expectations about future policy. The clearer markets are about a central bank's actions and intentions, he argued, the more powerfully rate decisions shape those expectations — and the greater the policy impact.
Woodford also addressed directly the problem of "over-reliance" that Shin had raised, offering several counterarguments against applying Shin's theory to central bank communication.
The first concerned the accuracy of private information. Woodford cited research showing that for the paradox — whereby releasing more accurate public information worsens overall social outcomes — to hold, individual market participants would need information at least eight times more accurate than the central bank's own disclosures. He pointed to studies showing that Fed staff forecasts are no worse than the best private-sector projections, and argued that central banks are inherently better positioned than markets to anticipate the path of interest rates.
He also noted that markets do not necessarily over-follow central bank announcements — just as a bond trader might sell when others are buying if they believe an asset is overvalued, markets can just as easily under-react to central bank signals as over-react. Finally, Woodford challenged the welfare criterion underpinning Shin's model, arguing that once the costs of divergent private judgments under insufficient public information are factored in, social welfare improves as public information becomes more accurate.
Warsh's silence invokes Shin's theory — while Nobel laureate Woodford warns against 'pulling levers'
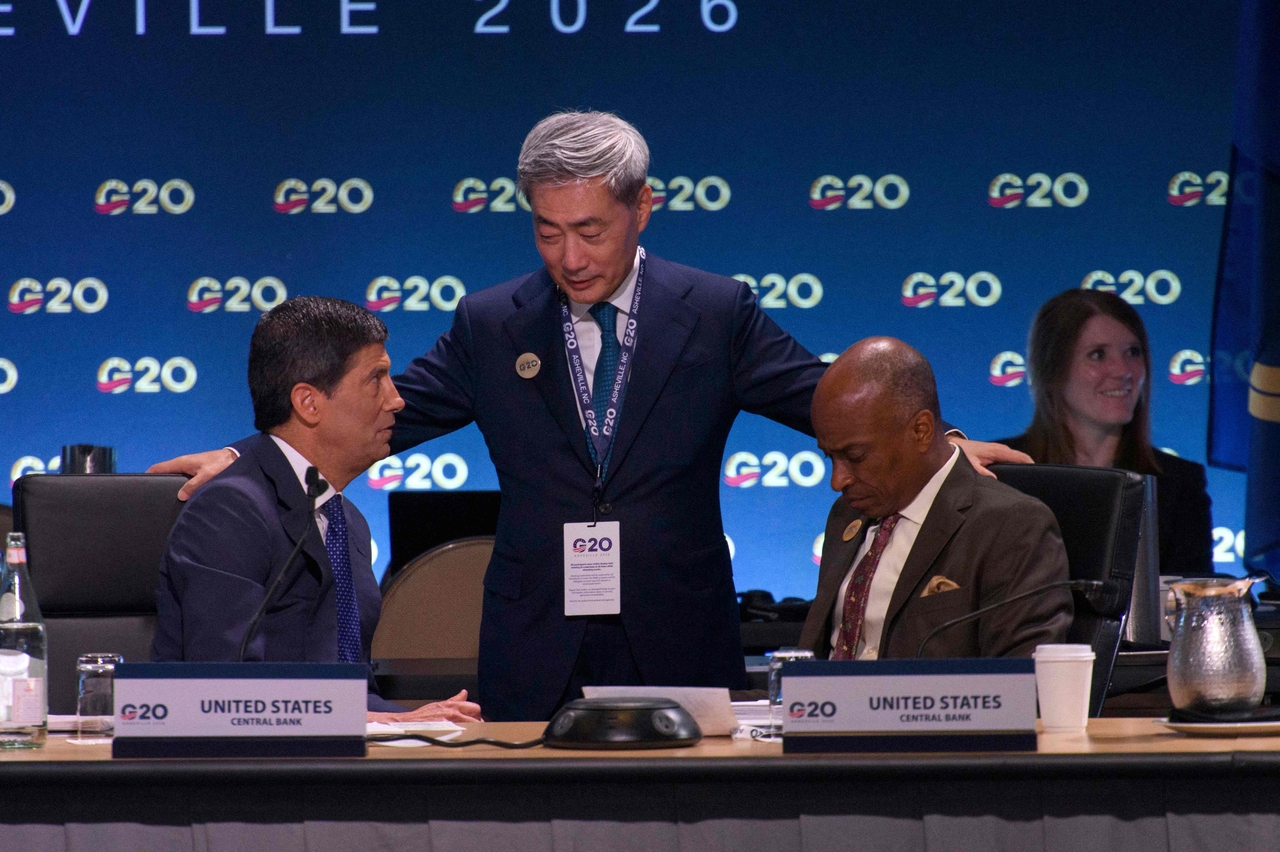
More than two decades after they first squared off over central bank communication, Shin and Woodford have found themselves at the center of the debate once again.
The immediate trigger was this year's Jackson Hole symposium in August, where Warsh explicitly invoked Shin's theory in his remarks. "Excessive pre-commitment undermines policy flexibility and creates a 'hall of mirrors' distortion in which markets and the central bank simply chase each other's signals," Warsh said, adding that the Fed should be committed to "discipline" rather than specific decisions. The "hall of mirrors" concept comes directly from Shin's "Social Value of Public Information" paper, describing a dynamic in which the central bank and markets focus on each other's reactions rather than the real economy, leading to market distortions.
Warsh abolished forward guidance at the first FOMC meeting he chaired after taking office in June and has maintained silence on the monetary policy outlook since — with Shin's theoretical framework serving as the intellectual basis for that approach.
About two months later, on Oct. 12 (local time), Woodford — fresh from winning the Nobel Prize in economics — used a press conference to reassert the importance of communication. "Policy should not be conducted as if it were irrelevant how economic agents understand what the authorities are doing," he said. "Governments should not think of stabilization policy as simply pulling a lever to control the economy."
Meanwhile, Shin contributed a chapter to the third volume of the "Handbook of Monetary Economics," co-edited by Woodford in 2010. The handbook is an academic series covering the theoretical foundations, empirical research and policy mechanisms of monetary economics.
In a paper co-authored with Tobias Adrian, now a special adviser at the IMF, Shin argued that financial institutions were at the heart of the global financial crisis. He proposed that central banks should track financial institutions' balance sheets just as they once tracked money supply.
Woodford's own contribution appeared in the same volume. In his paper on optimal monetary stabilization policy, he argued that central banks achieve better economic stabilization by committing in advance to policy principles. He also made the case for "forecast targeting" — conducting policy with reference to inflation projections — as a means of doing so.
kimstar@heraldcorp.com