Oil tops $100, US 10-year yield breaches 5% before easing; Kospi rebounds late in week
US-China summit on Thursday in focus; NH Investment & Securities sees Kospi range of 6,400–7,500
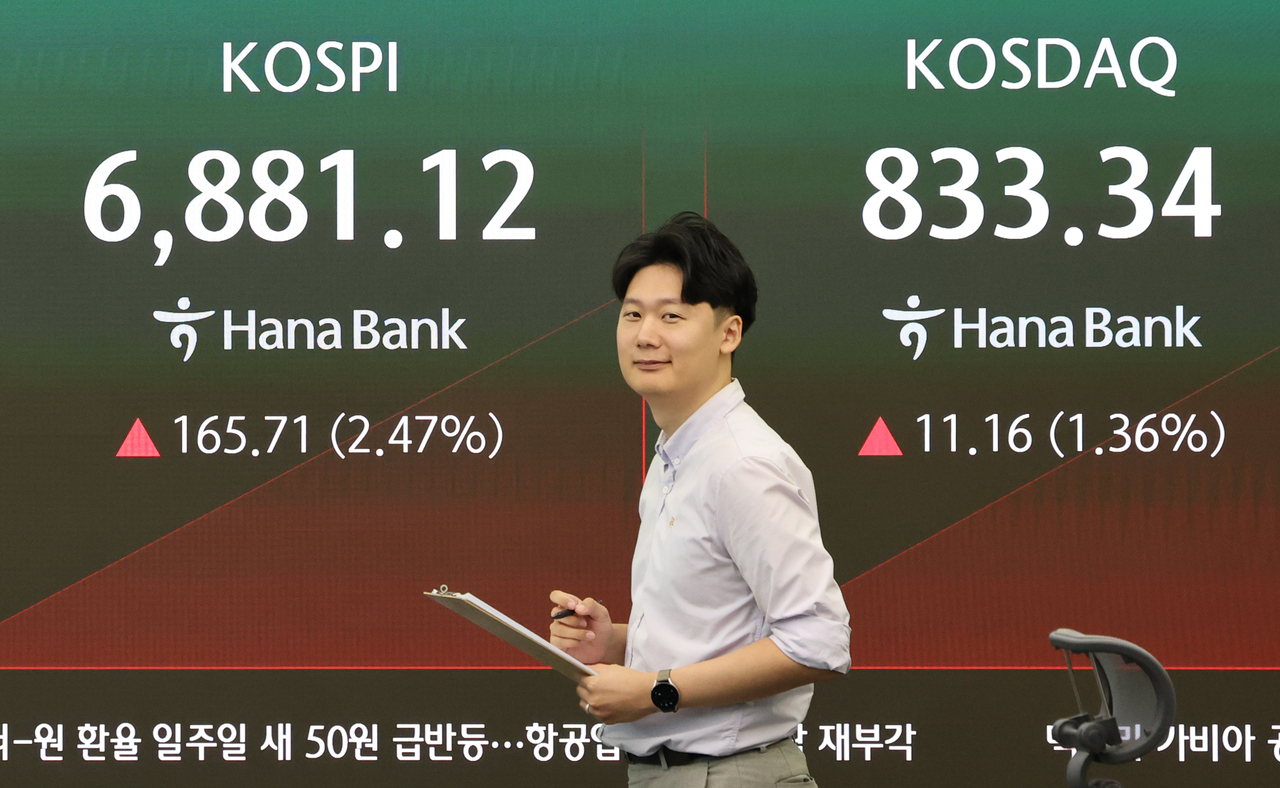
The Kospi, rattled this week by rising crude oil prices, climbing US long-term interest rates and calls for a slowdown in AI development, rebounded late in the week — and markets are now watching whether that momentum can carry through the chuseok holiday. Attention is turning to the US-China summit scheduled for Thursday and to supply-demand dynamics ahead of the long holiday break.
According to Korea Exchange, the Kospi closed Friday at 6,894.23, up 178.82 points, or 2.66 percent, from the previous session. For the week of Sept. 14–18, the Kospi fell 0.23 percent while Kosdaq surged 6.27 percent.
Domestic equities came under pressure early in the week as rising international oil prices, higher US long-term yields and debate over slowing the pace of AI development converged. The yield on the US 10-year Treasury note briefly topped 5 percent during trading, and crude oil surpassed $100 per barrel. Those pressures, compounded by comments from global AI company CEOs about moderating development timelines, dampened investor sentiment, particularly among chipmakers.
The mood shifted in the latter half of the week. After the Federal Open Market Committee announcement, US long-term yields retreated and oil prices stabilized, allowing the Kospi to rebound Friday, led by Samsung Electronics and SK hynix. Analysts said the conclusion of major central bank policy events had helped the market clear one hurdle of macroeconomic uncertainty.
Lee Jae-won, a researcher at Yuanta Securities Korea, said the AI slowdown debate originated from safety concerns but that the likelihood of it translating into broad investment cuts across the industry remained limited. "Since no one can control competitors' development and investment, it is difficult to conclude that the recent semiconductor correction signals a reduction in AI investment until actual order declines are confirmed," he said.
Markets are also watching whether US long-term yields, which fell after the FOMC announcement, can hold their lower levels. The Federal Reserve raised its benchmark interest rate by 25 basis points at its September meeting, setting the target range at 3.75–4.00 percent. The updated dot plot pointed to a higher year-end rate forecast, leaving the door open for further hikes. Some analysts in the brokerage community, however, said the Fed's rate path becoming more concrete had actually reduced uncertainty around monetary policy.
Lee Kyung-min, a researcher at Daishin Securities, said the hawkish stance had been reinforced but that markets had already priced it in. "The Fed's monetary policy path has become more concrete through the dot plot, bringing uncertainty over the terminal rate under control, and long-term bond yields are showing a relatively stable trend," he said.
Oil price movements remain another key variable. Crude surged after disruptions to shipments through the Strait of Hormuz and a shutdown of a Saudi Arabian pipeline, but alternative supply routes have recently begun to fill part of the gap. Shinhan Securities noted that the correlation between international oil prices and US long-term yields has strengthened this year, meaning a drop in oil prices would also ease upward pressure on inflation and long-term rates. Conversely, analysts warned that if the US 10-year yield climbs back above 5 percent and oil prices rise further, the pressure on the Kospi's price-to-earnings ratio would intensify.
The US-China summit set for Thursday at the White House is also drawing close attention. The two countries are expected to discuss AI, trade and rare earths, among other issues. Negotiations on AI — directly tied to US semiconductor export controls on China — are seen as particularly consequential for domestic markets. Analysts said tighter US restrictions on semiconductor exports to China would constrain Beijing's ability to develop low-cost AI, potentially creating a windfall for South Korean chipmakers.
Analysts also noted that the recent share price decline has significantly reduced valuation pressure on the Kospi, even as earnings forecasts for domestic companies remain intact. According to NH Investment & Securities, the projected net profit attributable to controlling shareholders for Kospi-listed companies stands at 806.3 trillion won ($584 billion) this year and is forecast to rise to 1,047.5 trillion won next year, continuing an upward trend. Meanwhile, the 12-month forward price-to-earnings ratio has fallen to 5.5 times, its lowest level on record.
Na Jeong-hwan, a researcher at NH Investment & Securities, said it is doubt about earnings — not the earnings themselves — that is weighing on share prices. "If US long-term yields partially reverse, share prices will push the upper end of their trading range higher as valuations normalize," he said. NH Investment & Securities set its Kospi forecast range at 6,400–7,500.
Near-term volatility is expected to rise, however, as thin trading conditions ahead of the chuseok holiday create a supply-demand vacuum. According to Daishin Securities, the Kospi's average return in the five trading days before the chuseok holiday over the past decade was minus 0.42 percent, while the five trading days after the holiday averaged a gain of 0.68 percent.
Lee of Daishin Securities said that if the market weakens in the short term due to the hawkish FOMC fallout and the pre-holiday liquidity gap, a buying strategy targeting a post-holiday rebound would be valid. "The Kospi's 12-month forward PER stands at 5.29 times, near a historical low, and the 7,600 level — equivalent to a forward PER of six times — is the first rebound target," he said. He added that IT hardware, semiconductors, retail, automobiles, secondary batteries and power equipment were worth watching as sectors where share prices lag underlying earnings.
hajun825@heraldcorp.com