Industrial realignment accelerates after US-Iran war
Defense, construction and energy emerge as top beneficiaries
US weapons stockpile shortfalls erode supplier credibility
Korean defense firms eye European air-defense market beyond Middle East
Daewoo E&C, Samsung E&A seen as LNG beneficiaries
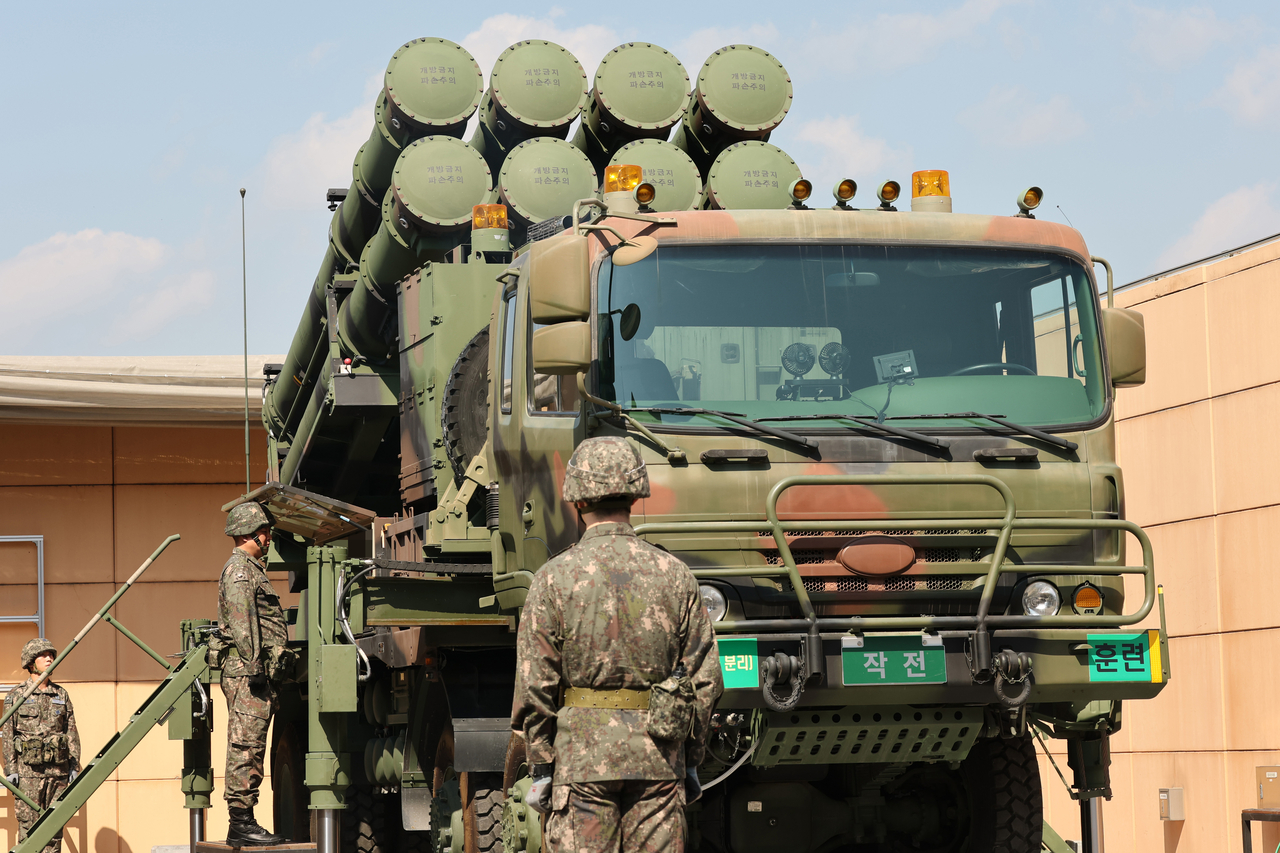
As the US-Iran war enters its seventh month, growing gaps in American defense and energy supply are fueling expectations that Korean companies stand to benefit.
The conflict, which began with US and Israeli airstrikes on Feb. 28, has dragged on longer than initially anticipated after Yemen's Houthi rebels and Iraqi Shia militias joined the fighting. The prolonged war has left the United States grappling with inflationary pressures, depleted missile stockpiles and weakened credibility as a weapons supplier to its allies.
iM Securities recently outlined a scenario in which Korean companies reap indirect benefits across three sectors — defense, construction (LNG and nuclear power plants) and energy (refining) — in a report titled "Industrial Realignment After the Iran War."
The Center for Strategic and International Studies (CSIS) estimated that as of July 27, roughly half of US missile defense and surface-to-surface systems — including Patriot, THAAD and PrSM — had been drawn down from initial stockpiles, while about one-third of long-range ground-attack munitions such as JASSM, SM-2/3/6 and Tomahawk had been expended.
Restocking is proving slow. Although Lockheed Martin has signed a production expansion contract with the US Department of Defense, returning to pre-war inventory levels is expected to take years. Patriot stocks are not projected to recover until mid-2029, THAAD until mid-to-late 2029, and Tomahawk until after the end of 2030.
With the United States struggling with acute missile shortages and production bottlenecks, countries that rely on American weapons — including Switzerland, Estonia and the United Kingdom — have also faced delivery delays.
"Ultimately, the Iran war has weakened not only the US missile stockpile but also America's capacity to meet global defense demand and its credibility as a weapons supplier to allies," said Byeon Yong-jin, a researcher at iM Securities. "The supply gap the US cannot fill will create an opportunity for Korean defense companies to enter the European air-defense market beyond the Middle East."
The report identified Korea's Cheongung-II as a leading candidate to replace the Patriot, citing its high interoperability, price competitiveness and high domestic-parts ratio. The Cheongung-II is integrated with LINK 16, the NATO and US standard tactical data link, allowing it to receive radar and command-post data from existing Patriot air-defense networks and share operational tasks.
Price is another advantage. The per-unit cost of a Cheongung-II interceptor runs between $1 million and $1.3 million — roughly one-quarter the price of Lockheed Martin's latest PAC-3 MSE interceptor, which costs between $4 million and $5 million.
The Cheongung-II also uses 95 percent domestic components, and LIG Defense & Aerospace manufactures in-house the seeker — the core of any guided missile — enabling more stable production ramp-ups than the United States can currently manage.
The UAE (2022, 4.1 trillion won, or $2.97 billion), Saudi Arabia (2023, 4.3 trillion won) and Iraq (2024, 3.7 trillion won) have already procured the Cheongung-II. The report noted that this trend could spread to Europe, pointing to German defense company Rheinmetall's partnership with LIG Defense & Aerospace in June to pursue joint entry into the European and NATO air-defense market.
In construction, the report said Korean EPC (engineering, procurement and construction) firms stand to benefit from the convergence of US energy security priorities and surging power demand driven by AI data centers.
Samsung E&A has carried out front-end engineering design and related work for LNG projects in Texas, Indonesia and Mexico, while Daewoo Engineering & Construction completed the EPC for Nigeria LNG Train 7 — making it the only Korean construction company with LNG liquefaction plant experience. The company is also expecting to sign EPC contracts this year for LNG projects in Mozambique and Papua New Guinea.
Hyundai Engineering & Construction has a track record in LNG terminals and storage tanks, including Kuwait's Al-Zour LNG terminal, and has been selected as the preferred bidder for the Papua New Guinea LNG project in a joint venture with Japan's JGC.
For combined-cycle gas turbine power generation, the report said that if a mega-project such as the 6.3-gigawatt Encinal project in Texas — estimated at between $20 billion and $22 billion — moves forward, Samsung C&T, Hyundai Engineering & Construction, Daewoo Engineering & Construction, DL E&C and Doosan Enerbility could all be in contention.
Nuclear power is also expected to be a major beneficiary. The United States has seen virtually no new nuclear plant construction over the past 30 years, leaving its equipment supply chain and skilled workforce significantly weakened. A US Department of Energy survey found that only a handful of EPC firms — including Bechtel and Fluor — have domestic nuclear project experience, and an estimated 10,000 additional skilled workers will be needed to support new nuclear expansion by 2030.
Korea's APR1400 reactor design and the "Team Korea" consortium are cited as candidates to fill that gap. Led by Korea Hydro & Nuclear Power, the consortium brings together Kepco Engineering & Construction (design), Doosan Enerbility (primary equipment), BHI (auxiliary equipment), Kepco Plant Service & Engineering (maintenance), and Hyundai Engineering & Construction, Samsung C&T and Daewoo Engineering & Construction (EPC).
In the energy sector, refining is identified as the key beneficiary. The Iran war has damaged Russian and Middle Eastern refining capacity, and adjustments to Asian operating rates have left roughly 10 percent of global refining capacity facing supply disruptions.
Capturing that opportunity, however, requires stable crude oil procurement and the ability to run at full capacity. While Chinese and Japanese refiners have been operating at utilization rates of 70 to 75 percent, Korean refiners have pushed their rates to around 90 percent.
"Korean refiners have stronger crude procurement competitiveness than other Asian peers, backed by large-scale purchasing power and strategic alliances with Saudi Arabia," said Jeon Yu-jin, a researcher at iM Securities. "They are translating the elevated refining margins from global supply disruptions into actual profits."
Jeon added, however, that domestic price caps and export restrictions are limiting their ability to fully capitalize on current market conditions. "Even so, maintaining production at levels similar to last year while benefiting from higher product prices is more than encouraging," she said.
jiyun@heraldcorp.com