Cumulative loss ratio up 0.3 percentage points from a year earlier; Chuseok travel demand and rising repair costs cloud second-half outlook
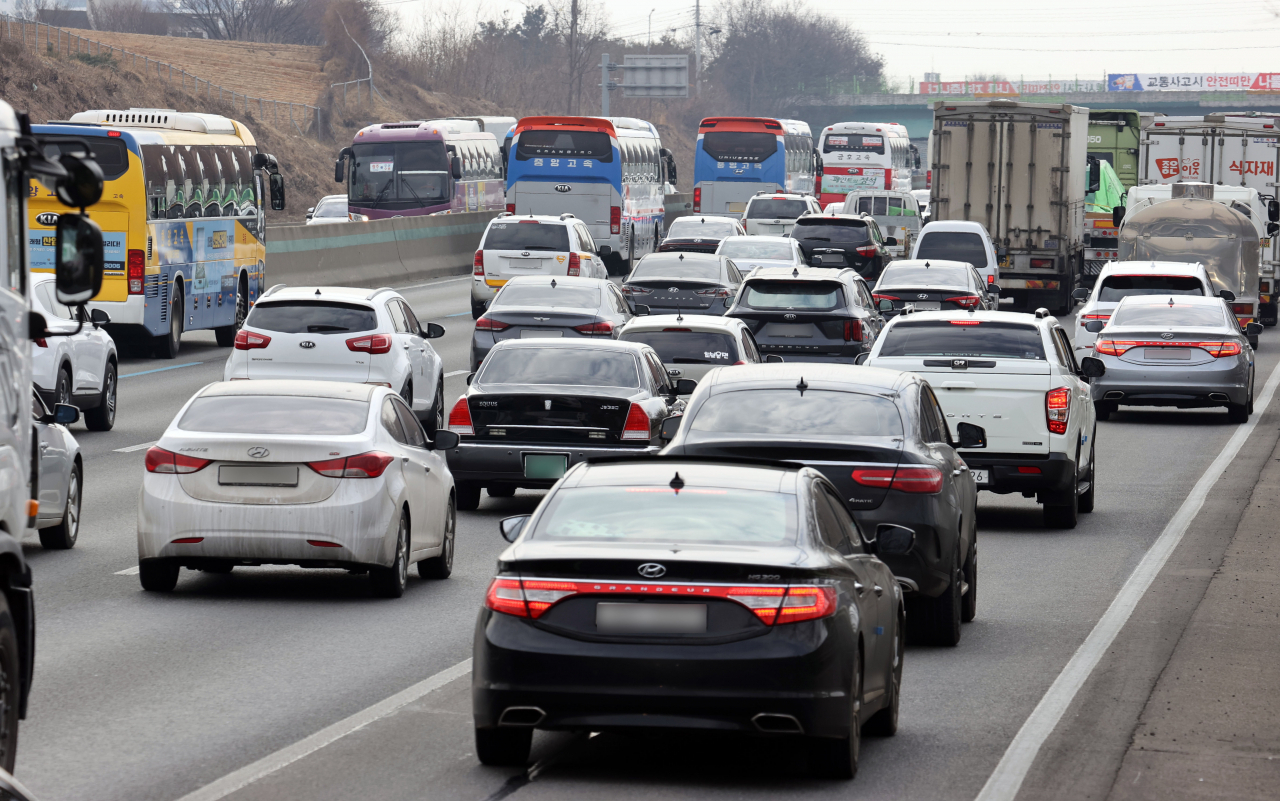
South Korea's auto insurance loss ratio remained in deficit territory through August, rising above last year's level despite a premium increase for the first time in five years. The hike was modest, and the cumulative effect of four consecutive years of premium cuts continues to weigh on results. Analysts expect the loss ratio to worsen further in the second half as Chuseok holiday travel boosts accident volumes and rising repair costs and daily wages push up claims expenses.
The cumulative auto insurance loss ratio for the country's four largest non-life insurers — Samsung Fire, Hyundai Marine & Fire Insurance, DB Insurance and KB Insurance — averaged 84.7% for the January–August period, up 0.3 percentage points from 84.4% in the same period last year, according to the non-life insurance industry Tuesday. By company, DB Insurance posted the highest ratio at 85.0%, followed by KB Insurance at 84.9%, Hyundai Marine & Fire Insurance at 84.6% and Samsung Fire at 84.2%. Meritz Fire recorded the lowest among the five insurers at 82.8%.
Compared with a year earlier, DB Insurance's ratio rose 1.6 percentage points and KB Insurance's climbed 0.7 percentage points, while Samsung Fire improved by 0.7 percentage points and Hyundai Marine & Fire Insurance by 0.4 percentage points. For August alone, the four-company average loss ratio was 84.0%, below the 86.7% recorded in August last year — but a sharp spike in the loss ratio at the start of the year has kept the cumulative figure above the prior-year level.
The loss ratio measures the share of premium income paid out in claims. The industry generally places the break-even loss ratio at around 80%, accounting for operating expenses. Although insurers raised auto premiums by roughly 1 percent earlier this year — the first increase in five years — the loss ratio still sits more than 4 percentage points above that break-even threshold.
"Premiums were raised for the first time in five years, but the increase was limited, and the accumulated effect of four years of premium cuts has yet to fully unwind," an official at the General Insurance Association of Korea said.
The loss ratio is expected to widen further in the second half. Heavier travel ahead of the Chuseok holiday is likely to push up both the number of accidents and the cost of personal injury per incident. Ongoing increases in vehicle repair rates and daily wages for workers are adding to claims costs, while prolonged treatment for minor-injury patients and future medical expenses continue to erode profitability.
"The rise in travel demand during the Chuseok holiday is expected to increase both accident frequency and per-accident injury costs, and the loss ratio is forecast to deteriorate further as cost-push factors — including continued increases in repair rates and daily wages — remain widespread," the association official said.
The auto insurance segment posted an underwriting loss of 184.8 billion won ($133 million) in the first half of this year, swinging to a deficit on a half-year basis for the first time in six years. Although premium increases lifted sales, the pace of rising costs — including hospital treatment fees and repair labor charges — outstripped the revenue gain.
won@heraldcorp.com