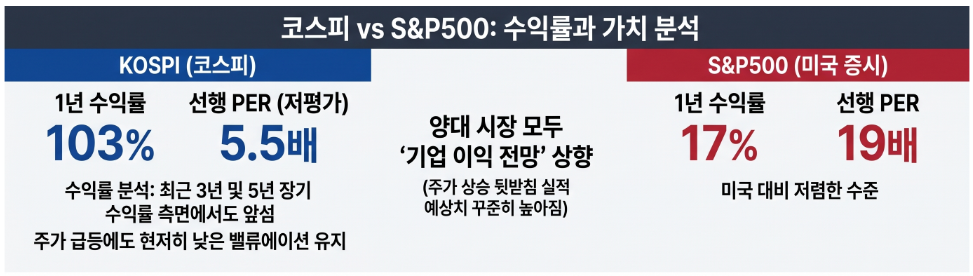
Kospi up 103%, S&P 500 up 17% over the past year — but 3- and 5-year returns also favor Kospi
Kospi 12-month forward PER at 5.5x vs. S&P 500's 19x — future earnings are the key
Kospi profit growth concentrated in semiconductors; AI spending, interest rates and exchange rate are wildcards for US stocks
The Chuseok holiday begins Thursday, offering a moment to take stock of how Korean and US equity markets have performed this year — and the gap has been striking. Over the past year, the Kospi more than doubled while the S&P 500 gained 17 percent.
The Kospi closed at 7,007.72 on Monday, up 103.40 percent from its Sept. 19, 2025 closing level of 3,445.24. Over the same period, the S&P 500 rose 17.08 percent, from 6,631.96 to 7,764.70.
Extending the window only widens the gap. Since Sept. 21, 2023, the Kospi has climbed 178.64 percent, compared with 79.32 percent for the S&P 500. Over the five years since September 2021, the figures stand at 123.14 percent and 75.16 percent, respectively.
Past returns alone, however, are a poor guide to future investment decisions. Beyond how much a share price has risen, investors also need to ask whether that price is expensive relative to the earnings a company is expected to generate going forward.
Is the Kospi, after doubling, still cheap?
A large share-price gain does not automatically mean a stock is expensive. The price-to-earnings ratio, or PER, measures how many times a company's earnings per share its stock is trading at. If a share costs 10,000 won ($7) and earnings per share are 1,000 won, the PER is 10 times — calculated by dividing the share price by earnings per share.
When earnings rise, the PER falls even if the share price stays flat. A stock at 10,000 won with EPS doubling from 1,000 won to 2,000 won sees its PER drop from 10 times to 5 times. Conversely, if earnings hold steady while the share price doubles, the PER rises to 20 times.
Despite more than doubling over the past year, the Kospi's PER remains lower than the S&P 500's. According to Han Ji-young, a researcher at Kiwoom Securities, the Kospi's 12-month forward PER stood at 5.5 times as of Monday. Goldman Sachs data show the S&P 500's 12-month forward PER has eased from 22 times at the start of the year to around 19 times recently. The 12-month forward PER is calculated using projected earnings over the next 12 months.
The earnings outlook for Kospi-listed companies has also been revised upward. According to Kiwoom Securities, the combined operating profit forecast for Kospi-listed companies this year stood at 989.7 trillion won as of Aug. 27, up 14.8 trillion won from 974.9 trillion won at the end of July. The forecast for next year also rose over the same period, from 1,310.9 trillion won to 1,314.3 trillion won.
Earnings estimates for the S&P 500 have similarly improved. The index's 2026 EPS forecast climbed 6.80 percent, from $338.99 on June 13 to $362.03 on Sept. 11. The 2027 EPS forecast rose 6.13 percent, from $392.48 to $416.53.
Kim Sung-hwan, a researcher at Shinhan Securities, said past periods of declining PERs and weak equity markets were accompanied by slowing earnings growth — a condition he said does not apply today. The S&P 500's 12-month forward EPS is expanding rapidly, he said. "The S&P 500's 12-month forward EPS is currently rising at the fastest pace in history and is still accelerating," Kim said. "The situation is fundamentally different from past bear markets."
The key variable that will determine the relative valuation of the Kospi and the S&P 500 is future corporate earnings — and which sectors and companies are driving that growth.
Samsung Electronics and SK hynix account for 63% of Kospi profits
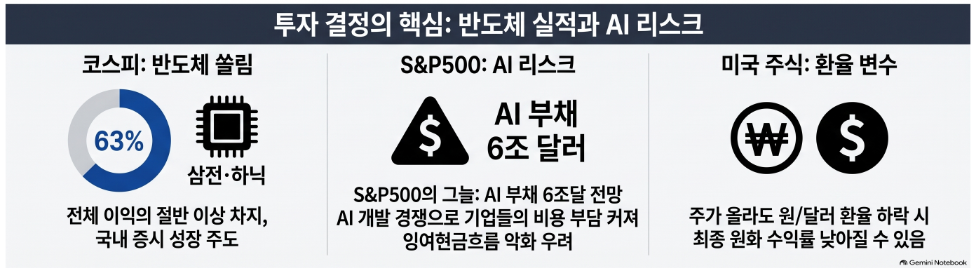
The Kospi's earnings growth is heavily concentrated in semiconductors. According to Korea Exchange, the combined operating profit of 634 KOSPI-listed companies with December fiscal year-ends — excluding financial firms and certain others — reached 388.15 trillion won in the first half of this year on a consolidated basis, a 254.15 percent increase from the same period last year.
Of that total, Samsung Electronics and SK hynix together posted operating profit of 244.88 trillion won, accounting for 63.09 percent of the group total. As of Monday, the two companies' combined market capitalization stood at 2,966.44 trillion won, equal to 51.28 percent of the Kospi's total market capitalization of 5,784.65 trillion won.
Semiconductors are also the primary driver of upward earnings revisions. According to Samsung Securities, the 12-month forward operating profit forecast for profitable KOSPI 200 companies was revised up 3.5 percent over the past month, with semiconductor stocks accounting for 3.3 percentage points of that gain. Samsung Electronics' 12-month forward operating profit forecast rose 4.3 percent, from 491.9 trillion won on Aug. 21 to 512.99 trillion won on Friday. SK hynix's forecast climbed 4.1 percent over the same period, from 350.1 trillion won to 364.28 trillion won.
The Kospi's earnings trajectory therefore hinges on Samsung Electronics and SK hynix. The critical question is whether the upgraded forecasts translate into actual results.
S&P 500 rides AI earnings growth, but high rates are a headwind
Earnings forecasts for the S&P 500 are rising, led by AI companies, but the cost of AI investment is climbing just as fast. Cash is being consumed more quickly than expected, pushing up borrowing needs and interest burdens.
According to Meritz Securities, capital expenditure forecasts have approached $1.2 trillion annually as AI investment accelerated sharply after competition in AI development intensified in 2024. The point at which free cash flow for major companies turns negative was originally expected in the first half of next year but has been pulled forward to the fourth quarter of this year. The negative free cash flow shortfall is projected to exceed $100 billion.
Debt is also mounting rapidly. On-balance-sheet liabilities at major hyperscalers have reached $500 billion. Total obligations — including off-balance-sheet investment commitments — were estimated at around $3 trillion in the second quarter of this year. Meritz Securities projected that, if investment continues at the current pace, total debt could approach $6 trillion by the first half of next year.
"When cash runs short amid rising AI investment, borrowing inevitably increases," said Yun Yeo-sam, a researcher at Meritz Securities. "If the current investment race continues, debt will grow even faster." He added that if the Federal Reserve raises interest rates while debt is expanding, the interest burden will compound the pressure.
S&P 500 up 75% over 5 years — but 106% in won terms
For Korean investors putting money into the S&P 500, the exchange rate is another variable that shapes returns. Because US stocks are traded in dollars, movements in the dollar's value against the won affect returns just as much as share price changes.
The S&P 500 rose 75.16 percent from 4,432.99 on Sept. 17, 2021 to 7,764.70 on Monday. Over the same period, the won-dollar exchange rate moved from 1,175 won to 1,381 won. Factoring in both the index gain and the currency move, the return in won terms was 105.87 percent — boosted by the dollar's appreciation on top of the index's rise.
This year, the dynamic has reversed. The S&P 500 has gained 13.43 percent since the end of last year, but the won-dollar rate has fallen from 1,439 won to 1,381 won. Once the exchange rate is factored in, the won-denominated return shrinks to 8.86 percent.
Ultimately, when investing in either the Kospi or the S&P 500, future corporate earnings and current valuations are not the only factors that determine outcomes — the exchange rate plays an equally decisive role.
hajun825@heraldcorp.com