SME owners enrolled: 52,104, up 3.9% from a year earlier
Artists' enrollment rate at 23.5%; only 2.0% joined through welfare foundation
Government plans to extend mandatory coverage to high-risk self-employed workers
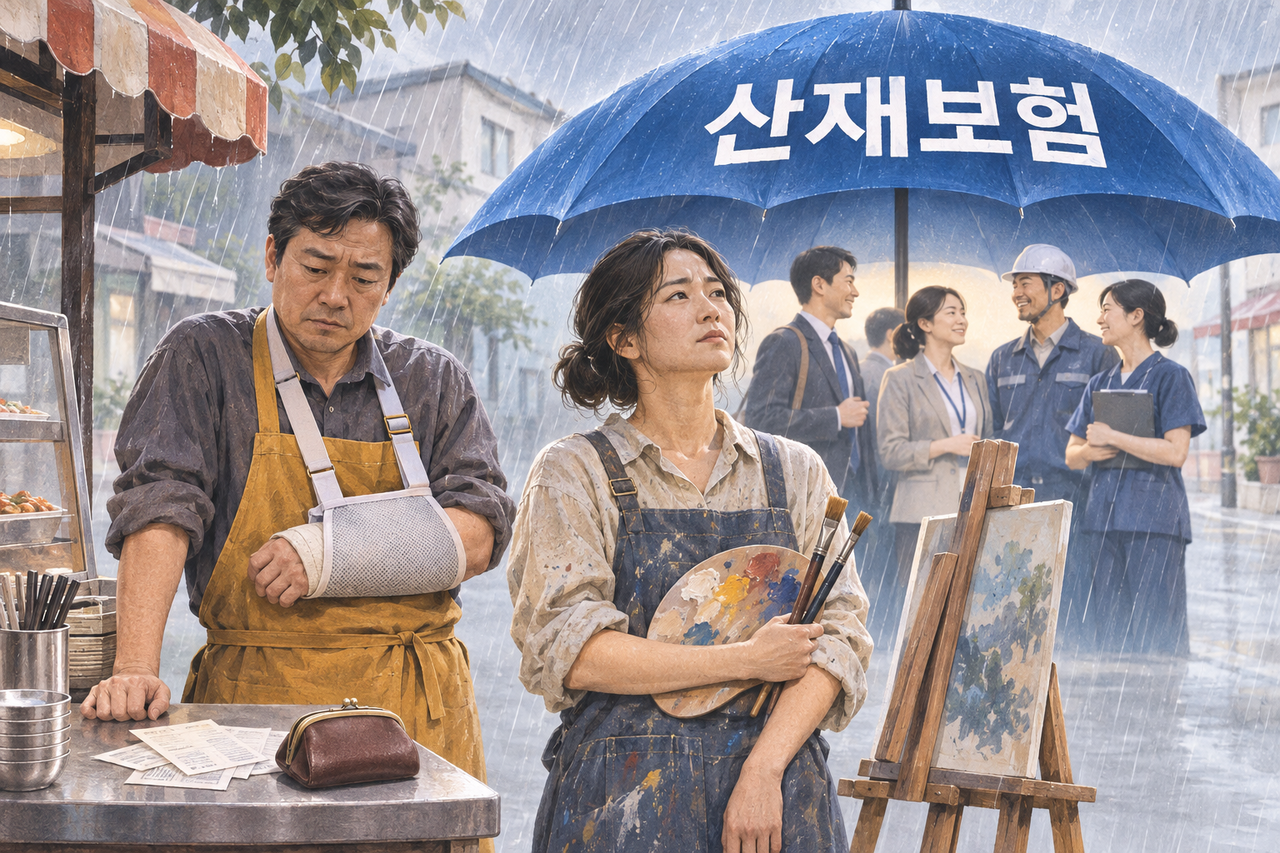
Annual benefit payouts under South Korea's industrial accident compensation insurance system have surpassed 8 trillion won ($5.96 billion), yet coverage for the self-employed and freelance artists remains thin.
The number of small and medium-sized enterprise owners who have voluntarily enrolled in the system has stalled in the 50,000 range, and a government survey found fewer than one in four artists is covered. As the government pushes toward universal workers' compensation insurance, expanding enrollment while easing the premium burden has emerged as a key challenge.
According to the Ministry of Employment and Labor's 2025 Industrial Accident Compensation Insurance Annual Report released Sunday, the number of SME owners who voluntarily enrolled last year reached 52,104 — up 1,961, or 3.9 percent, from 50,143 the year before.
Workers' compensation insurance for SME owners, which covers work-related injuries sustained by the owners themselves, is structured as an opt-in system that requires individual application. Coverage for a business's employees and coverage for the owner are treated separately: even when workers at a business are covered, the owner is not automatically protected.
Owners must also pay premiums out of pocket. A small-business owner injured on the job and forced to suspend operations faces not only medical bills but also a sudden loss of sales and income — yet without voluntary enrollment, the owner has no recourse to workers' compensation benefits for personal injuries.
Artists face similarly large gaps in protection. The Ministry of Culture, Sports and Tourism's 2024 Survey on the Status of Artists found that as of 2023, only 23.5 percent of artists were enrolled in workers' compensation insurance. Of those, 21.5 percent were covered through an employer, while just 2.0 percent had enrolled through the Korea Artists Welfare Foundation. Some 76.5 percent reported having no coverage at all.
Freelance artists, whose incomes are irregular, may find it difficult to keep up with premium payments. That said, they do not bear the full cost alone. The Korea Artists Welfare Foundation this year subsidizes 50 percent of premiums for artists who meet eligibility requirements — such as holding certified artist status — regardless of the coverage rating they choose.
The overall reach and payout volume of the workers' compensation system have been growing. At the end of last year, the system covered 3.207 million workplaces and about 22.598 million workers. Total benefits paid last year reached 8 trillion won.
Premium collections from the platform and gig worker segment — which includes delivery riders and designated-driver services — came to 485.77 billion won, up 104.42 billion won, or 27.4 percent, from 381.35 billion won the year before. The increase is attributed to a broader mandatory coverage scope driving higher enrollment and collections.
Workers' compensation insurance launched in 1964 covering mining and manufacturing workplaces with 500 or more full-time employees, and has since expanded to encompass most wage workers and gig workers across a range of occupations. Bringing business owners and artists — who remain in the voluntary enrollment category — fully into the system is still a work in progress.
The government plans to begin by making enrollment mandatory for self-employed workers in high-risk occupations and then extend coverage in stages, with the expansion targeting as early as next year alongside premium support measures.
The Ministry of Employment and Labor is working through a comprehensive support task force for industrial accident compensation and workplace rehabilitation, launched in March, to discuss reforms. The workers' compensation subcommittee is reviewing options to expand coverage based on field demand from voluntary enrollees, including artists, self-employed workers in high-risk sectors, and agricultural, forestry and fishery workers at unincorporated operations with fewer than five employees.
The central question is how to distribute the premium burden that comes with broader coverage. Designing the right level of support for enrollees with low or irregular incomes — so they can sustain premium payments over time — will determine whether universal workers' compensation insurance becomes a practical reality.
fact0514@heraldcorp.com